One broker says the usual assumption about rate hikes doesn't hold up
With reporting by Fergal McAlinden
Despite the pushback from the White House regarding yesterday’s decision by the Federal Reserve to raise its benchmark rate by 25 basis points, the mortgage industry seemingly believed the central bank got the decision right.
More than two-thirds of those who voted in a Mortgage Professional America LinkedIn poll thought the Fed made the right call. Some of those who believed they didn’t get it right actually thought a higher hike was needed.
One of the main reasons why is that history has typically shown that mortgage rates don’t always move in the same direction as a Fed rate action. With the 10-year Treasury yield soaring in recent weeks, the hope was that rate hikes from the central bank would actually cause those yields to fall, which they have so far on Thursday.
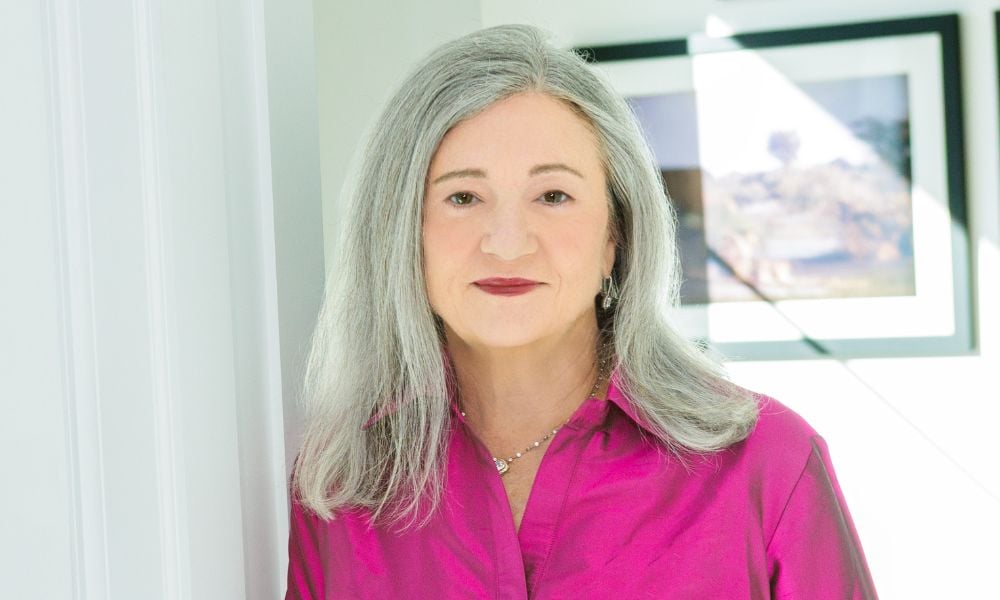
Melissa Cohn (pictured top), regional vice president at William Raveis Mortgage, said a rate hike can work in the mortgage market's favor under the right conditions.
"Rate hikes can be good for the mortgage market, because if the bond market feels that the Fed is fighting inflation and doing what they can and having any sort of impact, bond yields will rally, bond yields will come down, and mortgage rates will go down," Cohn told Mortgage Professional America. "There are examples in history in the past 20 years showing, I think it's like over three times when the Fed was in a rate-hiking cycle, that mortgage rates actually ended up lower."
Watching the bond market
Brokers don’t have to look too far into the past to see when mortgage rates and Fed rate decisions moved in opposite directions.
"In 2025, when the Fed was cutting rates, mortgage rates went up," Cohn said. "So the direction of the Fed and Fed funds rates has a direct impact on the prime rate and any borrowing that's impacted by the prime, such as a home equity loan, credit cards. Those are all impacted in the opposite direction. But mortgage rates can be very contrary to what the Fed does. It's all about the bond market and its anticipation and sensitivity to inflation."
Fed chair Kevin Warsh pointed to that same bond market when explaining why yields had already climbed heading into Wednesday's meeting.
"I will give you three reasons, but I would say these things tend to be overdetermined," Warsh said. "First is economic strength. The second reason is the competition for capital. The third is geopolitics."
One veteran bond trader had an even more specific theory about what Wednesday's decision would do to prices.
Billy Abrams, president of Imperial Fund Securities, predicted the outcome before the Fed's decision was announced.
"I personally think that if the Fed were to shock everybody and raise rates, I think the bond market would firm up," Abrams said. "A more aggressive Fed claiming they're going to fight inflation would actually help the long end of the bond market."
Mike Fratantoni, SVP and chief economist of the Mortgage Bankers Association, offered a similar read on why Wednesday's headline number mattered less than it might seem.
"Longer-term rates, including mortgage rates, had already baked in the expectation of hikes at this and future meetings," Fratantoni said. "Thus, longer-term rates have not moved much in response to this news."
That distinction, according to Cohn, is the one borrowers most need to understand after a decision like Wednesday's.
"I just think that people shouldn't think that just because the Fed raised rates, that means that mortgage rates are going up," she said.
Elevated energy inflation
Cohn said the bigger driver of where rates go from here has little to do with the Fed at all. Until the conflict in the Middle East is resolved and oil prices retreat, energy inflation is going to remain a problem for mortgage rates.
"A Fed rate hike or a Fed rate cut, I think at the moment, are completely overshadowed by what's going on in the Middle East and the price of oil," she said. "I think that where rates will go will follow the price of oil, because oil creates inflation.”
Warsh addressed that exact tension directly when asked about energy prices during his press conference.
"We cannot affect individual prices," Warsh said. "We will ensure that any change in relative prices doesn't broaden out and have second and third effects in the economy. That is what we are tasked to do and will do."
Cohn agreed that a raise in the Fed funds rate might not stop inflation, but could slow down its effects on the economy.
"Even if they continue to hike rates, that may slow down consumption here and can help maybe slow the rate of inflation," she said.
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.