Beckwith promises brokers will see the light at the end of the tunnel, but they must keep moving
The mortgage rate environment hasn’t ended up the way that brokers and consumers were hoping for when 2026 got underway.
While there are still deals getting done, the higher-for-longer rates that are now forecast have added headwinds to the space.
For originators who got into the business in the aftermath of the pandemic, when loans were easy to come by, the last couple of years have presented a different perspective on getting mortgage deals done.
One veteran of the industry says it’s more than just deals slowing down. It is the one-two punch of falling income and licensing rules that still hold originators to their personal finances.
However, that same veteran wants to remind brokers that better times are ahead.
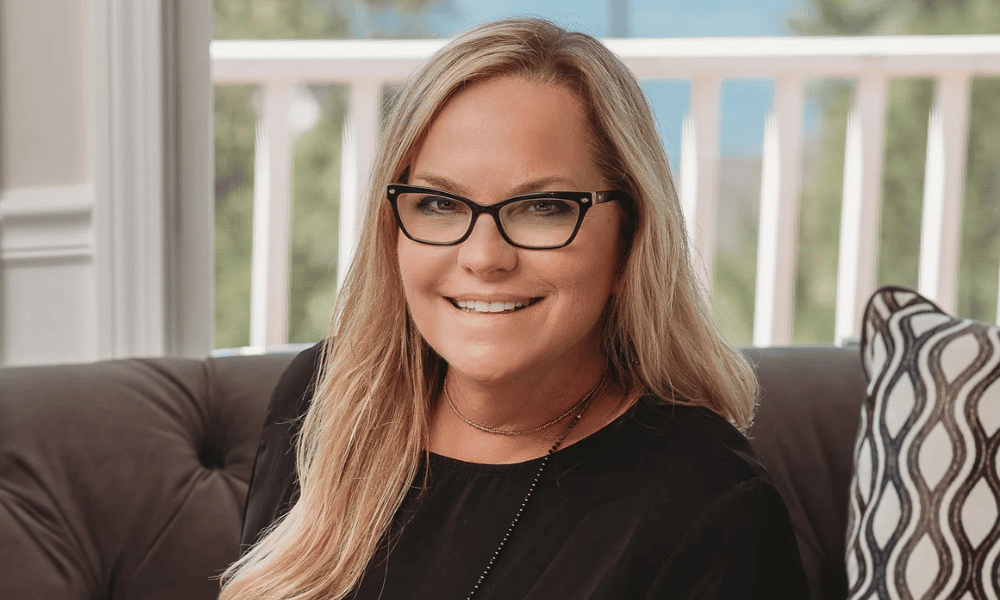
Christine Beckwith (pictured top), founder and president of 20/20 Vision for Success Coaching & Consulting, has been in the business since 1988 and said she gives brokers the same reminders she gives herself on the hard days. She recently shared that message at the Association of Independent Mortgage Experts (AIME) Fuse event in Austin.
"Going into the unknown is a scary thing, but they need to trust me when I tell them it is not a plank that they're walking," Beckwith told Mortgage Professional America. "They are walking through a tunnel where they can't yet see the light. I promise them they will see it, but they've got to keep moving. They just got to keep moving."
Back to basics
Beckwith's first piece of advice is for veteran originators whose referral business has slowed down. If 10 realtors have sent you business for 10 years and that was enough to stay busy, she asks, what do you do when little is flowing from those 10?
"A lot of really veteran originators are resisting something that I call the CEO oversight of sales, which is that we always have to be acquiring new clients and new referral partners," she said. "I challenge them to examine and not assume that the poor referral base is just the market, to really look at what they're getting and go back to the basics."
She said the basics include scoping out a geographic area, using the industry's vetting tools, and not writing off a realtor who already works with another lender. Independent brokers are CEOs of their own shops, she said, and nobody is coming to tell them to rebuild their sales funnels.
Beckwith also encouraged brokers not to write off cash-out refinances, even in an elevated market. JD Power's 2026 U.S. Mortgage Servicer Satisfaction Study found 59% of borrowers are financially vulnerable, stressed, or overextended and 30% fear losing their home.
The focus needs to be on the benefit of the move, rather than the rate change, she said.
"Sure, your rate's going to go up," Beckwith said. "But if you get rid of this $30,000, $40,000 unprecedented high revolving compounding interest debt on credit cards and you maybe grab some cash, put yourself in a better reserve position, that increase to your mortgage rate, even though your mortgage payment may go up, your overall savings may be paramount. Your re-securing and resetting of your financial position may be paramount."
Finding your lemonade stand
Beckwith lived through 2008 as a veteran originator, and she said the comparison with today is one of her reasons for hope. Back then, she said, originators had to learn loan modifications and short sales from scratch.
"There is a higher population of homeowners," she said. "There is a lower population of mortgage professionals, and we have equity. This isn't the same as back then."
In her view, brokers need to know exactly which products they can lean on right now, and she named debt service coverage ratio (DSCR) loans and non-qualified mortgage (non-QM) loans.
"I compared those things to lemonade stands," she said. "When a season comes, we pop up a lemonade stand. They're going to need to find their lemonade stands. It's DSCR; it's non-QM. These are the tools that are going to bring them through. That season will end, and they have to go forward into the unknown knowing this isn't the end of their careers."
Beckwith expects consolidation, mergers and acquisitions across the industry. She tells brokers to make decisions with a clear head, including vetting any new employer for products, pricing and service before taking a sign-on bonus.
Falling income can push originators toward desperate decisions, Beckwith said, and the industry has been through that before.
"Fraud levels went up dramatically in '07 and '08 through loan originator desperation," she said. "One deal, one commission, no matter how desperate you need that commission, is not worth your career."
Her firm has built new coaching that goes deeper into the tactics behind this advice. She said some loan officers have left coaching for financial reasons, but many have stayed despite the strain of paying tuition.
"I really am operating from a place of keeping my lighthouse on during a hard time to give as many people seats as I can, not worrying so much about my own profitability, although I do need to break even, but fighting for people to have a seat, being more of a community leader than I've been an entrepreneur, if you will," she said.
For more information or to contact Beckwith regarding coaching opportunities, email her at [email protected].
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.