As the political landscape shifts, Marty Green on what possible regulatory changes mean for brokers
While most of the attention for the recent midterm elections surrounds the changes coming to the Senate and House of Representatives, many state and local offices swung politically during the November elections.
With mortgage regulations controlled at both the federal and state level, a shift in local politics can also have a big impact on a broker’s business.
A change in who holds those offices can change what regulators prioritize, from how loans are priced to how closely files are reviewed.
Prior to the election, one mortgage attorney said that brokers and lenders should already be preparing for what comes next, including what happens with the White House in 2028.
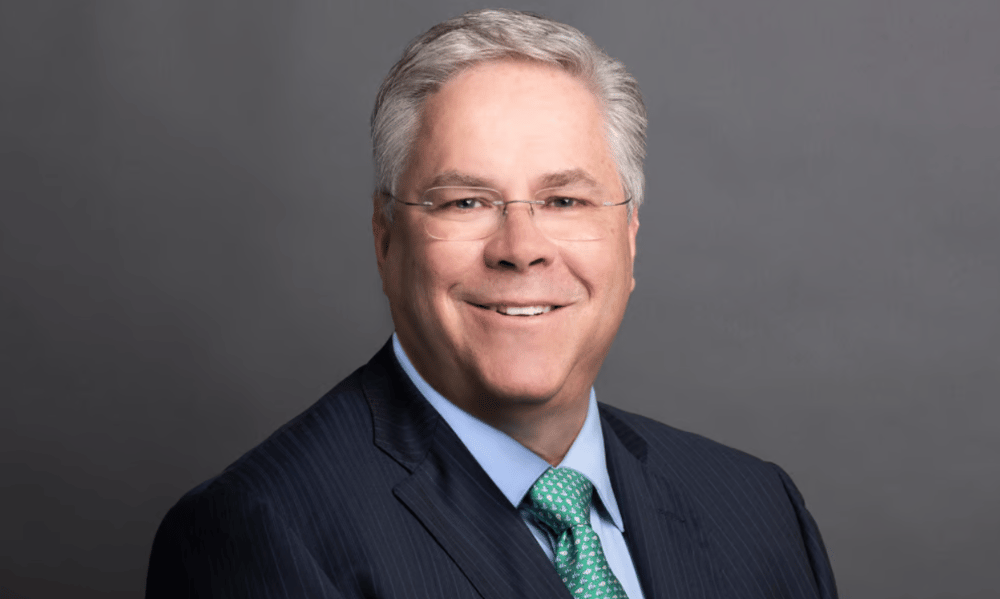
Marty Green (pictured top), principal at Polunsky Beitel Green, said a change of administration within two years is already changing the regulatory mindset a little on the compliance front.
"The new one will probably be a lot less laissez-faire than this one is," Green told Mortgage Professional America. "And so people need to be mindful of that because of the lookback period. And they should have been mindful of it before, but they really need to be now."
State activity and pricing
Green does not expect many federal proposals in the next two years, but there could be more action at the state level.
"I don't think you're going to see a lot in the next two years, at least not on the federal level," Green said. "You may see more on the state side."
The results have put more state offices in Democratic hands. Democrats won a majority of governorships for the first time in 16 years, flipping Alaska, Georgia, Iowa, Nevada, Ohio and Texas, and flipped legislative chambers in several states.
Green would like to see regulators coordinate how they deploy AI, he said, so that compliance does not vary from one regulator to the next.
"We just don't want it to be New York that sort of leads the charge," Green said.
Some regulators are likely to look harder at pricing as consumers feel strained, Green said.
"If you're on the broker side, are you making sure that they're getting the best rate?" Green said. "You're going to certainly see some regulators that will be more aggressively looking at that, particularly if they see something that looks a little bit out of whack based upon general pricing that they're seeing."
Credit scoring changes should help borrowers at the margins, he said, through pricing and through better scoring.
"I think that's a positive net for the industry, and I think it'll help somewhat with affordability on the margins," Green said. "It's mostly going to be on the margins at this point. But as the market recovers, as interest rates sort of hopefully get more normalized downward, then I think it'll make a bigger impact."
Scoring and AI review
A bi-merge, which would require two credit reports instead of three, was rumored to be announced at the Mortgage Bankers Association (MBA) annual event by FHFA director Bill Pulte. So far, that hasn’t happened, but many in the industry still expect that change in the future.
Green said it and the VantageScore change would both have an impact, with investors likely to adopt them over time.
"I think it's really just going to be in terms of how people operationally choose to deal with it," Green said. "I think the bi-merge thing is huge, probably bigger than the VantageScore at the outset.”
The Texas Finance Commission, on which Green serves, discusses AI with the state's banking and mortgage regulators, and he said regulators are weighing how to use it.
"One of the things that's going to be interesting from a regulatory standpoint is how regulators may start deploying AI to broaden the dataset that they're looking at," Green said. "It's going to allow them to do that with less manpower, which has been the principal impediment in the past."
Prasad Kodibagkar, chief technology officer at Polunsky Beitel Green, said AI changes how much of a loan population can be checked.
"In the past, you did inspect, but you did sample," Kodibagkar told Mortgage Professional America. "Now with a lot more computing power and AI's decision-making, which you can get pretty deterministic, your sample set can be the whole population.”
As that technology is rolling out at the regulator level, it is also rolling out to lenders. Green noted that a broker's own lender is likely to start this kind of review first.
"The lender who is accepting those loans is also going to have that same resource, and they're probably going to deploy it before the regulator does," Green said.
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.