Fairview's Glen Weinberg asks who holds the bag as banks run out of room to kick the can
While commercial deals often get done regardless of the rate environment, one area where the impact is still felt is when deals come up for refinancing.
Many deals completed in the low-rate environment that followed the onset of the COVID-19 pandemic are coming up for renewal in 2026 and 2027.
Soaring Treasury yields have pushed mortgage rates back into the mid-7s for 30-year conventional mortgages, with commercial rates often higher than that.
One veteran lender in the commercial and private money space is wondering what is going to happen when these loans come due over the next year, especially if market conditions remain challenging with elevated cap rates and sector distress.
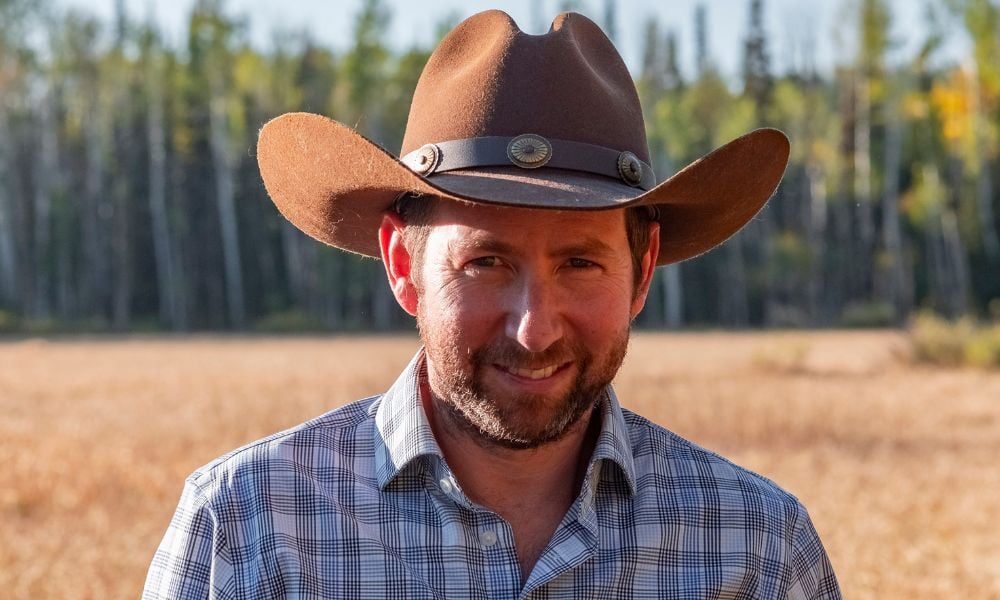
Glen Weinberg (pictured top), chief operating officer and partner at Fairview Commercial Lending, said commercial real estate is a bigger risk than residential. He has been in the industry for more than 30 years and has been through every cycle, he said.
"How the hell do all these properties get refinanced?" Weinberg told Mortgage Professional America. "And who eats that distress, especially in the office sector?"
Cap rates and the can
Some multifamily properties were bought at cap rates of 2%, 3% or 4%, Weinberg said, and the cap rate on them is now about 6%.
"That means that property is worth half of what it was on a 2% or 3% cap rate," Weinberg said.
About 17% of the $5.0 trillion in outstanding commercial mortgages, or $875 billion, were set to come due in 2026, according to a February survey from the Mortgage Bankers Association (MBA). Trepp's delinquency rate for commercial mortgage-backed securities (CMBS) was 7.87% in October, with office at 12.33%, the highest of any property type, and multifamily at 8.09%.
Office is where he expects the worst of it, Weinberg said, with multifamily to follow.
"Rents can't cover that spread," Weinberg said. "What happens in commercial real estate with cap rates doubling? Which means their values have to basically be cut in half. Who the hell is going to hold the bag? And how does that market shake out? And I think that's a much bigger risk than the residential."
Banks have been extending loans on these properties, Weinberg said, and he expects that to run out at some point.
"Here we are in '26, and the can's still getting kicked down the road,” Weinberg said. “At some point, you can't kick the can any further. The can falls in the hole, or gets in the river. The can’s gone."
Some Denver office buildings have traded at steep discounts to their values from three or four years ago, according to Weinberg, who lives in Colorado.
"Someone just took a big hit, but we aren't seeing that show up anywhere yet," Weinberg said. "But you can't hide the donut. Eventually the mouse finds the donut."
Distress and opportunity
Fairview is a niche player, in Weinberg's words, and he sees the turmoil as an opening for lenders like it.
"As all of these banks continue to buy each other, especially in the small balance commercial, or even on the residential, a lot of deals don't fit for whatever reason," Weinberg said.
While the market is facing challenges, Weinberg sees a second side to the distress.
"There are going to be some good opportunities because in turmoil and transition, someone always makes money," Weinberg said.
Scale will not save lenders that compete with the biggest banks, Weinberg said, because those banks invest heavily in technology.
"The only way you're going to survive is a niche product," Weinberg said. "It's not going to be the volume games where you're trying to close like 1,000 loans a month. Someone's always going to beat you at that game."
Looking back at 2008, he laid out what he thinks the market got wrong.
"One of the problems with '08 is we didn't really understand the mortgage mess we were in because people were basically taking securities and stripping them to different payment streams," Weinberg said. "Nobody knew what the hell they actually had."
Fairview funds its loans in cash, Weinberg said, after what the firm went through in 2008. It had been selling loans into securities, and that market stopped.
"We're funding everything in cash. So we aren't leveraged. We're 100% unleveraged in our portfolio, and we've passed up huge opportunities because I refuse to take on leverage," Weinberg said. "So yeah, we'll get to see how it works in the next cycle. So far so good, but we thought in the last cycle that we were going to be okay, and yeah, we made it through, but it was quite the painful experience."
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.