Mortgage and protection professionals welcome the FCA's pure protection market study but say personalised, data-led support must follow

The Financial Conduct Authority (FCA) has published the final report of its Pure Protection Market Study, concluding that while competition in the market functions well for those who hold cover, millions of UK adults remain without it, and the regulator is now partnering with industry, government and consumer groups to address that.
The report found that around 58% of adults have no life insurance, critical illness cover or income protection, with 59% of that group having never considered it. Figures from the FCA show that the scale of the protection gap leaves a significant proportion of households financially exposed to death, serious illness or loss of income.
To help expand coverage, the FCA is joining forces with the Money and Pensions Service, the Digital Property Market Steering Group, the Protection Distributors' Group and the Association of Mortgage Intermediaries (AMI). The plan centres on prompting consumers to think about protection at key moments – buying or renting a home, becoming a parent – while the AMI leads work to help advisers improve how they discuss cover with clients. The regulator is also inviting firms to participate in a TechSprint focused on innovation in the market, with expressions of interest sought by 13 November.
The response from the mortgage and protection industry has been broadly positive, but several voices have been quick to argue that the regulator's collaborative approach must translate into something more substantive than awareness campaigns.
Beyond the awareness gap
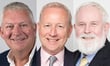
Andrew Gething (pictured top left), managing director of MorganAsh, welcomed the report's direction but argued the work of closing the protection gap goes further than getting more people to consider cover.
"The FCA's final report makes clear that closing the protection gap is not simply about getting more people to buy protection," he said. "It is about making sure people can recognise when protection is relevant to their circumstances, understand their options and access cover that meets their needs."
Gething drew particular attention to customers with characteristics of vulnerability, warning that the barriers identified by the FCA – complex sales processes, lengthy underwriting, unclear communications and limited availability – need to be addressed before the point of claim, not at it.
"The focus on prompts, clearer communications and improved access is welcome, but there is an opportunity to go further by making support more responsive to the individual," he said. "Protection needs can change as a customer's health, finances or circumstances change, and firms need to recognise those moments proactively and respond accordingly."
He pointed to vulnerability assessments as a more precise tool for identifying protection needs than traditional life-stage triggers such as marriage, children or mortgages. "With vulnerability assessments becoming increasingly embedded across financial services and utilities, there is a greater opportunity to engage on protection," he added. "The fundamental point is that information being available is not the same as a customer being able to understand it, act on it and access the protection they need."
Reaching beyond traditional triggers
Graham Singleton (pictured top right), chief executive of National Friendly, echoed the concern that protection conversations remain too narrowly defined, and highlighted the role of mutual societies and lower-cost products in reaching underserved segments of the population.
"Mutual societies and flexible, lower cost protection products represent an important part of the solution, helping reach many parts of the population that don't usually buy any cover," he said. "It's also great to see the FCA highlighting that protection triggers shouldn't be just limited to traditional life stage milestones."
Singleton pointed to generational differences in expectations around protection, noting that Gen Z and millennials are more likely than older consumers to expect advisers to discuss everyday accidents alongside serious illness and death. "Yet these generations are also least likely to have hit the traditional protection triggers such as buying a home or having children," he said – a dynamic that makes the FCA's broader framing of when and how protection conversations happen all the more pressing for advisers engaged in protection and mortgage advice for younger clients.
Networks have a role to play
Rob Clifford (pictured top middle), chief executive of Stonebridge, described the report as the most important regulatory review of the protection market in years, and one capable of benefiting industry and consumers in equal measure.
"The final report, reinforcing the FCA Interim Report, finds that competition in the industry works well," he said. "That said, not enough people are getting to the point they can benefit from that, because far too many consumers remain unprotected."
Clifford was unequivocal that the advice sector has been delivering good outcomes, and that the report contains no findings of consumer harm or misselling. The problem, he argued, is one of reach. "The industry, including insurers and distributors, has been reminded that the protection gap must be tackled to prevent unnecessary financial harm," he said. "We know that mortgage networks have a huge role to play and we'll continue to invest heavily in the soft skills and technology advisers need to close this gap."
He also highlighted a specific finding in the report relating to policies not being written into trust – a persistent issue that can result in payouts becoming entangled in probate. Stonebridge has been building adviser awareness of trust usage in protection for several years, and Clifford welcomed the FCA's decision to give it dedicated attention. The issue sits alongside the broader conversation about consumer financial resilience in the UK and reflects the kind of systemic gap the industry is increasingly expected to address.
The FCA has confirmed it will hold a webinar for firms to address misunderstandings about its rules that may be acting as barriers, and will work with the Association of British Insurers (ABI) to reduce delays in obtaining medical records. No new market-wide regulatory measures are planned, but the regulator has made clear it will take action where firms fall short of Consumer Duty requirements.
"The determination that shines through here represents a step change in improving the protection market, which promises to hold enormous power over the reduction of financial vulnerability among households," Clifford said. "While not suitable in all cases, trusts can rescue families from impossible financial situations when it matters most."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.