Ashlin Endter of 4MG Mortgage on equity access for investors, without income or a new first loan
Investors holding low-rate mortgages on rental properties have little reason to give them up, even when they see deals to buy.
However, there is a product that brokers can pitch to those investors to help them get new deals done without worrying about that low-rate first lien.
A debt service coverage ratio (DSCR) second lien leaves the first mortgage alone and qualifies the borrower on the property's rent and the borrower's credit, not on income.
One industry veteran said it is a niche product that many in the industry have yet to take up.
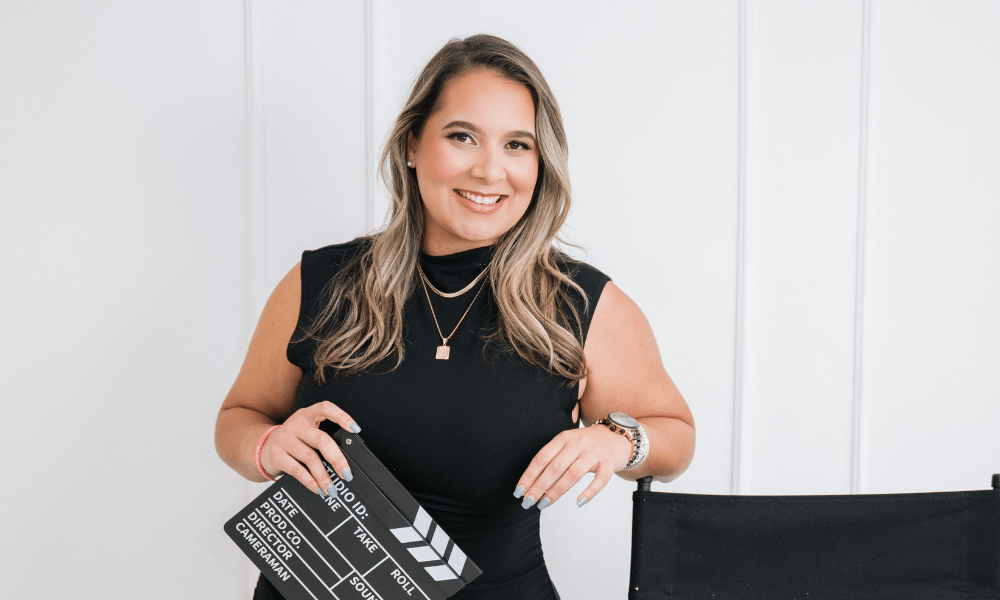
Ashlin Endter (pictured top), president of 4MG Mortgage LLC, said brokers who get the structure right can capture demand that is already there.
"Nobody's talking about the gold mine for investors or even for homeowners who want to turn their primaries into investment properties," Endter told Mortgage Professional America.
How it qualifies
Many investors have paid down their first loans and don't want to start a new 30-year term, Endter said. The second gives them another way to get at the equity.
"It's essentially a glorified Amex, and it allows you to pull equity without touching your first mortgage," Endter said.
Unlike a typical HELOC, the product does not look at the borrower's income. Endter said that is the part many investors don't know.
"I don't need you to be working," Endter said. "I don't need you to have a million-dollar job. I don't need you to be worried about your debt-to-income or the fact that you have 10 cars financed under your personal name. I just need to make sure that you have the qualifying credit and your house rents."
Endter gave an example of how the math would work. A rental that brings in $3,000 a month, with $2,000 going to principal, interest, taxes, insurance, and HOA dues on the first mortgage, can take on a $1,000 monthly payment on the second and still hit a 1-to-1 ratio. The new and old payments together can equal the rent, and no more.
"There are so many people who are actually sitting on so much equity, and there are properties that cash flow, whether it's short-term rental or long-term rental, and they can access their equity," Endter said.
Investors, she said, tend to ask a short list of questions that don’t involve the mortgage rate.
"Most investors don't care about the terms and rates," Endter said. "They're like, does it make sense? Can it get me money? Can I pay it back? And is there a prepayment penalty on it?"
What brokers should know
Investors are looking at a buyer's market in most areas, Endter said, and many are short on cash to act on it. They have been reluctant to touch the low-rate loans they already hold.
"The investors are not really interested in the doom and gloom," Endter said. "People find opportunity in down markets."
First American Data & Analytics put accessible equity at a record $13.2 trillion in the second quarter, and about 88% of it sits with borrowers whose mortgage rates are below the prevailing rate. Endter said many investors don't want to give up those rates.
Optimal Blue's September 2026 Market Advantage report, which draws on lock data from about 800 lenders, put non-QM at 12% of September production, up 478 basis points from a year earlier. Brennan O'Connell, director of data solutions at Optimal Blue, said the rise in non-QM comes from both borrowers and the people originating their loans.
"I think the originators are also going out there and they're like, 'Hey, are you an investor looking to do a debt service coverage ratio loan? Let's get a loan done,'" O'Connell said in October.
Many investment property loans carry prepayment penalties, which a second lien avoids triggering. That makes the terms on the second the part brokers need to get right, Endter said.
"You need to make sure you're structuring your investor into a good prepayment deal," Endter said. "What is your long-term plan?"
An investor planning to cash out within months may be better off with no prepayment penalty, she said, as long as the property still cash flows at the higher rate.
The product's growth carries its own risk, Endter said, as originators who don't usually do non-QM move in. She said borrowers should work with someone who knows these products well.
"Clients are getting to the closing table, and they're not understanding that they got locked into a three-year prepayment penalty, or they were so excited about their 6% interest rate and they didn't realize that the originator placed them on a five-year prepayment penalty at 5%," Endter said.
Brokers Advantage, FundLoans, and Angel Oak all offer the product, she said. Angel Oak also has a bank statement version, but she prefers the DSCR one because it skips debt-to-income.
The product is available in nearly 40 states, she said, which lets her serve investors beyond her local market.
"Now you can help your investors who have portfolios in multiple states, right?" Endter said. "Hey, you want to do the Ohio house? You want to do the New Hampshire house? You want to do this house? Cool. I got you. I can do all of them for you."
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.