Selma Hepp's base case could open a refi wave earlier than expected
In late 2025, most economists forecast a gradual decline in mortgage rates continuing throughout 2026. However, none of them could forecast the macroeconomic factors that would turn those projections upside down.
Now, 30-year mortgage rates are closer to 8% than they are to the sub-6% rate briefly experienced early in the year. Anytime rates begin moving higher, there is speculation about how high rates can go.
However, brokers want forecasts grounded in reality, not based on extreme cases that predict extremely high or low rates. One chief economist sees a base case for an eventual rate decline, although the market will have to work through the current challenges first.
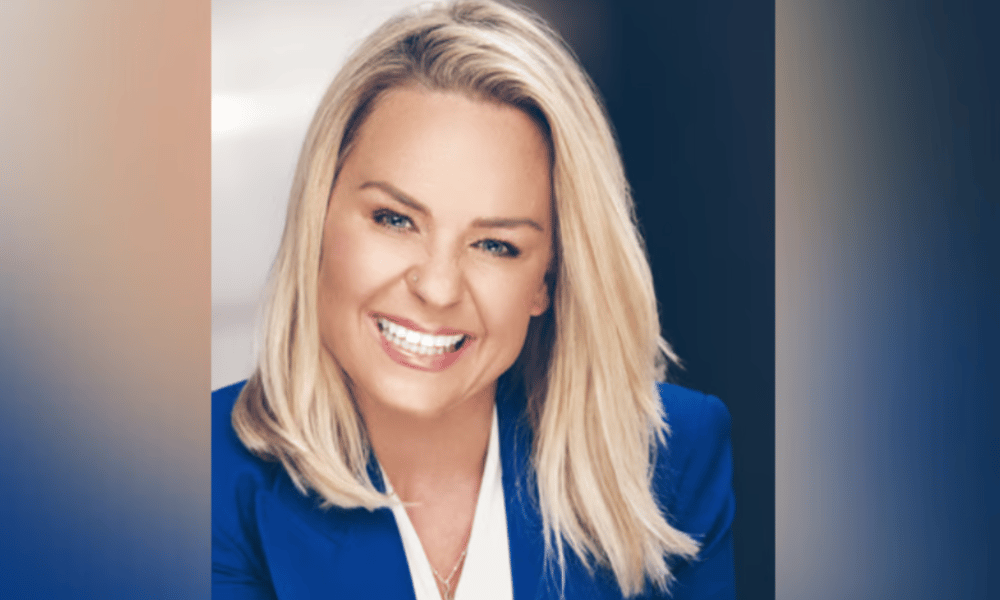
Selma Hepp (pictured top), chief economist at Cotality, said it has been a rough stretch for housing.
"I think, unfortunately, it feels like a one-two punch for the housing market," Hepp told Mortgage Professional America. "We had this very fleeting moment of relief in February, and then everything sort of changed from there."
Base case and refi pool
The Mortgage Bankers Association (MBA) reported Wednesday that the average contract rate on a 30-year fixed-rate conforming mortgage was 7.49%.
To fall from that rate, it will likely take geopolitical unrest easing, energy prices and inflation stabilizing, and bond yields coming off their highs.
"One scenario is inflation does come in, slowly, but month after month we see some improvement to give people enough confidence that inflation is coming in," she said. "In that case we sort of fall off that 7.5% where we are today and go to the upper 6s if we're talking about mortgage rates. I don't think the spread itself changes at this point. So we go to the 6s, and we move to the mid-to-high 4s for Treasuries. That's a base case scenario for me."
She also has a downside scenario, which she said is less likely. It depends on factors well outside housing.
"Or you have this worst scenario where inflation is persistently higher," she said. "The elections in some way don't lead to any resolution in terms of the supply shock, Middle East conflict, and all that. And then you have more infighting in government, and you get Treasuries going up. They're now at like 5.3%. I want to say they go up to 6%. This worst-case scenario is also lower probability."
In that case, she said, Treasury yields in the high 5s to 6% would keep mortgage rates between 7.5% and 8%.
However, if tensions in the Middle East ease and energy markets settle down, rates could ease back into the 6s.
"That brings rates into that 6.5% to 7% range," she said. "At this point, with where Treasuries are, 6.5% is the most reasonable expectation."
That range would matter to originators looking for refinance business among loans from the past few years. Hepp said July data showed even a rate drop below 7% could bring refinances, and a lower drop could mean more refis.
"With rates 7% and greater, we have 1.2 million originated since 2022," she said.
The real number is probably a little higher now, she said, though originations have been light lately. That number increases dramatically when looking at loans originated since 2022 at a rate of 6.5% or higher.
"We have 3.8 million loans that are 6.5% or higher," she said. "That margin between 6.5% and 7%, that's where we created a lot of loans. As soon as you drop a little less than 6.5%, you get 3.8 million loans. So a lot."
A hard market to forecast
Most economists are revising their rate forecasts higher. Hepp said the most recent outside forecast she had looked at came from the National Association of Home Builders (NAHB).
"Looking at just mortgage rate forecasts alone, everybody has revised them up," she said. "I think they sent it out, and they're like in 7% at the beginning of next year. I think they go only to 6.8% by the end of 2027. We're really looking at such tight margins right now in terms of changes."
Pending sales are down from a year ago, Hepp said, and forecasters have been cutting their sales outlooks. Coming up with forecasts isn’t easy for economists because there are so many unknown factors to weigh.
"It's extremely difficult because you really don't know," she said. "When you look at what happened since March of this year, it's an incredible amount of volatility. At one point, I remember nobody thought Treasuries were going to go to 5%. That was unthinkable. But not just the Treasury; you have the term premium, the price of uncertainty, being much wider because it's so hard to know at this point.
“You don't know from Sunday to Monday or even from Friday to Saturday. It seems like a lot of things happen on the weekends. It's very unfulfilling right now to be on the side of forecasting."
It’s also a challenging time for the Federal Reserve. CME FedWatch is predicting a rate hold in October, but believes there will be more hikes through the middle of 2027. Hepp said the central bank is working through the same uncertainty, which is why they’ve even backed off on forward guidance.
"I think maybe that's why they are holding back on forward guidance, because it's hard to give forward guidance right now when you don't know what the reading is going to be from one month to the next," she said. "When you look at the statement of economic projections, we are kind of where they think we're going to be. There are not that many hikes to be had if we are following that statement of projections. I think they are just as in this turmoil as everybody else."
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.