TransUnion's Satyan Merchant doesn't think 'anyone's ringing any alarm bells right now'
Mortgage delinquencies have crept back above their pre-pandemic level, after a pandemic stretch when loan forbearance helped many homeowners avoid delinquency.
Most of the movement traces back to loans insured by the Federal Housing Administration (FHA). Where the pre-pandemic picture was a broad mix of loan types, FHA loans now make up most seriously delinquent accounts, according to the latest data from TransUnion.
Despite the increase, one TransUnion executive isn’t too concerned yet. Home equity gives borrowers a strong reason to hold on to their homes, and a labor market that keeps beating expectations is helping them keep making payments.
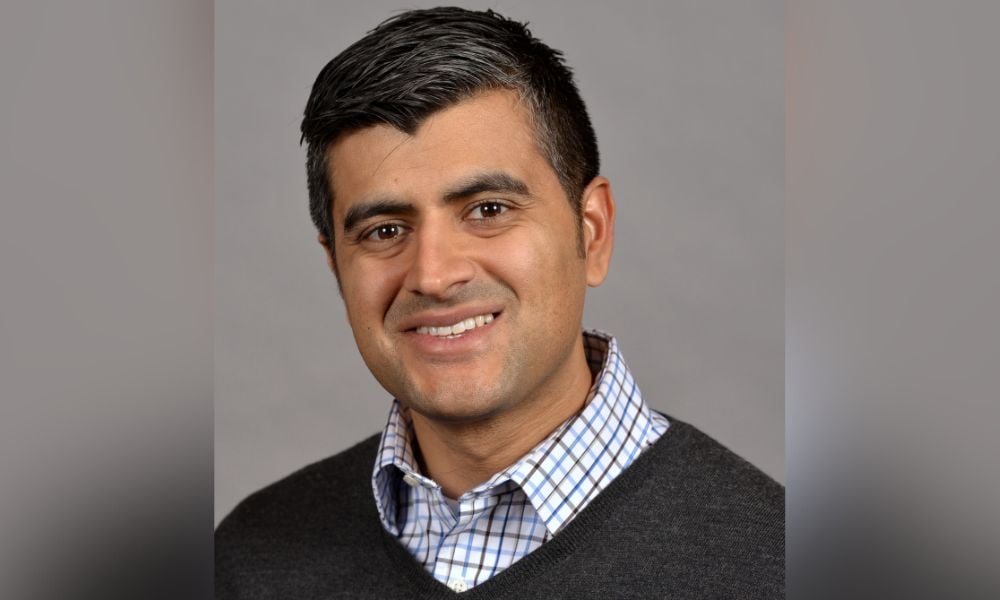
Satyan Merchant (pictured top), senior vice president and automotive and mortgage business leader at TransUnion, said the 60-day mortgage delinquency rate reached 1.71% in the company's Q3 2026 Credit Industry Insights Report (CIIR), which covers 54.7 million mortgage loans and $13.1 trillion in balances.
"Probably worth keeping an eye on," Merchant told Mortgage Professional America. "I don't think anyone's ringing any alarm bells right now."
FHA is the driver
TransUnion's report puts the account-level rate at 1.71%, up from 1.58% in 2019 and 1.42% a year earlier. Merchant said it hit a low of 0.8% in 2021.
"The trend is like a small kind of stair-step march upwards since 2021," Merchant said.
Today's rate is nowhere near the great financial crisis, when it topped 7%, and it was 1.70% in 2018, the report shows. The borrower-level rate is 1.64%, up from 1.36%.
Overall delinquency rates before the pandemic were in roughly the same ballpark, Merchant said, but the mix of loan types behind them was different.
"FHA is becoming more of the driver of delinquency versus maybe back pre-pandemic, it was a more even spread of the drivers, like the different loan types, Fannie, Freddie, Jumbo, et cetera," Merchant said. "It actually gives us more clarity on where to keep our eye on at the moment, which is FHA."
Nearly half of mortgages 60 days past due, 47.2%, are FHA loans, the highest concentration in more than 20 years. Their delinquency rate reached 5.60%, up from 4.09% a year earlier.
Performance on Fannie Mae, Freddie Mac and jumbo loans remained stable. The recent mortgage vintage is also performing well in its early months relative to loans originated from 2022 to 2024.
FHA's share of new originations has declined to 18.5%, though its share of balances keeps rising. FHA borrowers typically carry higher loan-to-value ratios and smaller down payments, he said.
"It's not surprising that's where some of this delinquency is coming from," Merchant said.
Why borrowers are holding on
The strain is not limited to mortgages, Merchant said, with delinquencies also ticking up among card and personal loan borrowers as below-prime borrowers take a growing share of new accounts. They made up 42.3% of new card accounts, up from 40.6% a year earlier.
"It's a signal that the consumer that's below prime is looking for credit, looking for access to liquidity," Merchant said.
Lenders have modeled for that risk, he said, so charge-offs have stayed managed. In his view, inflation has cooled but remains sticky, and wages have started to close the gap with prices.
The Bureau of Labor Statistics reported Friday that employers added 165,000 jobs in October, well above what economists expected, and that the unemployment rate slipped to 4.1%. Average hourly earnings rose 3.1% from a year earlier.
"Probably the most important macro figure in my world is employment, and employment continues to be strong," Merchant said.
Home loan delinquencies are often the last sign of trouble to show up, as borrowers are likely to exhaust all options before considering giving up their homes.
"When the consumer has real or even perceived wealth, which is often in the form of their home, they might be struggling, but they're not going to give back the keys to the house," Merchant said.
Cotality forecasted that home price growth will slow to 0.9% by September 2027, according to data released this week. Even slowed growth is better than falling values, which could change the thinking of homeowners who are falling behind.
“If you're struggling to make the payment and your house is losing value, it's like a much different decision, psychological and even logical decision a consumer would make," Merchant said.
Over time, he said, the housing finance system has worked.
"Sure, we had a crisis. Sure, there are periods of delinquency. But when you zoom out, it's an upward trending story in the United States, which is a really good one," Merchant said.
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.