Rates may be on the way up, but that’s only bringing the role of mortgage professionals into sharper focus
With Treasury yields continuing to climb higher and mortgage rates following suit, loan originators and their clients could be in for a bumpy fall homebuying season as the 30-year fixed average lurches above 7%.
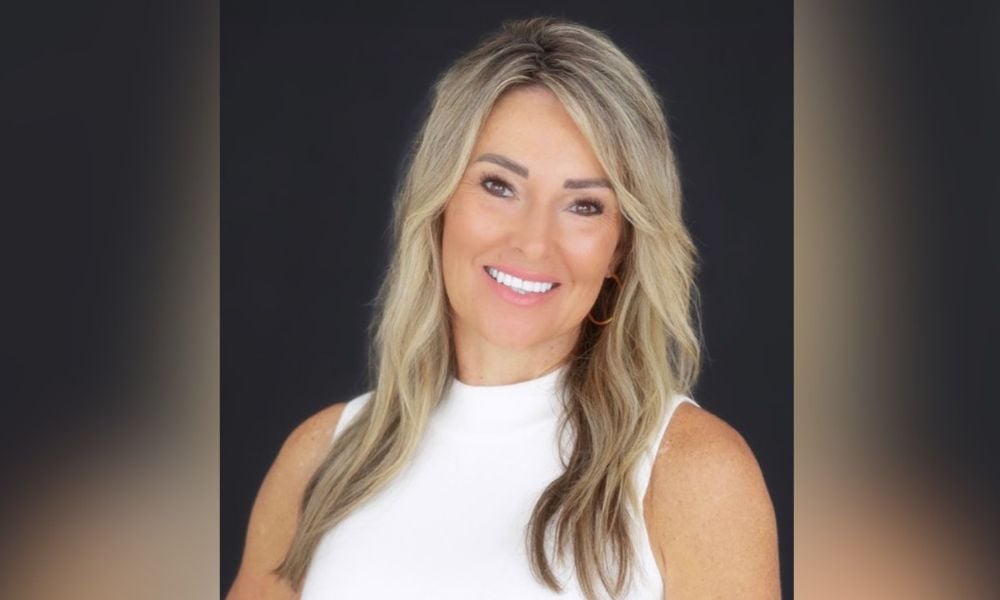
But while some homebuyers might step to the sidelines because of the continuing tumult – which hasn’t been helped by the ongoing conflict in Iran and the resulting upward pressure on bond yields – loan officer Jessica Eddy (pictured top) of Edge Home Finance told Mortgage Professional America she’s still emphasizing to her clients that purchasing is often the right move.
“I had a client say, ‘Oh, we’re just going to rent,’” she said. “And I said, ‘OK, well, let’s look at this here – before we make that decision, let’s look at the numbers.’ And they were like, ‘Oh, well, we’re still below where we thought we were going to be, so we’re good.’”
The buyer’s market case
Higher rates are clouding the picture for potential homebuyers whose budgets were already stretched, but those with a better financial picture are seeing some opportunity despite rising borrowing costs.
That’s partly because reduced demand has brought more inventory to market, ended the bidding wars that defined the low-rate period, and restored negotiating leverage that buyers had largely lost.
“This is definitely now becoming a buyer’s market,” Eddy said. “There’s more inventory now than there has been in quite a while. No bidding wars have allowed seller concessions. If you have a house to sell and it’s contingent on your purchase, now we’re able to make that back-to-back closing work because the seller’s willing to wait.”
And rate buydown strategies are becoming increasingly common in the current market, Eddy said. She sees a clear distinction between a temporary 1-0 buydown (funded through seller concessions, with any unused portion applied to principal if the buyer refinances within the first year) and a permanent buydown, where those funds are forfeited upon refinancing.
“No funds get lost on that versus if you do a permanent rate buydown from a seller through seller concessions. Then if you refinance, those funds are gone,” she said. “So there’s just different tools that we can use.”
The decision between the two comes down to timelines and market expectations. Eddy said she typically walks clients through a straightforward calculation: divide the total cost of the buydown by the monthly savings it generates to arrive at the breakeven point in months.
If that figure runs to 24 or 36 months or beyond, the math may not support it. Buyers who understand how to use rate buydowns and seller concessions effectively are better placed, she said, than those taking their cues from headlines about mortgage rates alone.
FHA loans back in focus
FHA loans, meanwhile, are a product worth revisiting, Eddy said – both for buyers and for the realtors she works alongside.
“I’m letting my realtors know: don’t be afraid of an FHA loan, because we were not seeing the rates in FHA going up as much as we were with the traditional conventional loans,” she said. “So those could be a better opportunity and a better option for buyers currently.”
The geopolitical uncertainty that’s gathered because of the Iran war and global trade disputes is responsible for a significant layer of complexity in the rate outlook. Oil market volatility, Eddy said, is compounding an already unsettled environment in ways that monetary policy alone cannot resolve.
“No matter what the decisions are with the Fed, until there’s a resolution with that, I don’t think we’re going to see any changes with the market as far as seeing rates come down,” she said.
Rate movement may be volatile at present and potentially about to get worse, but Eddy’s approach is centered around the idea that client education is the main variable that loan officers can control.
The current environment is also putting the value of loan originators and mortgage brokers into sharp focus. “Now is even more important to have someone in your corner to educate and to help walk you through that,” Eddy said.
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.