Nationwide, Barclays and Halifax have all reduced rates this week, with Rhys Edwards saying the moves signal genuine market confidence

Nationwide, Barclays and Halifax have all cut their mortgage rates this week ahead of the Bank of England base rate decision on Thursday, in a move that signals growing confidence in the direction of the market.
The base rate has been held at 3.75% since December 2025, but with UK inflation climbing to 3.5% in September – above forecast – financial markets are widely pricing in a rise on Thursday. Against that backdrop, this week's lender activity has caught the attention of brokers.
Nationwide has reduced its rate for those remortgaging with the largest deposits to 4.99%, down from 5.09%, while its five-year fix for home movers with a 40% deposit now sits at 4.89%, down from 5.01%. Barclays is offering a two-year fix at 4.95% for buyers with a 40% deposit, while Halifax has a comparable deal at 4.93% for members of its Loyalty Club. Sub-5% deals, however, remain largely out of reach for those with deposits below 40%.
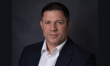
Rhys Edwards (pictured top), head of mortgages at Stratton Wealth Management, said the reductions are being driven by movements in the wholesale market, specifically swap rates, which have edged down in recent days partly due to a fall in the price of oil.
"The wholesale market has dipped a little bit," Edwards told Mortgage Introducer. "Swap rates are down. It's nice to see that being shown in some lower lender rates."
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
What the cuts really signal
While a base rate rise is widely expected on Thursday, Edwards offered a view of the relationship between the base rate and fixed mortgage pricing that may surprise borrowers who assume the two move in lockstep. A modest base rate increase, he argued, can actually create conditions for fixed rates to fall. By providing greater certainty about where inflation actually sits, a rise can give lenders the confidence to sharpen their pricing.
"We've seen this before where when the Bank of England base rate actually goes up a little bit, it benefits the fixed rates because it gives a bit more confidence of where pricing should be," Edwards said. "There's been such a large gap between tracking mortgages and fixed rates because of all this implied inflation coming into the market."
Further evidence arrived in real time during the conversation with Edwards. Accord Mortgages announced reductions across most of its product range, while NatWest had earlier today cut some of its existing customer rates. The pace and breadth of those moves suggested the market is reading Thursday's decision as a settling moment rather than a source of alarm.
"It doesn't look like the lenders are too worried about the potential increase affecting their margins the way they are reducing rates," Edwards said. "That's why I'm feeling it's given a bit more certainty to the lenders of where the market's going."
Broker priorities after the announcement
The period immediately following a Bank of England decision demands proactive client management. Edwards said the first priority is to be ready for a surge in contact, particularly from those on tracker mortgages, which are linked directly to the base rate and move with it almost immediately, unlike fixed rate products.
"It’s important to man the phones a little when the announcement hits, because people are going to be coming to us with questions on how it affects their situations," he said. "Especially those clients we've been speaking to recently on potential remortgages, refinancing, product transfers, and those out there house hunting."
The majority of clients, however, are likely to need reassurance rather than urgent action. Fixed rate customers are insulated from the immediate impact of a base rate move, and the message for many will be that the picture is not as alarming as headlines might suggest. As Mortgage Introducer’s preview of what the anticipated rate rise means for mortgages sets out, the relationship between base rate movements and fixed rate pricing is rarely straightforward.
"It's managing expectations of where most people sit," Edwards said.
The psychology of sub-5%
The psychological impact of the sub-5% threshold should not be underestimated, according to Edwards. He cited a client whose quoted monthly payment had moved from around £1,400 to just above £1,300 following the week's reductions, not a dramatic difference numerically, but one that immediately shifted the client's outlook.
"You see something priced at £3.99 and you automatically think it's still within the £3, not that it's just one penny less than £4," Edwards said. "It has a positive effect when you're speaking to clients."
Edwards also noted a broader shift in borrower behaviour. Clients who might previously have sought to maximise their borrowing are now arriving at meetings having already factored in budget headroom unprompted – a sign, he said, that the higher rate environment has driven a meaningful improvement in financial awareness.
"Some clients are coming back saying, 'we don't want to max out – we want to leave some room in our budget,'" Edwards said. "I'm thinking, great, because we just don't know where rates are going to end up."
Looking ahead, Edwards said the market needs stability. Continued falls in the oil price could feed through into further swap rate reductions, giving lenders more room to move on fixed rate products – though geopolitical developments could quickly reverse that momentum.
"As it looks today, I would like to think there'd be some more reductions if things continue as they are," he said. "A couple more dips on that rate can't do anything but help."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.