Reducing mortgage broking to a glorified price comparison tool does the profession a disservice, argue Australia’s leading mortgage professionals

The cheapest home loan on the market can look like a bargain, much like the cheapest umbrella does before it meets its first southerly.
This week, the corporate regulator put that trade-off under the microscope, telling mortgage brokers that when they recommend anything other than the lowest-cost loan, they’ll need to be able to show their working.
Brokers speaking to MPA spoke to don’t dispute the principle. But they do want borrowers to understand why the lowest rate and the best outcome are often two very different things.
ASIC’s Report 840, titled ‘Mortgage brokers: Review of best interests duty and complaints handling practices’, is the regulator’s first major test of the best interests duty (BID) since the obligation began in January 2021. The review examined 13 credit licensees across eight large aggregator groups.
The headline number: seven of the eight aggregators reported that their brokers did not recommend the cheapest loan in more than 20% of cases, and the Australia Securities and Investments Commission (ASIC) found instances where brokers had no clear evidence to support those recommendations.
Make no mistake: the report did not paint the broking industry in a particularly negative light. On the contrary, the licensees reviewed generally had processes designed to support compliance, and ASIC observed no apparent steering towards lenders paying higher commissions.
But ASIC commissioner Alan Kirkland warned that inadequate reasoning will leave brokers open to regulatory scrutiny. And the bigger the cost gap between a recommended loan and a cheaper alternative, the stronger the evidence a broker needs.
Industry bodies were largely welcoming of the ASIC report, but there is a sense among the broking community that the regulator is out of step with what a borrower actually needs out of a home loan.
What does BID actually require?
BID requires brokers to act in a borrower’s best interests when recommending a home loan. True, cost sits at the heart of it.
Under ASIC’s Regulatory Guide 273 (RG 273), recommending a loan is unlikely to be in a borrower’s best interests if a cheaper one would also meet their non-cost needs. But RG 273 also recognises that features like offset accounts, approval speed and a lender’s credit policy can legitimately matter.
In other words, brokers are allowed to recommend a pricier loan, provided they can prove why. So what justifies paying a bit more? The brokers MPA spoke to had plenty of answers.
When the cheapest loan can’t get you the keys
The first reason is the simplest: the cheapest loan isn’t much use if the borrower can’t get it, or can’t borrow enough with it.
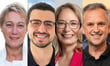
Tanya Sale (pictured, top of page, left), chief executive of mortgage aggregator outsource Financial, said the rate is only one part of the equation. “The lowest rate does not always equate to the best outcome for a client. Factors such as credit policy, borrowing requirements, flexibility and future needs can all influence the most appropriate recommendation,” she said.
Curtis Stewart (pictured, right), head of strategy at Flint, offered a scenario most brokers will recognise: “We don’t always recommend the cheapest loan, and our clients would be worse off if we did. Rates and fees matter, but every customer comes to us with a different goal.
“For a buyer stretching to get a home in the suburb they want, a lender with a more generous servicing calculator and a slightly higher rate might be the best way to get there. The cheapest loan is no good if it doesn’t meet your objectives.”
Who the borrower is can matter as much as what they want. Joseph Daoud (pictured, top of page, centre left), founder of Its Simple Finance, said his business recommends the cheapest loan wherever possible, but employment type quickly changes the shortlist. Some lenders suit self-employed borrowers best, while others suit teachers, and non-bank lenders can offer higher borrowing capacity than traditional lenders.
Justine Harris (pictured, top of page, centre right), mortgage broker at Nectar Mortgages, made a similar point about income. She said a lender’s credit policy, its assessment of variable income and the borrowing capacity it offers can be “critical to achieving the outcome they need”.
Why speed to approval matters
Then there’s the clock. A rate comparison won’t show what a delayed approval costs, either, and AFG chief executive David Bailey said that cost can be steep.
“When an approval is time-critical, such as a purchase with a fixed settlement date, the cost of a delay can be significant and won’t show up in a rate comparison. Missing settlement can mean penalty interest, extra costs and, in the worst cases, losing the property and the deposit,” he said.
Daoud put numbers on it. A bank might be 10 basis points cheaper, but take three extra weeks to approve the loan. For a buyer with a fixed settlement date, that can be the difference between moving in and losing the property.
How offset accounts can beat a lower rate
The most popular example among the brokers was the offset account. An offset account is a transaction account linked to a home loan, and its balance reduces the amount of loan interest charged.
An offset account will often save them far more than a marginally lower rate on a basic loan,” Stewart said.
Energy Lend director Darren Sayers (pictured, top of page, right) took the idea further, pointing to the behavioural benefits of having more than one offset.
“We often use our calculators to demonstrate how structuring a loan with multiple offsets can help customers establish and sustain good savings habits, particularly where they’re allocating funds towards different expenses or savings goals,” he said. “Over the life of a loan, those behaviours can potentially deliver interest savings that far outweigh a relatively small difference in interest rates.”
Beyond the one-and-done deal
A home loan is a generational financial commitment, so a good recommendation naturally looks well beyond the borrower’s circumstances today.
Blake Buchanan (pictured, below), general manager at SFG, gave a familiar scenario: a couple planning to have a child, with a stretch of parental leave and lower household income ahead. “The cheapest loan may only offer principal and interest repayments, while a slightly more expensive alternative may provide an interest-only option, subject to lender approval and assessment at the time.”
He was careful to flag the trade-off. “That flexibility could help reduce repayments temporarily, although the broker must explain the additional interest costs and higher repayments that may follow. The question is whether the benefit justifies the additional cost for those particular clients.”
That is the same calculation ASIC wants brokers to put on paper: what the extra cost buys, and whether it’s worth it. And for Harris, the answer shifts depending on who is sitting across the desk.
“For a first-home buyer, eligibility for a government scheme, the lender’s assessment criteria and confidence in meeting contractual settlement deadlines may be particularly important. For an investor, loan structure, interest-only options, equity access and flexibility for future purchases can significantly influence the recommendation,” she said.
Why brokers need to show their working
None of this works without documentation, and that is exactly where ASIC found gaps.
Sale agreed that brokers must be able to show why a particular loan was recommended. “Where a lower cost option was not selected, ASIC expects that rationale to be clearly documented.”
Bailey accepted ASIC’s finding that some higher-cost recommendations across the industry needed clearer documentation. “Where a broker recommends a loan that isn’t the cheapest, the reasons should be clear, documented and explained to the customer, and the bigger the price difference, the stronger that explanation needs to be. AFG will keep working with our brokers, and with ASIC, to make sure that happens consistently.”
Loan Market Group (LMG) made the same point in a statement to its brokers, stating that BID does not require recommending the cheapest loan every time, but a higher-cost recommendation demands stronger evidence.
For Sayers, the test is simple. “Ultimately, it’s not about recommending a more expensive loan for the sake of additional features. It’s about understanding how the customer is likely to use the loan and demonstrating why the recommended product provides the best overall outcome for their particular circumstances.”
Stewart framed it as a question of respect for borrowers. “Price absolutely matters. But the best interests duty isn’t about picking the lowest number. It’s about recommending the loan that best serves the customer’s goals and being able to explain why.”
Harris welcomed ASIC’s push for higher standards, but warned against reducing broking to a price comparison. She summed up the whole debate in one sentence: “The cheapest loan isn’t always the best loan, but the best loan should always be one that a broker can clearly explain and justify.”
A cheap umbrella is easy to sell, but when the southerly hits, regret is often the hidden cost. A home loan is no different.