Corporate regulator’s review into mortgage broking industry should be welcomed, says FBAA boss Leo Gagic

The Finance Brokers Association of Australia (FBAA) has welcomed the Australian Securities and Investments Commission's (ASIC) review of mortgage brokers' best interests duty (BID), saying it shows brokers must weigh competitive pricing against each borrower's circumstances – not simply default to the cheapest loan.
ASIC's Report 840, Mortgage brokers: Review of best interests duty and complaints handling practices examined 13 credit licensees across eight large aggregator groups. Seven of those groups reported that their brokers did not recommend the cheapest loan in more than 20% of cases, and ASIC found instances where brokers had no clear evidence to support those recommendations.
ASIC is calling on brokers to consider the findings in the report and take steps to address gaps in their practices.
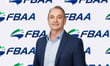
"Competitive pricing matters, and brokers will always consider it. But every customer has different circumstances, and a broker's value comes from understanding those needs and helping them find an appropriate loan," FBAA chief executive Leo Gagic (pictured) said.
"In its report, ASIC recognises that factors beyond cost can be relevant to a recommendation. That is an important acknowledgement of the judgement and customer understanding brokers bring to their work."
Gagic pointed to self-employed borrowers as an example. Low-doc loans are designed for borrowers who cannot provide standard income evidence such as payslips, and typically carry higher interest rates than full documentation loans.
"For example, a self-employed customer may need a low doc loan because of the income documentation they can provide. It may not be the cheapest option, but it can enable them to secure a loan suited to their circumstances," he said.
"Brokers help customers understand their options and weigh up the trade-offs. Clear explanations and strong documentation demonstrate the reasoning behind a recommendation, including why any additional cost is justified."
That emphasis on the paper trail mirrors ASIC's own guidance. Regulatory Guide 273 (RG 273) states that any higher-cost recommendation must be supported by evidence showing why it is in the borrower's best interests – a point ASIC reinforced this week.
Gagic also welcomed the finding that brokers did not appear to favour lenders paying higher commissions. "That is a positive finding for our profession and deserves recognition," he said.
He added that the review should prompt brokers to treat compliance as part of how they run their businesses, rather than a separate task.
"As I've said before, compliance cannot be viewed as a standalone function or a simple box-ticking exercise. Growth, risk, compliance, governance, and customer outcomes need to be considered together and embedded in how a business operates.
"This is about building trust, professionalism, and long-term sustainability, alongside meeting regulatory obligations.
"The FBAA remains committed to supporting members through education, professional development, advocacy and practical business support, helping brokers build sustainable businesses and deliver good outcomes for their customers."
How did the MFAA respond?
The FBAA's response closely tracks that of the Mortgage & Finance Association of Australia (MFAA), which described Report 840 as a roadmap for the industry.
The MFAA noted ASIC found the licensees reviewed generally had processes designed to support compliance with the duty, largely aligned with ASIC guidance, and observed no apparent steering towards lenders paying higher commissions.
"ASIC's review gives our industry a roadmap. It recognises the foundations already in place, while being clear about where brokers, aggregators and licensees can continue to strengthen practices and consumer outcomes," MFAA chief executive Anja Pannek said.
Like Gagic, Pannek argued that price is central but not decisive on its own.
"Price absolutely matters. Consumers should have confidence that their broker has considered the available options and can clearly explain why a particular loan is in their best interests," she said. "At the same time, the lowest-cost loan is not necessarily the right loan for every borrower."