‘The challenge is not whether lenders offer incentives, but how they do so,’ says broker association boss

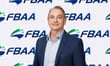
Finance Brokers Association of Australia (FBAA) chief executive Leo Gagic (pictured) has warned of channel conflict in the mortgage industry amid a glut of lucrative cashback offers hitting the market.
While Gagic, who recently took the helm of the broker association, reckons lenders have good reason to compete hard with a broker channel that now captures nearly 82% of new deal flow, he stresses the importance of fairness.
“The mortgage market is highly competitive and, with application volumes under pressure, it is understandable that lenders are looking for ways to attract customers and grow market share. Cashback offers and other incentives have once again become a prominent feature of the lending landscape, providing borrowers with tangible benefits and encouraging engagement in a challenging environment,” Gagic says.
“Lenders are absolutely entitled to offer cashback incentives and compete aggressively for business within the required legal and regulatory guardrails.”
The concern, he said, lies in how those offers are distributed.
“The challenge is not whether lenders offer incentives, but how they do so. When offers are only available through selected origination channels, or one channel receives a materially different proposition, the potential for channel conflict increases. Brokers continue to play a critical role in helping consumers navigate increasingly complex lending decisions and originate a significant share of Australia’s mortgage market.”
Changing the channel
Some of the most generous home loan incentives on the market are only available to borrowers who go direct, with several lenders limiting their best offers to their own online or branch channels.
One of the largest direct-only cash offers sits with the Newcastle Greater Mutual (NGM) Group. Newcastle Permanent’s cashback is available only for applications submitted through its online channel, paying $2,500 for loans of $250,000 to $499,999 and $3,000 for loans of $500,000 or more.
BOQ’s $2,000 refinance cashback applies only to applications received through a BOQ branch, requires at least $400,000 in new lending with a maximum 80% LVR, and excludes refinances from within the BOQ Group, including subsidiaries ME Bank and Virgin Money Australia.
On the points side of things, Commonwealth Bank is offering 100,000 CommBank Yello points to borrowers who apply online and settle a qualifying home loan of $100,000 or more, provided the application stays in its digital channel and settles within 90 days of formal approval. Borrowers must also hold Yello Gold or Diamond status when eligibility is checked, 60 days after settlement.
But some of the best cashback offers are also channel agnostic.
The biggest headline cash offer found was IMB Bank’s $4,000. IMB’s published terms pay $4,000 on eligible loans of $750,000 or more and do not restrict the offer to direct applications. Borrowers must, however, repay half the cashback if the loan is closed within 12 months.
ANZ offers $3,000 for eligible first-home buyers with an ANZ home loan of $250,000 or more; its broker page promotes the same $3,000 offer to brokers’ customers, with the same eligibility wording.
ME Bank’s $3,000 refinance cashback is paid when borrowers refinance from another lender, borrow $700,000 or more and have an LVR of 80% or less, and is being actively sold through the broker channel.
Preserving relationships
The FBAA believes incentive programs are most effective when they are transparent, accessible and support consumer choice regardless of how a borrower chooses to engage with a lender.
Gagic says: “While a promotional campaign may deliver a short-term uplift in volumes, lenders should also consider the longer-term value of maintaining equitable relationships across all distribution channels.
“Australia's lending ecosystem works best when lenders, brokers, aggregators, and direct channels operate within a framework of mutual respect and healthy competition. Growth and market share are important objectives, but fairness and consistency remain equally important.
“By ensuring incentive programs are accessible across channels, lenders can compete effectively while preserving the partnerships that support a strong, competitive, and consumer-focused mortgage market.”
A perennial issue
Channel conflict is far from a new fault line for the industry. In an opinion piece published in MPA in November 2025, Mortgage & Finance Association of Australia (MFAA) chief executive Anja Pannek said it was “disappointing to again hear of channel conflict rearing its ugly head” after major bank chief executives flagged a renewed push into lending through their own branches and digital channels.
She pointed to member reports of discounted branch pricing offered off the books, and of broker-submitted applications declined only to be approved in-branch, which she said raised concerns about lender bias in credit assessment.
Pannek argued that letting the conflict persist erodes trust between lenders and brokers, wastes effort and destroys lender margin – particularly when price undercutting and cashbacks come into play – while often leaving customers with a poor experience.
With brokers now settling more than eight in 10 new home loans, and major banks continuing to close branches as brokers fill the gap, how lenders split their incentives between channels looks set to remain a flashpoint.