A California mortgage veteran of nearly 40 years says rate lock-in has become a trap — and brokers can break it

For millions of Americans, a sub-4% mortgage has become a financial anchor. With the 30-year fixed rate averaging 7.4% as of mid-October, rate lock-in has kept sellers off the market and inventory tight, deepening the supply shortage even as housing needs evolve.
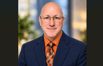
Michael A. Harris (pictured top), president and CEO of United Mortgage Corporation of America in Santa Clarita, California, sees a deeper problem in how that trade-off is being framed.
“The challenge is that the decision is often being made based on the interest rate alone, rather than the homeowner’s complete financial picture,” Harris, who has spent nearly four decades in the mortgage industry, told Mortgage Professional America.
Joel Kan of the Mortgage Bankers Association says new home purchase applications fell to their lowest level in six years as rising borrowing costs weighed on buyers, particularly first-time purchasers relying on FHA financing. https://t.co/Pf7V8lz8zm
— Mortgage Professional America Magazine (@MPAMagazineUS) October 15, 2026
Looking beyond the rate
Harris’s argument is not that rate lock-in is illusory — it is that the industry has elevated it into a reflexive rule that stops homeowners from examining what a move might mean for their retirement, their equity position, or their long-term financial goals.
“I believe the important question is not simply whether a homeowner should give up a 3% mortgage,” he said.
“It is whether the next housing decision makes sense when we evaluate the total cost, available equity, monthly cash flow, and long-term objectives. For some borrowers, staying put is absolutely the right decision. For others, moving may be the better choice despite the higher rate. The answer depends on their circumstances, not a blanket rule that everyone should hold onto their existing mortgage.”
His approach begins before any product recommendation. After reviewing a client’s equity, retirement exposure, and debt obligations, Harris determines whether a transaction is warranted and which structure fits best — a home equity line of credit, a fixed-rate second mortgage, a bridge loan, or reverse mortgage programs for eligible homeowners.
Each can unlock liquidity while preserving existing financing. Non-QM options for self-employed borrowers and real-estate investors widen the toolkit further for brokers who engage at that level.
Rethinking the broker’s planning role
Pending home sales fell to their lowest level in records dating back to 2021 in the four weeks ending October 18, per Redfin. US housing affordability is forecast to improve only modestly through 2026, raising the value of a deeper advisory conversation over rate-only guidance.
“My philosophy is straightforward: educate first, evaluate the alternatives, and then make an informed decision. The objective is not to put someone into a new loan simply because a product is available,” Harris said.
“At the end of the day, the mortgage should serve the homeowner’s financial plan, not dictate it. We need to move beyond rate-only conversations and focus on affordability, financial flexibility, responsible access to equity, and helping people make housing decisions that support their lives over the long term.”
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.