A Manchester-based adviser explains why the north’s high-value mortgage market is eating into London’s dominance

A record number of buyers in the north of England are taking out mortgages of at least £500,000, and one adviser says the shift is about more than just rising house prices.
Figures from estate agency Savills, reported by The Times, show that 3,875 buyers in the north of England borrowed at least £500,000 in the year to October, a rise of 16% compared with 2021. The midlands saw a 17% increase over the same period, with Wales, Scotland and Northern Ireland recording an even sharper rise of 27%. In London and the South East, however, the picture was reversed, as the number of buyers taking out £500,000-plus mortgages actually declined by 2%.
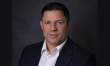
The data, drawn from Financial Conduct Authority (FCA) records, points to a growing concentration of high-value lending activity outside London and the South East – a trend that Rhys Edwards (pictured top), head of mortgages at Stratton Wealth Management in Manchester, says he is seeing play out directly with clients. Edwards spoke exclusively to Mortgage Introducer about what is driving the shift.
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
What is driving the rise in large northern mortgages?
Edwards points to a fundamental shift in where buyers are willing to live – and why. He recently assisted a client who had been living in a one-bedroom flat in central London and chose to relocate to Bramhall, a suburban area in Stockport, purchasing a five-bedroom detached home with a large garden for less than the price of their previous property.
"They're still working in London," Edwards said. "But because of hybrid working, they only need to come into the office once every two weeks, and with better rail links, Manchester is only a couple of hours from Euston."
That combination of improved connectivity and flexible working arrangements has, in his view, enabled a new category of buyer to access properties in the north that would previously have been out of reach, or simply off the radar.
House prices and loosened affordability rules
The rise in large northern mortgages reflects two parallel forces. Sustained house price growth in the region and a gradual loosening of affordability criteria by lenders. According to the Office for National Statistics (ONS), house prices in the north of England rose 18.5% over the five years to 2026, outpacing growth in London, which recorded just 3% over the same period.
At the lender level, the landscape has also shifted. The Bank of England scrapped its mortgage affordability stress test in 2022, and in 2025 the FCA relaxed its guidance around loan-to-income limits, allowing high street lenders to extend borrowing of up to six or seven times a borrower's salary in certain circumstances, up from the previous cap of 4.5 times.
Edwards sees this reflected in his caseload, particularly among borrowers with complex income structures. Contractors and project managers paid on day rates are now being assessed more favourably by a growing number of lenders.
"There are some front runners that have always done it, but more lenders are now starting to look at how they calculate income, using a day-rate calculation rather than relying on declared self-employed income through a limited company," he said. "That certainly does enable greater affordability."
He also notes that the geographic spread of high-earning industries has played a role. Businesses expanding outside London mean that higher earners are no longer tied to the capital, broadening the pool of buyers who can realistically target premium northern properties.
A tale of two markets
The contrast between Edwards's London and northern client bases is stark. In the north, conversations tend to focus on value – what buyers can get for their money, and whether hybrid working makes a commutable location viable. In London, the dynamic is fundamentally different.
"For many first-time buyers in London, a standard flat or apartment can range from £350,000 to £500,000," he said. "A lot of the conversations I have with London clients are centred around affordability, their current situation versus their deposit, and what they can actually get for that."
Buyers priced out of their preferred areas often face a limited set of options. Purchasing further out and commuting, exploring shared ownership, or pursuing more unconventional routes – friends buying together, parents acting as joint borrowers, or relying on substantial support from the Bank of Mum and Dad. Edwards notes that the size of parental contributions tends to be notably higher among London-based first-time buyers than those in the north, even if the proportion receiving such help is broadly similar across regions.
Stamp duty adds another layer of pressure in the capital, and Edwards has seen clients actively limit what they are willing to borrow in order to stay below first-time buyer thresholds.
"Just because a bank says they can borrow a certain amount doesn't mean they should," he said. "We need to take into account lifestyle, and what they like to do. It's not just about putting a roof above your head that you can't then do anything else with."
Outlook: steady shift, not a mass exodus
Edwards expects the trend towards larger northern mortgages to continue, driven by an attitude shift among buyers rather than any sudden structural change. He is seeing more clients consider locations further from London than they might have done before the pandemic normalised flexible working arrangements.
He is cautious, however, about overstating the trajectory. The return-to-office push from some employers could slow the outflow from London, and he does not anticipate a wholesale migration from the capital.
"I think it will continue, but there may be some pullback to the city as things change," he said. "Not all businesses agree on hybrid working. But for those that do offer that flexibility, it's a great thing, and it's certainly benefiting the North West."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.