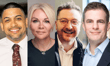
Brokers share their verdicts as the Bank of England raises the base rate for the first time in over three years

The Bank of England raised its base rate by 25 basis points to 4% on Thursday, voting 8–1 to lift borrowing costs for the first time in more than three years and signalling that further increases may follow.
The decision ended a run of six consecutive holds dating back to December 2025 and, while widely expected, the tone of the minutes – and the unanimity of the vote – left little doubt that the Monetary Policy Committee (MPC) is not done yet.
Mortgage professionals across the industry moved quickly to offer perspective, urging borrowers to stay calm and focus on their own circumstances rather than the headlines.
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
Expected, but the message is clear
David Hollingworth (pictured top right), associate director at L&C Mortgages, said the unanimous vote was the detail that caught his attention.
"I think it would have been more of a surprise if they'd decided to hold rather than increase," he told Mortgage Introducer. "What was perhaps a little bit more surprising was the fact that the vote was unanimous. There was a possibility that not everyone would have been voting for a rise, and of course one of the telling things was that one member is voting for a bigger increase of 0.5%."
Harry Arnold (pictured top middle right), director at Anderson Harris, agreed the outcome was never seriously in doubt. "It's pretty unsurprising that it's gone up to 4%," he said. "I think the market has very much priced that in. If the Bank of England had pulled a rabbit out of the hat and not raised rates today, then I think the market reaction would have been quite odd."
The sole dissenter was Catherine Mann, who argued for a more aggressive 50 basis point rise, citing non-linear inflation risks and the damage already done to the Bank's credibility after five years of above-target inflation. Several of those who backed the smaller move made clear they expect to be back at the table soon. Huw Pill, the Bank's chief economist, said a single hike "is unlikely to be sufficient" and that more tightening would be needed in the near term.
Base rate and mortgage rates are not the same thing
A consistent message from brokers in the aftermath was that borrowers on fixed rates should not assume today's decision feeds directly into their mortgage costs.
Hollingworth pointed to the lender rate cuts seen earlier in the week as the clearest illustration of how the two move independently. "All that does is underline the fact that just because base rates move doesn't necessarily mean that all mortgage rates are going to move," he said. "Fixed rates aren't and have not been linked to what base rate is actually doing. It's all about what base rate might do, and that's why they've been so volatile over the course of this year."
Arnold echoed that view, noting that swap rates – which drive fixed-rate pricing – were sitting at around 4.5% at the time of the decision, already pricing in roughly three further hikes. "Fixed rate pricing is unlikely to be moved dramatically by this," he said. "We've seen a few cuts on the fixed rate market in the last few days, gentle cuts from a few of the major banks. So I don't expect today's base rate announcement to move the dial too much on fixed rate pricing."
Nicholas Mendes (pictured top left), mortgage technical manager and head of marketing at John Charcol, noted that the impact would be felt most immediately by those on tracker and standard variable rate products. A homeowner with a £200,000 tracker mortgage over 25 years would see monthly repayments rise by around £28, he said, with standard variable rates likely to follow in the coming days.
Brokers urged to cut through the noise
With borrowers increasingly anxious, the industry’s message was consistent. Calm, clear advice matters more now than at any point in recent years.
"I think it's about stepping away from all the hullabaloo in the press, which is all talking about what may happen," Hollingworth said. "The reality is that we don't know. Borrowers need to understand that this was very much expected, so this is not coming as an additional surprise, and it doesn't necessarily mean that fixed rates are going to leap once again."
Arnold recommended what he described as a safety-first approach. "Customers, all they can really do is try and get rates booked as early as possible and make sure their advisers are monitoring the market if things do improve at any point over that period of time," he said.
Mendes set out a practical framework for clients reviewing their options. Those with fixed rates ending within six months can usually secure a new deal now, he noted, with many lenders allowing a switch to a cheaper product if pricing improves before completion. Trackers can be cheaper than fixed rates and often come without early repayment charges, but Mendes was clear they suit borrowers with room in their budget to absorb higher payments, not those hoping rates are bound to fall.
What comes next
Jeni Browne (pictured top middle left), sales and marketing director at Mortgage Finance Brokers, was the most direct on the question of where rates are heading. "The increase today will come as little surprise to any of us," she said. "What is on my mind is how many more increases we are likely to see and when. Personally, I think we will see two more by the middle of 2027, but let's hope I am wrong."
Arnold pointed to the conflict in the Middle East as the single biggest variable hanging over the market. "A lot of it is contingent on what happens in the Gulf," he said. "If there is an agreed settlement in the Gulf within the next few weeks or months, then maybe we don't see that many more increases. Even the chief economist of the Bank of England doesn't think the market is right on the number of hikes being priced in."
Hollingworth shared that cautious optimism, noting that falling oil prices had already given some lenders the confidence to trim fixed rates, but warned against reading too much into it. "If resolution is reached, then market prices can come down quite quickly," he said. "But it's way too early to be expecting it."
Mendes struck a similarly measured tone, arguing that current market pricing looks too aggressive given the underlying data. "Much of the rise in inflation is being driven by energy, and with pay growth slowing and the jobs market softer, there is little sign yet of the broader inflation that would justify a long series of increases," he said. "That would give borrowers more reason for optimism as 2027 progresses."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.