Peak broking bodies say accountability must rest on evidence as brokers thrust into mortgage fraud spotlight once again

Australia’s two peak mortgage broking associations have rejected suggestions that mortgage fraud is a broker problem and have put forward their own fixes for an issue that has gripped the mortgage finance world in 2026.
The Mortgage and Finance Association of Australia (MFAA) and the Finance Brokers Association of Australia (FBAA) both say accountability for suspect home loans must rest on evidence of individual conduct, not on the channel an application came through.
Their comments come in response to evidence given by bank chief executives to the House of Representatives standing committee on economics in Canberra this week.
What the bank chiefs told parliament
ANZ chief executive Nuno Matos set the tone when he told the committee that “it’s fair to say that the majority of fraud was coming from broker channels, which means that we also have to do a better job in protecting good information in that channel”.
Westpac chief executive Anthony Miller told the same committee that “the idea that someone misrepresents so that they can get a loan or a larger loan has been a challenge for the banks forever, and it is a bit more sophisticated now with the brokers”.
Striking a more diplomatic tone, Commonwealth Bank chief executive Matt Comyn avoided placing blame on any particular channel, telling the committee that suspicious activity can take different forms across lenders as technology evolves rapidly.
The MFAA said it was "disappointed" in some of the statements made about the broker channel during the hearings.
MFAA: the channel is not the culprit
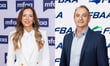
MFAA chief executive Anja Pannek (pictured, left) said the debate needs to separate how a loan is originated from how the people involved behave.
“A loan being submitted through a mortgage broker is not, in itself, evidence that the broker committed or knowingly facilitated fraud,” Pannek said. “These are serious matters, and any allegations of wrongdoing must be supported by evidence of individual conduct, rather than assumptions about how a loan was originated.”
Pannek stressed brokers and aggregators have obligations to spot warning signs. Lenders, she added, remain accountable for verification and credit decisions, and that includes their own introducer and referrer networks.
“Banks ultimately make the decision to approve a loan, and their responsibilities for verifying information and maintaining effective fraud detection controls remain important regardless of how an application is submitted,” she said.
FBAA: don’t confuse channel size with channel risk
FBAA chief executive Leo Gagic (pictured, right) made a statistical argument. Absolute fraud numbers, he noted, mean little without knowing how much lending each channel handles.
“The real question is not simply how many suspected fraudulent applications came through the broker channel, but what proportion of applications within each channel actually involve fraud?” Gagic said. “Without that intelligence, we risk confusing channel size with channel risk.”
He added: “Fraud has no place in our industry, and anyone deliberately participating in fraudulent activity should face the full consequences, whether they’re a broker, customer, banker or another participant in the lending process.”
How the industry wants to tackle mortgage fraud
Both associations have put forward concrete measures to tackle the fraud issue.
The MFAA took its proposals to the Australian Securities and Investments Commission (ASIC) mortgage fraud roundtable on 16 November 2026. They include:
-
better information sharing between lenders, aggregators and other participants
-
an ASIC-administered portable unique identifier, so individuals can be tracked when they move between organisations
-
consumer-consented access to Australian Taxation Office (ATO) income data through the Consumer Data Right, to reduce reliance on documents that can be manipulated.
The ATO data proposal is not new. In April, Pannek told MPA that the MFAA had worked with the Australian Banking Association on joint advocacy, including calls to expand access to ATO data. Major banks have since made the same push to a Senate committee, arguing that AI-generated fake documents are making fraud easier to commit and harder to detect.
The FBAA, meanwhile, wants a professional conduct register. It would pull together verified information held by lenders, aggregators and industry associations to identify misconduct.
“This would not only build trust in the industry but ensure that anyone caught doing the wrong thing would have a record and the vast majority of brokers acting professionally and ethically would continue to enjoy the trust of lenders,” Gagic said.
How Australia’s mortgage fraud crisis unfolded
In February 2026, CBA contacted authorities over suspected illicit behaviour “being attempted through mortgage broking and referral channels”, with initial estimates of around $1 billion. CBA’s review reportedly found swathes of potentially doctored applications, including AI-generated submissions.
The estimate kept growing. It doubled to $2 billion as Westpac, ANZ, NAB and Macquarie reportedly began working with authorities. It was later suspected to have reached $3 billion after CBA reportedly alerted nine other lenders to referrers it suspected were tied to irregular mortgages.
Other cases followed. NAB confirmed in June that it had taken direct action against multiple parties involved in mortgage fraud. Separately, police allege that a Sydney group known as the Penthouse Syndicate defrauded the major banks of more than $250 million, with charges laid against former bank staff who moved into broking.
The syndicate case hit the broker channel directly. Andrew Hu, described by police as a central figure in the Penthouse Syndicate, operated as a broker under sub-aggregator Hai Money’s credit licence before his December 2025 arrest. That arrest set off the chain of events that ended in Hai Money’s collapse, after Finsure terminated its relationship with the sub-aggregator. Fourteen of Hai Money’s brokers were found to be under investigation, leaving more than 200 legitimate brokers without a path to market, as detailed in MPA’s coverage of Hai Money’s collapse following the Finsure fallout.
In August, the Australian Transaction Reports and Analysis Centre (AUSTRAC) revealed the findings of its Operation Claw investigation. The analysis of data from 10 major banks identified potentially hundreds of millions of dollars in suspected fraudulent loans, mostly linked to Sydney properties. The clearest recurring signal was falsified documents and the repeated use of the same brokers, accountants and law firms across multiple loans.
“The scale of this activity should be a wake-up call for every lender,” AUSTRAC chief executive Brendan Thomas said at the time.
Referral channels inside the banks have also come under the spotlight. In November 2026, the Fair Work Commission upheld CBA’s dismissal of a home lending executive who had concealed a relationship with a mortgage broker.
“Fraud is not a broker-only issue. It is a lending ecosystem issue, and the response needs to reflect that,” Gagic said.