Pepper Money data shows Scotland's homeownership gap is widest for self-employed and adverse credit borrowers

Scotland's homeownership gap is widening, creating a pipeline of clients mortgage brokers are well placed to serve. New research from Pepper Money maps where that gap is deepest – and highlights the segments most likely to respond to specialist guidance.
Pepper Money's Scotland Specialist Lending Study found 54% of 18-to-34 year olds name the cost of living as their biggest homeownership barrier. Across all age groups, 39% said affordability pressures and savings difficulties had affected their plans.
The figures sharpen among borrowers with complex financial profiles. Among non-homeowners with adverse credit, 55% cited the cost of living as their primary obstacle. One in three Scottish non-homeowners with complex income (33%) reported no savings or investments at all. That compares with 29% of non-homeowners overall. A further 20% said they lacked a sufficient deposit.
The clients most squeezed by rising costs are also, frequently, those who require specialist placement. Mainstream lenders assess affordability through payslips and credit scores. For the self-employed, contractors or those with variable earnings, that assessment rarely captures the full picture.
How wide is Scotland's homeownership gap for complex income borrowers?
Demand has not disappeared despite the financial strain. Five per cent of Scottish adults with complex income said they plan to purchase within the next year. Among the self-employed, the figure rises to 11%. That is a meaningful pipeline, one that brokers with specialist knowledge are positioned to serve.
The scale of the opportunity is well documented. Just over 11% of brokers expected difficulty placing clients with complex income or self-employment circumstances, separate Pepper Money research found. The challenge is not a shortage of demand; it is matching clients to lenders whose criteria go beyond standard assessment.
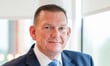
"For many aspiring homeowners more broadly, the immediate challenge is building a deposit while everyday costs continue to squeeze household budgets, with 20% saying they do not have enough saved for one," said Paul Adams (pictured above), director of sales at Pepper Money.
"Savings challenges can quickly become homeownership challenges, especially for customers with complex income or adverse credit, whose circumstances may not fit neatly into standard lending criteria," Adams said. "That is where specialist lending and broker expertise can make a real difference, helping customers be assessed on the substance of their circumstances."
Where adverse credit borrowers are looking for help
The research identifies one group as particularly receptive to broker engagement: those with a history of adverse credit. Forty-two per cent of Scottish adults with adverse credit said they were worried about the mortgage application process. The same proportion expressed concern about securing a mortgage at all.
This is where brokers can step in. Clients in this segment are not walking away from homeownership; they are looking for someone to show them a route in. Understanding how specialist lenders assess adverse credit cases allows brokers to provide that answer. This is also the client group most actively seeking their guidance.
Pepper Money released the findings alongside its First Charge mortgage launch in Scotland, extending its residential and buy-to-let range to Scottish intermediaries. The lender already operates a second charge business in the region. It has appointed Michael Walsh, who brings more than 25 years of intermediary experience, as regional development manager.
For brokers, closing Scotland's homeownership gap starts with understanding which clients the high street cannot serve. Building the specialist lender referral pathways to reach them is the practical next step.