Housing wealth gains ground as retirement planning tool, UK Finance data shows

Later life lending rose in the second quarter of 2026, with 37,300 new loans advanced to older borrowers — a 13.4% increase on the same period a year earlier, according to UK Finance's latest Later Life Lending update.
The total value of that lending reached £6.2 billion, up 20.5% year on year. However, UK Finance cautioned that the annual comparison is distorted by a temporary fall in activity that followed the rush to complete transactions ahead of stamp duty changes introduced in April 2025.
Lifetime mortgage volumes edged down 1.7% year on year to 5,730 new loans in Q2, though they recovered 8% from Q1 2026. The value of new lifetime mortgage lending was £490 million.
Retirement interest-only (RIO) mortgages saw 323 new loans advanced in Q2, up 5.9% year on year, with the value of that lending reaching £31 million — a 24% increase on Q2 2025.
Later life loans accounted for 7.8% of all residential mortgage lending in Q2, and 20.6% of all buy-to-let lending.
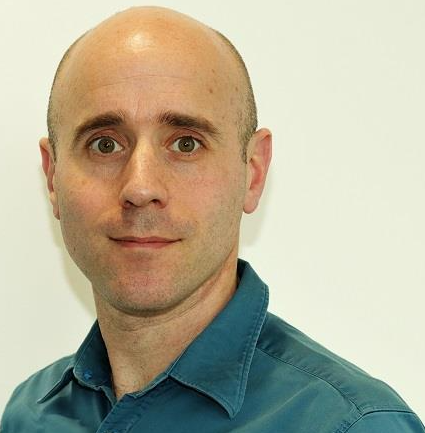 "Later life lending rose in the second quarter, with both the number and value of loans to older borrowers increasing compared with a year earlier, although the annual comparison reflects the temporary dip in activity following last year's stamp duty changes," said James Tatch (pictured right), head of analytics at UK Finance. "Lifetime mortgage lending also recovered from the first quarter, while retirement interest-only mortgages recorded further year-on-year growth."
He added that the figures underline the role later life lending plays across the broader mortgage market, particularly in buy-to-let, and that customers should seek advice to identify the most suitable product for their circumstances.
Jim Boyd, chief executive of the Equity Release Council, said the data showed the later life lending market continuing to develop as housing wealth becomes a more significant component of retirement planning. He also noted the Financial Conduct Authority's recognition of later life lending as a potential fourth pillar of retirement funding — alongside pensions, savings and investments — as reflective of a broader shift in how people approach their finances in later life.
"This is about more than market growth," Boyd said. "It is about ensuring consumers can access the right guidance and advice to make informed decisions about all their assets."
He cited Fairer Finance modelling suggesting that 51% of households aged 60 and over could benefit from accessing housing wealth by 2040, and called on the industry to build on stronger standards, greater product flexibility and the FCA's fourth-pillar framework to deliver good consumer outcomes at scale.
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.