First-time buyer scheme, landlord taxes and market stability – industry reacts to chancellor John Healey’s first Budget

Amid a raft of new measures announced in chancellor John Healey's first Budget, there was plenty for housing and mortgage market watchers to chew over.
The housing policy that has grabbed most headlines recently – and on which Healey unveiled further details on Wednesday – was the Your First Home scheme, a bid to ease affordability hurdles for first-time buyers. The equity loan scheme will allow eligible buyers to put as little as 2.5% down for a deposit, with an initially interest-free government loan totalling 20% of the property's value helping fund the purchase. Backed by £4.7 billion, it is expected to help around 70,000 households onto the ladder.
The Budget also saw further taxes imposed on banks, but shares in the UK's banking giants received a boost, with the announced surcharges lower than many had previously feared. Last week, the International Monetary Fund (IMF) sounded a warning on raising bank taxes, saying it was not the best way for the British government to increase fiscal headroom. Healey confirmed he was raising the bank surcharge by three percentage points to 6% – below its pre-2023 level of 8% and lower than the City had anticipated, with the measure time-limited to 15 months.
Holiday let landlords took note of the announcement that from 2028, mayors and some local authorities will gain the power to introduce overnight visitor levies – adding further potential pressure after the withdrawal of furnished holiday lettings tax relief. There was also tax relief for founders of successful firms, in the form of a 10% rate on lifetime gains of up to £10 million – a measure likely to have turned heads among mortgage industry entrepreneurs and self-starting brokers.
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
What Your First Home means in practice
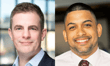
David Hollingworth (pictured top left), associate director at L&C Mortgages, welcomed the clarity on Your First Home's timelines but cautioned that detail is still emerging. "There is a bit more detail coming out, but there is still more to come," he told Mortgage Introducer. Among what is now confirmed: the government loan is interest-free for the first five years, before an interest charge kicks in at 1.5% and doubles from year seven. "I wonder if that will put a bit more focus for users of the scheme on repaying the equity loan sooner rather than later," Hollingworth added.
Nicholas Mendes (pictured top right), mortgage technical manager at John Charcol, described Your First Home as the most significant support for first-time buyers since Help to Buy closed, but was clear about its limits. "Limiting the scheme to new builds means it will do little for the wider housing market," he said. "Most first-time buyers purchase existing homes, and those purchases are what allow sellers further up the chain to move."
Lifetime ISA changes – and what stays the same
Healey confirmed that a new First Time Buyer ISA will eventually replace the Lifetime ISA, but the transition will not take effect until 2029. The Lifetime ISA (LISA) continues in its current format in the meantime, with the government bonus maintained at its existing level.
The property price cap on the existing LISA remains at £450,000 – a threshold Hollingworth acknowledged will continue to exclude some buyers in higher-value parts of London. He pointed to one immediate improvement, however, with the LISA withdrawal penalty for buyers purchasing above £450,000 reduced, effective from 29 October.
Stamp duty – a missed opportunity
One area where the Budget fell short of industry hopes was stamp duty. Healey made no changes to the tax, leaving brokers and borrowers without the relief many had called for. Hollingworth said the industry had held out some hope. "Perhaps there could have been a bit more relief for first-time buyers, or potentially new relief to try and encourage downsizing," he said. "I guess we were holding out that he'd kept something up his sleeve, but for the most part this was a well-managed release of information in the run-up to and on the day."
Mendes was equally direct about the consequences. "Stamp duty remains one of the biggest costs of moving home, and leaving it unchanged will continue to put some homeowners off moving," he said, adding that relief targeted at downsizers in particular would free up larger family homes and create more movement across the market.
Bank surcharge – smaller than feared
Hollingworth said the smaller-than-expected bank surcharge increase would be received positively, and noted bank share prices had already risen in anticipation.
On whether the additional cost could filter through to mortgage rates, he was measured: "Hopefully the fact that it is smaller than many had anticipated means we'll see very little impact for mortgage borrowers."
Buy-to-let landlords face higher income tax
Landlords saw rental income tax rates confirmed as rising – to 24% for basic-rate taxpayers, up from the previously anticipated 22%. Hollingworth was blunt about the cumulative effect: "That comes on the back of all the other changes that have put the squeeze on buy-to-let landlords."
Mendes warned the increase could accelerate an existing trend. "More individual landlords are likely to consider selling as a result," he said. "And if more of those homes are bought by owner-occupiers, it will further reduce the number of homes available to rent and put upward pressure on rents."
Markets steady – and what comes next
One of the mortgage industry's chief concerns heading into the Budget was market turbulence – any fiscal misstep risked pushing swap rates and fixed mortgage pricing higher. That scenario did not materialise, with government borrowing costs edging slightly lower on the day across two, five, 10 and 30-year terms.
Hollingworth was relieved but measured. "What we absolutely did not want was any big market reaction," he said. "We've kind of reached some semblance of stability at the moment, albeit at elevated rates."
On the Budget's implications for the Bank of England's next base rate decision – due on 5 November – he added: "I don't think today's announcement adds to that. I think the Bank of England will be looking at it independently, and hopefully we won't see any market reaction which forces any further action."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.