A ‘clear escalation’ in cash flow pressure is causing a sector-agnostic headache for Aussie firms

Late payments across Australian businesses have hit their highest level in eight and a half years, with one in 10 invoices now more than 60 days overdue, according to credit reporting bureau CreditorWatch.
CreditorWatch’s September 2026 Business Risk Index shows the share of invoices outstanding beyond 60 days has doubled from 5% to 10.1% in just 12 months – the highest reading since April 2018. Just 48% of invoices are now paid by their due date, down from 58% a year earlier.
For mortgage brokers, the figures are an early read on the financial health of self-employed and small-business borrowers – a segment where cash flow strain tends to show up in loan applications well before it reaches official arrears data.
‘Clear escalation’ in cash flow pressure
The deterioration is no longer confined to a handful of sectors. Trade payment defaults – where one business formally registers an unpaid invoice against another – rose by more than a quarter year on year.
CreditorWatch’s seasonally adjusted trade payment default index stood at 196 in September, which is almost double pre-pandemic levels (from a base line of 100 in February 2020).
Defaults registered in the three months to September were 6.8% higher than in the three months to June.
Patrick Coghlan, chief executive of CreditorWatch, said the trend had moved well beyond slow payers.
“The September data shows a clear escalation in business cash flow pressure. Businesses are not just paying a few days later. We’re seeing a growing share of invoices drift into serious delinquency, with one in 10 now more than 60 days overdue. That’s a strong warning sign because payment delays are often the first indicator of emerging financial stress,” Coghlan said.
Construction, transport and hospitality hit hardest
Construction recorded the sharpest deterioration, with its share of seriously overdue invoices more than doubling over the year. Transport, postal and warehousing, manufacturing, retail trade, mining and utilities saw similar or steeper rises, and CreditorWatch noted that many of these industries deteriorated rapidly through the September quarter.
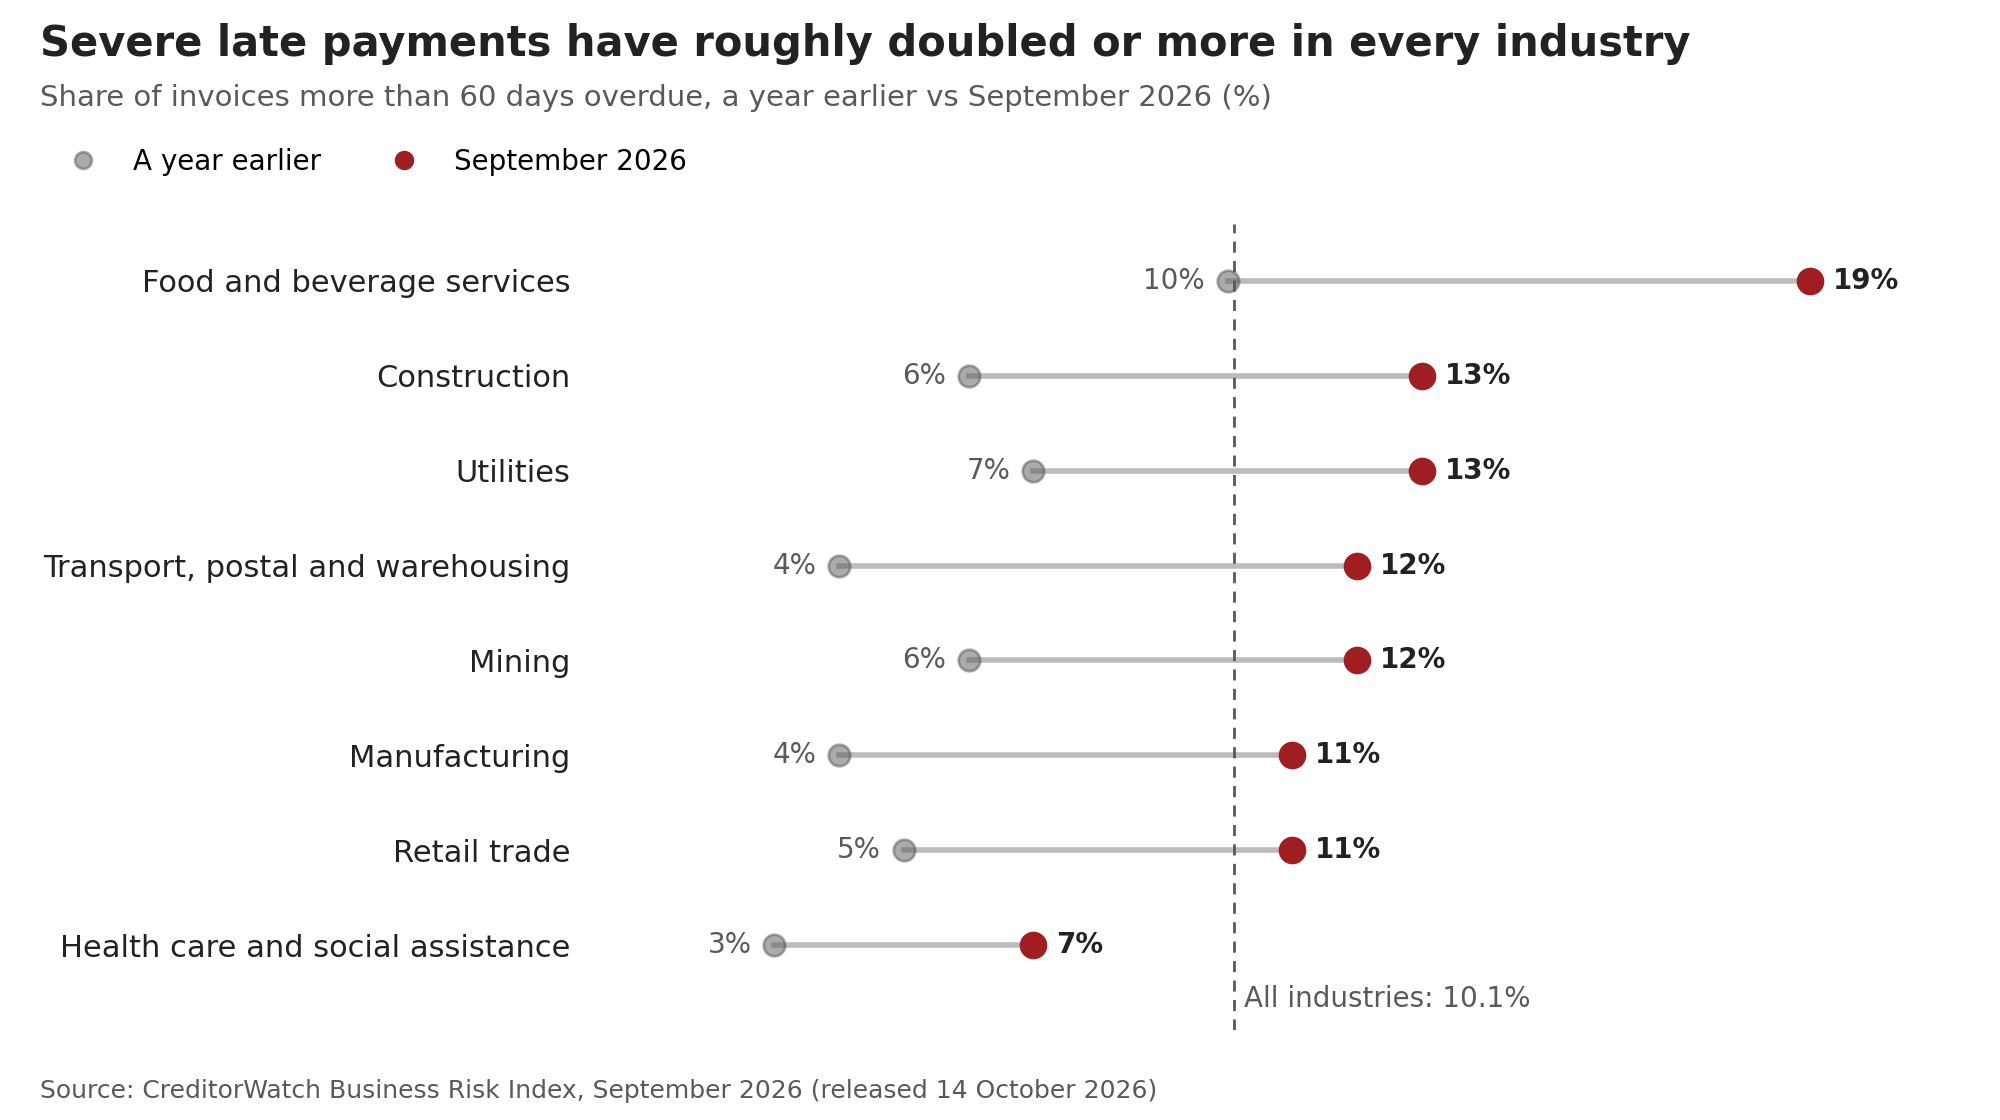
Food and beverage services remains the weakest performer, with almost one in five payments more than 60 days overdue. Even health care and social assistance – still the best performer – has seen its rate of severe payment delays more than double.
Tax defaults climb
The strain is also showing up in obligations to the Australian Taxation Office (ATO). Tax debt defaults in effect reached 37,577 in September, up 20.7% on a year earlier and 5,289 higher than in January. A further 2,024 new tax defaults were lodged in September, and new defaults continue to outpace removals.
“Record ATO tax defaults show many businesses are falling behind on what they owe the tax office, not just their suppliers. Tax debt is often one of the first obligations to slip when cash flow tightens, and if it isn’t addressed it can escalate quickly. With interest rates at their highest level in 15 years and fuel costs remaining elevated, creditors should be keeping a close eye on their exposures,” Coghlan said.
Read more: Labor overrules ATO credit card payment ban
Company insolvencies remain volatile. First-time insolvencies fell to 934 in September from a record of more than 1,800 in August, though the August figure included more than 500 companies from the failed Bathla/Universal Property Group.
Escalating pressures
CreditorWatch chief economist Ivan Colhoun (pictured) said rising costs were compounding the rate pressure.
“The pressures on Australian businesses continue to build. Official interest rates are now at the highest level for 15 years (though admittedly only 0.25% above the peaks recorded in 2025). High oil and diesel prices add to those pressures, building on the considerable increase in costs that businesses have already experienced over the past five years. The high minimum wage and award wage rises granted by the Fair Work Commission this year haven’t helped either.”
He expects the economy to keep diverging by sector, with technology, parts of mining and construction, defence and renewables among the winners.
“Conditions are likely to prove increasingly challenging for businesses (and consumers) with large debts; interest-sensitive sectors of the economy, including residential construction and real estate; businesses reliant on discretionary spending; and low-income earners. It is likely that insolvencies will begin to rise in coming months as a result,”
For brokers, the data suggests more self-employed clients will arrive with stretched cash flow, overdue tax obligations, or both – making early conversations about serviceability, debt consolidation and lender choice more important.