‘The commencement of the AFIA Code is the culmination of many years of work, cross-industry engagement, and collaboration to set the standard’

Non-bank and specialist lenders across Australia are operating under their own industry code of practice from today, as the Australian Finance Industry Association (AFIA) Finance Industry Code of Practice takes effect.
The voluntary code sits alongside existing responsible lending obligations in the National Consumer Credit Protection Act 2009 (NCCP Act), which the Australian Securities and Investments Commission (ASIC) enforces.
Banks have long operated under the Banking Code of Practice, but until today, non-bank lenders had no equivalent whole-of-industry benchmark.
Bluestone Home Loans chief commercial officer Tony MacRae called being an AFIA member “a public statement that is just formalising what we've already been doing”.
“We think this is important to ensure that we're all abiding by these practices," MacRae told MPA. “it's formalising what we've all been doing. As a result, we're more than happy to be a participant in it.
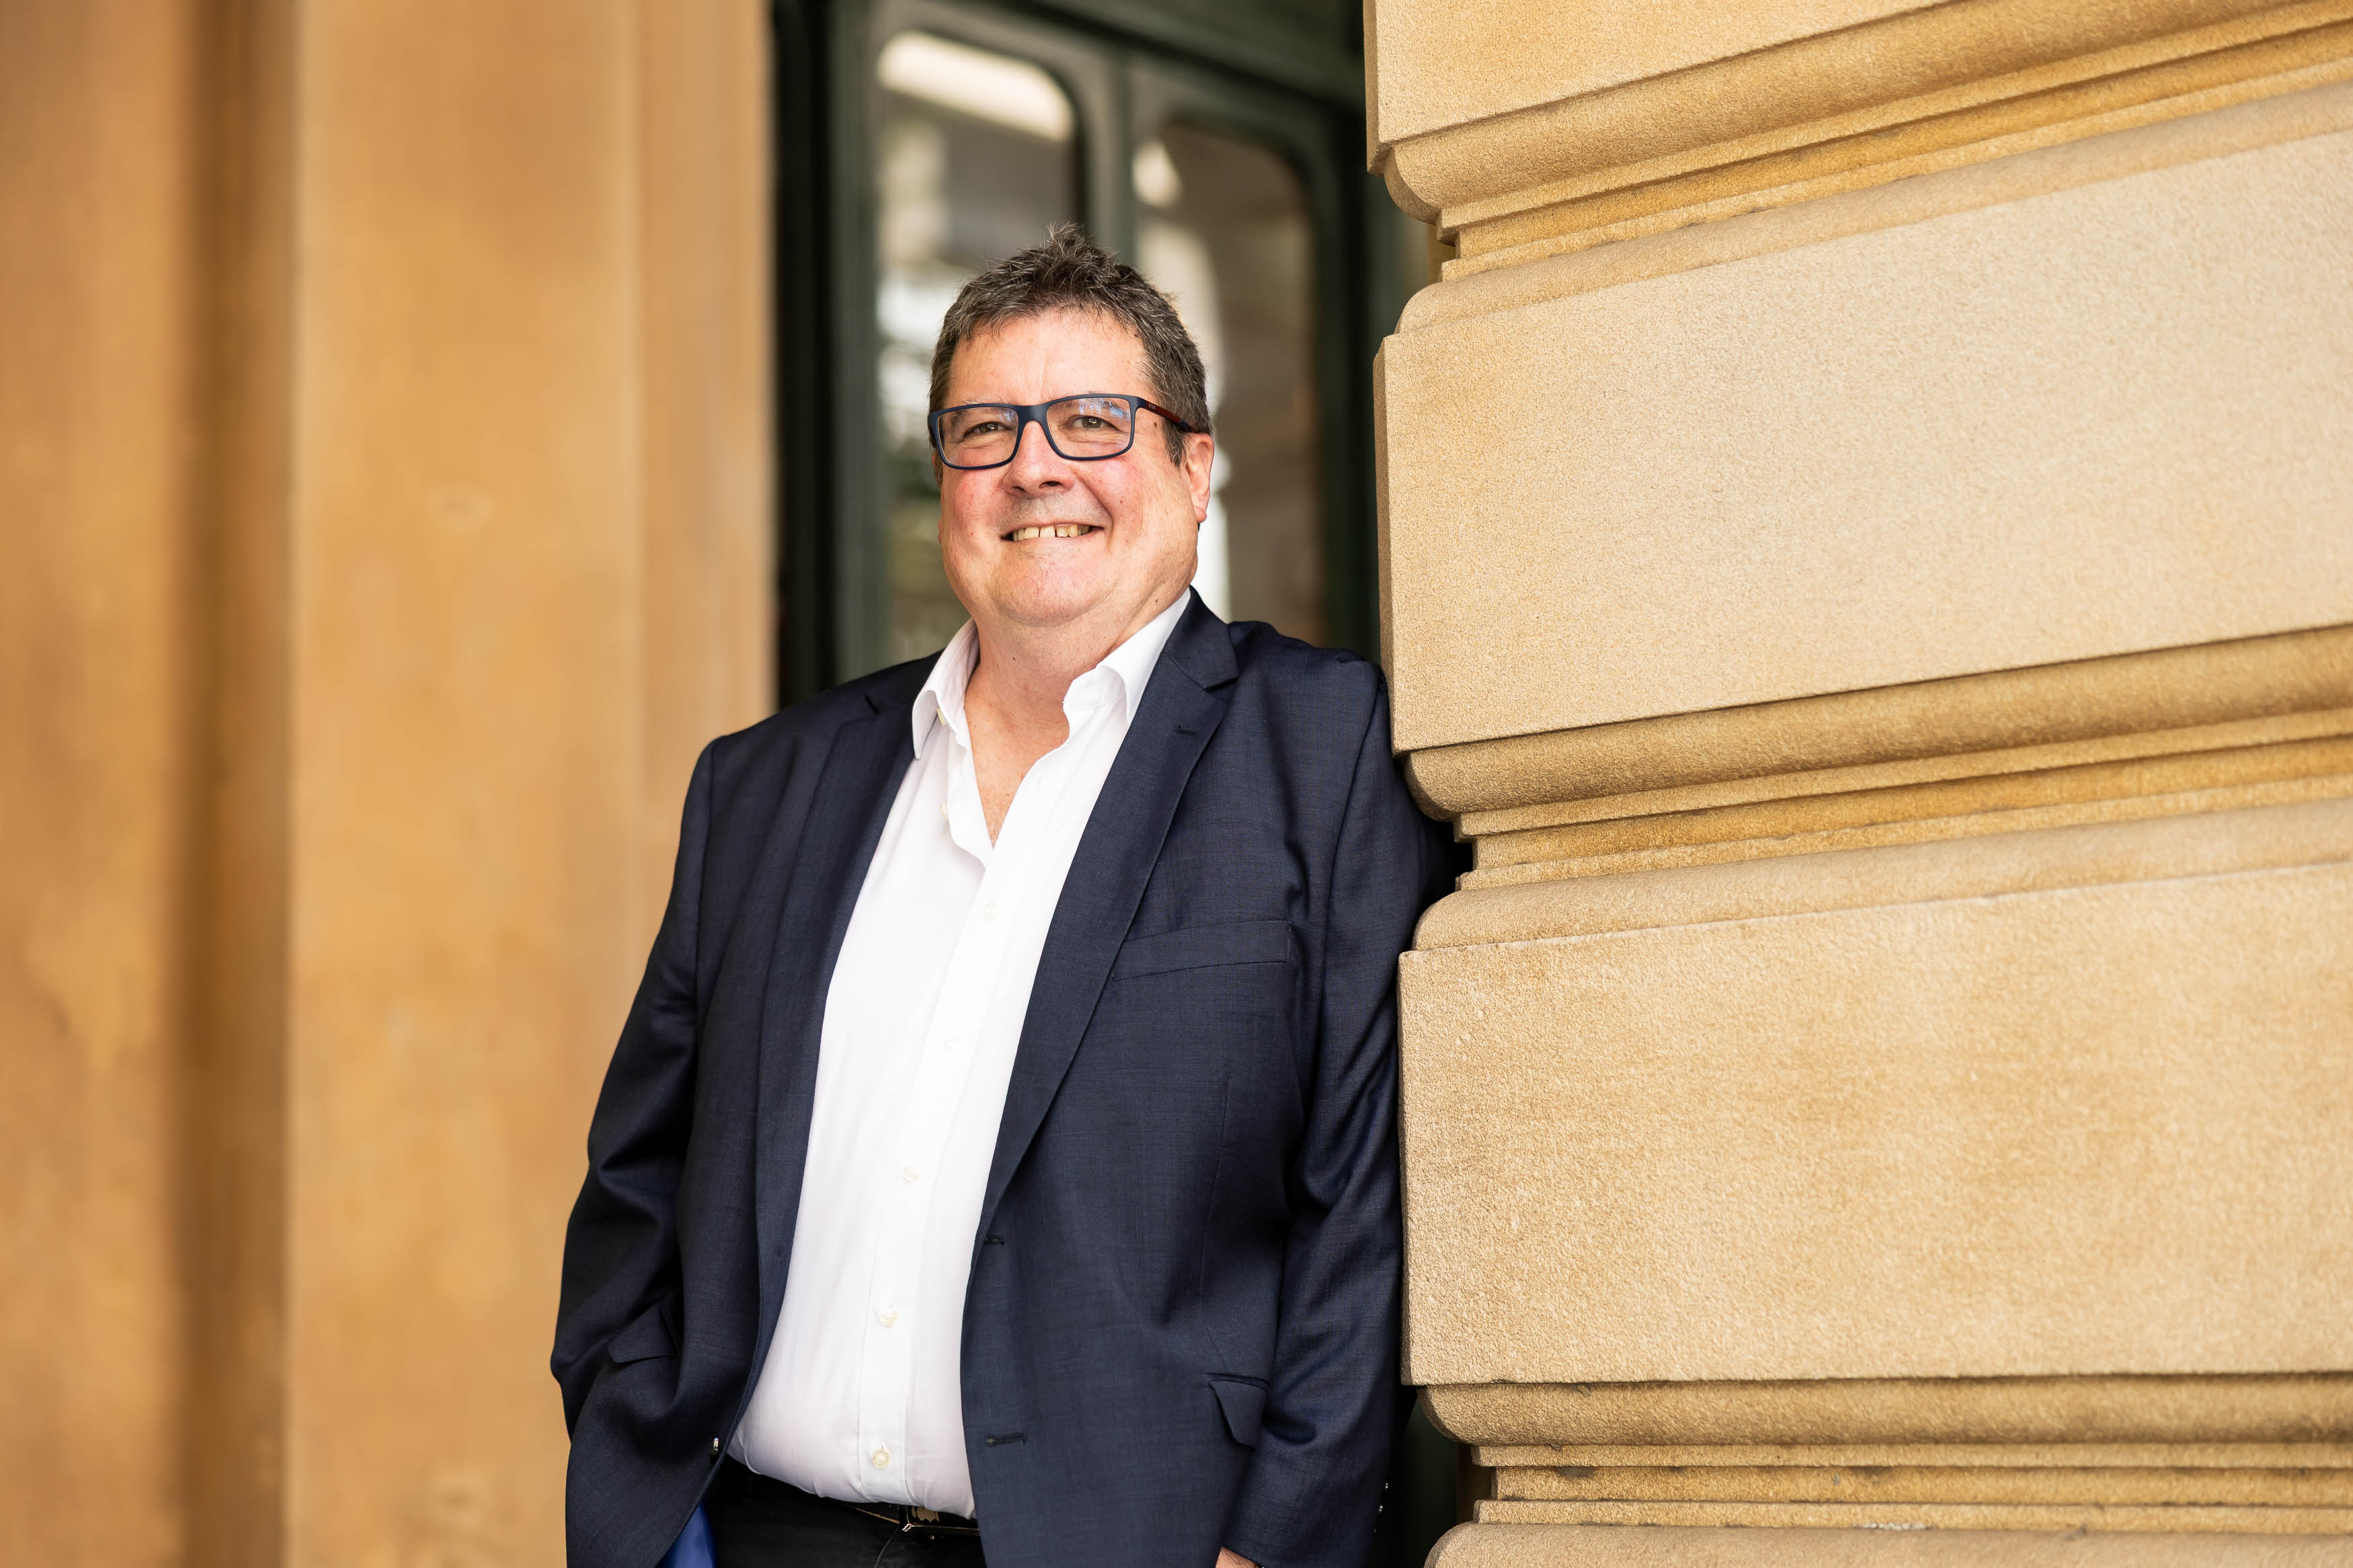
MacRae (pictured, below) also sees the AFIA Code of Practice as a strong lobbying platform in the interests of the non-bank lending sector.
While the law sets the floor, the AFIA code commits signatories to standards above it – with an independent committee on standby to call out breaches.
The code brings Australian non-bank and specialist lenders together under a single framework for consumer and business finance. Its commitments cover clearer communication, support for customers in hardship or experiencing vulnerability, protection from scams and financial abuse, cybersecurity, the responsible use of artificial intelligence (AI), and complaint and dispute handling.
"Today, commitment becomes practice,” said AFIA chief executive Diane Tate (pictured, top of page). “Non-bank and specialist lenders are stepping forward, making themselves publicly accountable and demonstrating their determination to deliver stronger protections and better outcomes for the millions of Australians they serve.”
Tate told MPA the code was built alongside the regulator, not around it.
"Like any industry sector, regulators and industry bodies play important yet distinct roles. In recognition of ASIC's regulatory oversight of non-bank lenders, AFIA developed its Finance Industry Code of Practice in consultation with ASIC, and the AFIA Code sets expectations that align with key focus areas for ASIC intended to improve customer outcomes.
"However, ASIC isn't the only regulator or stakeholder we worked with on the Code's development. The commencement of the AFIA Code is the culmination of many years of work, cross-industry engagement, and collaboration to set the standard. And, as industry developments and customer expectations evolve, so will the Code."
Tate drew a direct line between what the law requires and what signatories are now promising.
"AFIA members offer a broad range of products, services and technologies to consumers and small business customers. While consumer credit is regulated under the NCCP Act (including responsible lending obligations), AFIA members are committing to high standards across finance, including better disclosure practises, responsible use of technology and AI, fraud and scam protection, and fair treatment of customers, especially help for financial difficulties and access to dispute resolution.
"The AFIA Code is industry leadership in action. It is not a once-off compliance exercise. It is an enduring framework through which members will be expected to learn, adapt and demonstrate how their businesses support good customer outcomes."
The full text of the AFIA Finance Industry Code of Practice and its scope is published on the association's website.
What happens when a lender breaches the code?
The code's teeth sit with the Finance Industry Code Compliance Committee (FICCC), which monitors signatories independently of AFIA. As a non-government body, the committee's enforcement capabilities are limited in scope; options run from rectification orders to public naming.
“Among other things, the Committee's role is to continuously monitor AFIA Code compliance, investigate alleged breaches of the AFIA Code and make determinations on breaches," Tate said.
"This may include requiring the AFIA Code member to undertake a rectification process or other remedial action, issuing a formal warning, publicising notice of non-compliance, reporting a breach to a regulatory body or recommending that the AFIA Board reviews, suspends or terminates AFIA membership."
FICCC independent chair Tim Grimwade congratulated AFIA and its members on the commencement, and put the onus on lenders still outside the code.
"AFIA has tasked the FICCC with an important oversight and monitoring role in relation to code compliance, and we look forward to working with AFIA Code members in improving standards across the industry and providing better outcomes for customers.
"Non-bank lenders and other finance industry participants that are serious about playing their part in building trust, transparency and fairness in the industry need to join the AFIA Code to demonstrate that commitment to their customers."
Which non-bank lenders have signed the AFIA code?
In February 2026, Pepper Money became the first non-bank lender approved as a code member, having helped shape the framework through AFIA working groups. Chief executive Mario Rehayem, who has chaired AFIA since March 2024, told MPA at the time that the code "makes existing protections more visible" and lifts customer support to a more consistent level across the sector.
Bluestone Home Loans joined in August 2026, committing to fair and responsible lending, clear communication, hardship support and accessible dispute resolution. Chief executive Mark Jones said: "The Code provides an important framework for ensuring customers are treated fairly and consistently.”
Last month, RedZed was accredited as a code member for self-employed lending. "Brokers place significant trust in the lenders they recommend," said managing director Calvin Cordle, adding that membership signals brokers can keep recommending RedZed with confidence.
They join specialist and fintech lenders including Prospa and Brighte, while AFIA added Zip and Payright as code members in May 2026.
Tate hopes the list of signatories will continue to grow, saying: "AFIA is actively working with its members transitioning to Code compliance. We are also seeing others joining AFIA to be part of the AFIA Code. We look forward to welcoming more Code signatories in due course."
"Trust is built through behaviour, not intention," Tate added. "This is how we finance Australia's future: by working together, taking responsibility for the standards we set, and ensuring competition, innovation and growth are underpinned by integrity, fairness and care for customers, well into the future."