Self-employed lending just got a new benchmark. Here's what RedZed's AFIA accreditation means for your non-bank panel

RedZed has been accredited as a Code Member of the Australian Finance Industry Association (AFIA) Finance Industry Code of Practice, raising the bar for self-employed lending in Australia's non-bank sector.
The AFIA Code takes full effect on 1 October 2026, following an industry transition period. It is the first whole-of-industry code for Australia's non-bank and specialist lending sector.
Standards under the Code cover conduct, product transparency, customer protection, responsible use of technology, support for vulnerable customers, and dispute resolution. The Code is independently monitored by the Finance Industry Code Compliance Committee (FICCC).
What does AFIA code membership mean for brokers placing self-employed clients?
The self-employed lending segment remains one of the hardest to place. Brokers working with clients outside standard serviceability benchmarks rely heavily on the reputational standing of the lenders they recommend.
RedZed's Code membership adds a layer of independent accountability to those referral decisions – one that goes beyond product competitiveness or relationship history. Brokers wanting to build out their self-employed client base can review RedZed's broker education program and accreditation resources.
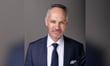
"Brokers place significant trust in the lenders they recommend," said Calvin Cordle (pictured above), managing director of RedZed. "Our membership demonstrates our commitment to maintaining high standards and ensuring brokers can continue to recommend RedZed with confidence."
The scale of RedZed's broker network
RedZed has provided more than $9.7 billion in loans to over 23,000 self-employed Australians since it started in 2006.
The lender operates primarily through the broker channel. More than 5,000 mortgage brokers are currently accredited to offer RedZed products. For that cohort, the lender's conduct standards and dispute resolution processes are operational concerns, not background policy.
What protections does the AFIA code offer clients who don't qualify with major banks?
For contractors, sole traders, and business owners with variable income, the quality of a lender's customer protections can determine how a hardship event plays out.
The AFIA Code requires members to provide strengthened safeguards against scams and fraud. It also mandates support for customers in financial difficulty and access to efficient complaints and dispute resolution processes. These obligations apply to residential mortgage products within scope.
"Ultimately, this is about strengthening trust," Cordle said. "It gives customers confidence that they are dealing with a lender committed to fairness, transparency and support throughout their lending journey."
A growing signal for self-employed lending
Brokers writing business through specialist lenders have always carried some risk around whether those lenders hold equivalent conduct standards to their major bank counterparts. Code membership under an independently monitored framework narrows that gap.
As more non-bank lenders seek accreditation ahead of October, brokers will have a more reliable signal for assessing lender partners.
Cordle said the accreditation reflects nearly two decades of operating in the specialist space.
"For almost 20 years, RedZed has been helping self-employed Australians access finance through trusted broker relationships," he said. "Becoming a member of the AFIA Finance Industry Code of Practice reinforces our commitment to acting responsibly, communicating transparently and delivering positive customer outcomes."