Younger Australians are getting a leg up into the housing market – but could first-home buyer remorse be close behind?

It’s rare to have so much policy attention – and so much policy contradiction – aimed at a single demographic. But anything seems possible in 2026.
Take first home buyers.
The federal government’s expanded 5% Deposit Scheme, now uncapped on both income and places, has stripped away one of the biggest barriers standing between renters and their first purchase: the deposit itself. No more waiting years to scrape together 20%. No more paying Lenders Mortgage Insurance just to get in the door. For a generation that’s watched home ownership drift further out of reach with every passing year, it looks, on paper, like a genuine turning point.
Then the May Budget came crashing into the housing market like a bull in a china shop, with changes that have completely upended the housing narrative – changes experts warn could have some dramatic unintended consequences for the first-home buyer cohort.
Add falling prices that aren’t matched by falling interest rates, and a housing downturn that could erase over a trillion dollars in property wealth, and the picture gets even murkier.
The deposit scheme paradox
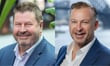
Twelve months into the substantially expanded 5% Deposit Scheme, Blake Buchanan (pictured, right), general manager of mortgage aggregator Specialist Finance Group (SFG), has seen the interest surge accordingly. “For many first-home buyers, servicing isn’t necessarily the initial problem, accumulating a deposit while paying increasingly high rents is,” he says.
But while the scheme has broadened access, Darren McLeod (pictured, left), Beyond Bank’s head of third party and lending solutions, notes the shift hasn’t dramatically changed who is applying. He agrees, though, that the scheme is particularly useful for customers with the income capacity to service a home loan “but who would otherwise need to spend several more years saving for a larger deposit”.
So far, so good on the policy front for first home buyers, yet the government seems all too willing to give with one hand and take with the other. There is mounting concern that the monumental tax changes announced in the May Budget – specifically, the removal of negative gearing and capital gains tax (CGT) benefits – will result in heightened competition from the investor class for homes at the affordable end of the spectrum – the very homes that younger buyers see as their entry to the housing market.
Buchanan says, “I’m… concerned investors may increasingly move towards lower-priced properties, where yields are typically stronger. That’s precisely the market first home buyers occupy. If investors move down the price curve while reduced rental supply contributes to higher rents, first home buyers could face greater competition for property while simultaneously finding it harder to save their deposit.”
McLeod sees a related pressure point building in a different corner of the market: the negative gearing and CGT carve-outs for new-build properties have increased investor interest in new-build construction, “which may lead to stronger competition in that segment of the market”.
Yet in the near term, first-home buyer activity appears to be outpacing the investor cohort. Australian Bureau of Statistics data shows first home buyer loan commitments fell 2.9% quarter-on-quarter in the June quarter, compared with an 8.6% quarterly drop in investor loan commitments – nearly three times the pullback. The gap widens further by value: first home buyer lending edged up 0.2% over the quarter while investor lending value fell 10.2%.
That divergence raises the obvious next question: are first home buyers actually gaining ground, or is investor retreat simply flattering the numbers?
Not quite a silver bullet
At face value, falling house prices sound like a godsend for prospective buyers, but as is usually the case, the reality is more nuanced.
“In a housing market where borrowing capacity is closely linked to income growth, slower price appreciation can improve affordability and make it easier for first home buyers to enter the market,” McLeod says. “However, these measures alone are unlikely to solve Australia’s housing affordability challenges. The fundamental issue remains a shortage of housing supply relative to demand.”
There’s also the fact that house prices are coming down, but interest rates certainly are not. McLeod argues that a modest reduction in interest rates “can materially improve borrowing power and loan servicing capacity, often more than a small decline in property values”. However, thanks to four rate rises from the Reserve Bank of Australia in 2026, and a likelihood of more to come, the trend is currently moving in the opposite direction.
Buchanan takes a harder line on what falling prices actually mean in aggregate: “Some will benefit [from falling house prices], but I fear significantly more Australians will be adversely affected. Some forecasts suggest the housing downturn could ultimately erase more than $1 trillion in residential property wealth. Making millions of existing homeowners poorer is a very blunt instrument for improving housing affordability.”
His preference is for prices to be supported rather than destroyed: “We should be focused on increasing housing supply rather than destroying existing housing wealth.”
“If investors move down the price curve while reduced rental supply contributes to higher rents, first home buyers could face greater competition for property” – Blake Buchanan, SFG
McLeod strikes a similar note: “A more sustainable outcome would be a period of slower or relatively flat house price growth, allowing wages and household incomes to gradually catch up.”
The overlooked risk: negative equity and squeezed savings
For low-deposit homeowners, falling prices are exactly where negative equity risk starts to bite, since a 5% equity buffer leaves very little room to move should house prices fall by double digits.
That’s less of a concern for a homeowner who wants to stay put.
Negative equity, McLeod notes, “only becomes a real issue if a homeowner needs to sell or refinance while the property’s value is below the outstanding loan balance. For buyers who remain in their home and continue meeting their repayments, a temporary decline in value is often just that, temporary.”
But life events can sometimes get in the way. As Buchanan says, “The danger comes if unemployment, illness or another life event forces a sale. If the sale doesn’t extinguish the mortgage, the borrower can potentially lose their home and still owe money to the lender. That’s a serious risk and reinforces the importance of appropriate insurance and financial buffers.”
Compounding the problem is the squeeze on household budgets more broadly. “Higher everyday expenses, including rent, groceries, utilities and insurance, mean there is often less disposable income available to put towards savings each month,” adds McLeod.
“A more sustainable outcome would be a period of slower or relatively flat house price growth, allowing wages and household incomes to gradually catch up” – Darren McLeod, Beyond Bank
What buyers – and brokers – should do differently
With soaring monthly repayments grabbing the headlines lately, it is understandable that brokers have an impetus to get their clients onto the lowest rate possible. But going down this path could actually do more harm than good.
“Preserving cash is often just as important as achieving a competitive rate,” says McLeod. For brokers, the risk of over-indexing on rate is compounded by a second mistake: writing a client off too early. McLeod says it’s worth asking more questions rather than assuming a thin savings balance rules someone out – digging deeper often turns up alternatives like a parental gift, proceeds from selling other assets, or a strong rental payment history that can satisfy genuine savings requirements instead.
For its part, Beyond Bank is an active participant in the government scheme, and for buyers outside the scheme’s eligibility, McLeod points to a parent equity option allowing borrowing of up to 110% of the purchase price, alongside fully assessed pre-approvals lasting 120 days – giving buyers room to negotiate in a competitive market. Servicing settings help too: the bank takes 100% of allowances and overtime where ongoing, excludes HECS/HELP debt due within two years, and counts 100% of most government pension income expected to continue for at least five years.
Buchanan makes a case for zooming out rather than fixating on the here and now. “The most common mistake I see is focusing entirely on interest rates and today. Borrowers should also consider government assistance, lender policy, total costs and their medium-term circumstances. Think about where your career, family and finances could be in three to five years, not simply what you can borrow today.”
That often means front-loading the work before a client even starts looking. Buchanan recommends starting the planning process as early as possible. “Understand the client’s deposit, borrowing capacity, scheme eligibility, grants and lender options before they find the property. Establishing a realistic purchasing range early allows a first home buyer to negotiate confidently and avoids disappointment later,” he says.
Amid these shifting dynamics, first home buyers can at least agree on one thing: with brokers now settling nearly 82% of all residential home loans, they know exactly where to turn for guidance through an increasingly complicated market.