But it’s not as gloomy up north

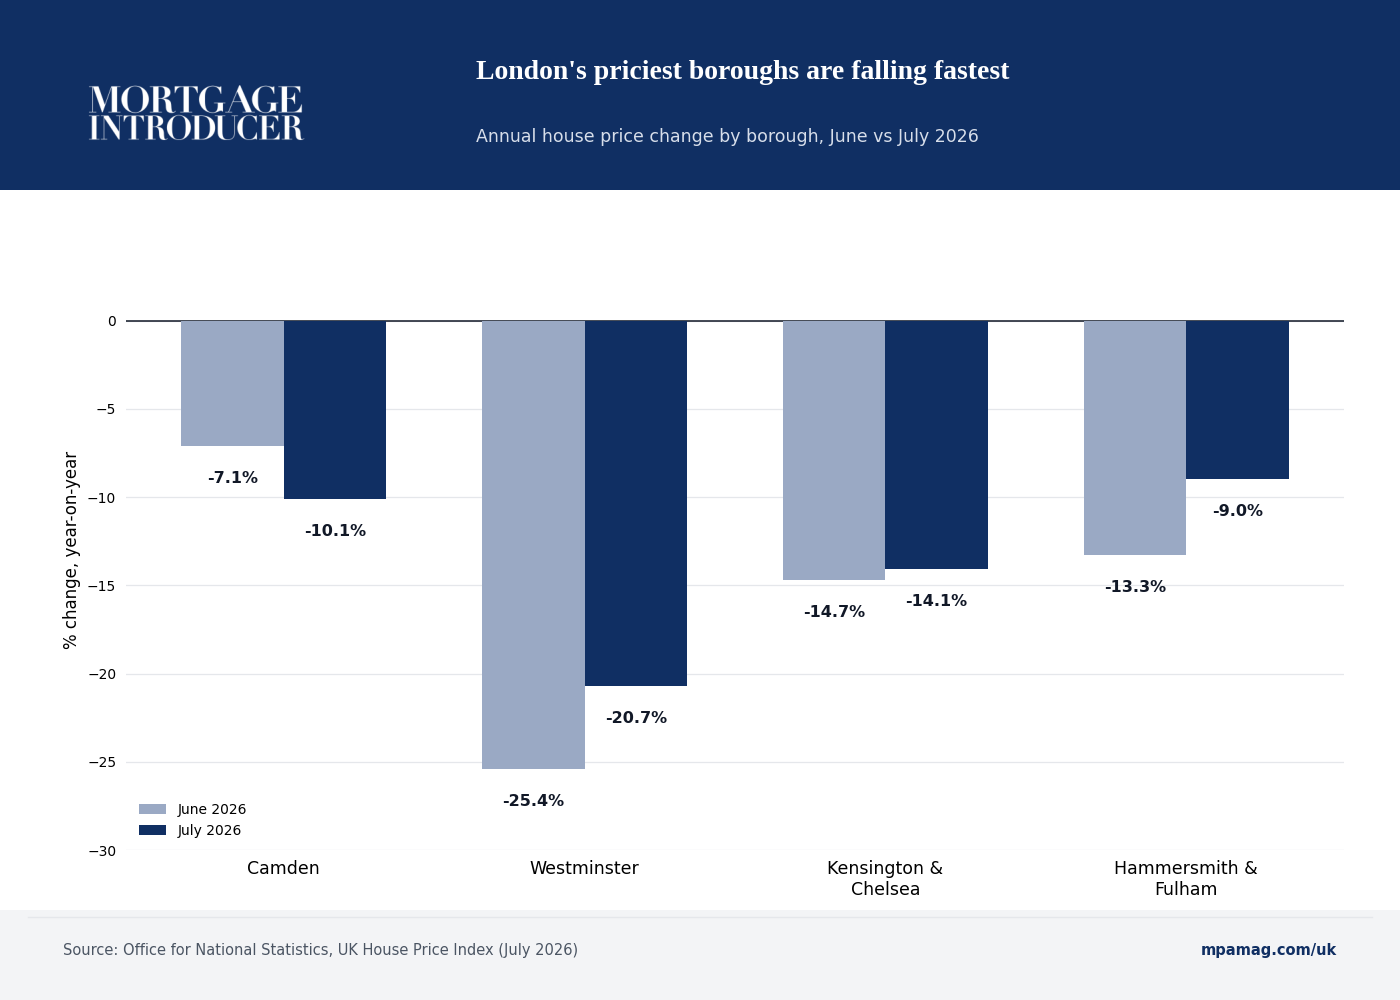
Here's the thing about London's property market right now: the more expensive the postcode, the harder it's falling. The average home in the capital dropped 3.3% in the year to July, according to the Office for National Statistics worse than June's 2.5% fall. But zoom in on the boroughs everyone associates with London wealth, and the numbers get properly stark.
Camden (Hampstead, Highgate, Primrose Hill) saw its annual losses jump from 7.1% to 10.1%, dragging the average price down to £815,000. Westminster is down 20.7% to £877,000.
Yes, that's actually better than June's eye-watering 25.4% fall, but "better" is doing a lot of work in that sentence.
Kensington and Chelsea eased slightly to 14.1%, Hammersmith and Fulham to 9%. This is now London's 11th straight month of annual price falls, and Sarah Coles, head of personal finance at AJ Bell, reckons she knows why: London's prices are so high that stamp duty bites harder here than anywhere else, and plenty of would-be buyers simply don't have that kind of headroom left.
Read next: Why high-net-worth clients can't afford to wait for rates to fall
Lenders are already feeling this. Down-valuations are creeping up across the whole UK market, not just London. The average newly listed property is now priced 11.6% above its independent valuation, more than double last year's 5.7% gap, according to TwentyCi's latest report. That gap always widens fastest where the market's falling, and right now that's London's priciest boroughs, where plenty of sellers are still pricing against a peak that's long gone.
If you're working prime cases, it's worth flagging the risk of surveyor pushback to clients before the offer goes in, not after.
A lot of this market doesn't touch a mortgage at all though. Historically, around half of prime central London sales have gone through in cash, according to Knight Frank so however dramatic these figures look, they only tell part of the story for brokers. Where the lending market actually has skin in the game is further out: Fulham, Clapham, Wandsworth, the family-home areas where buyers need finance rather than a spare few million.
Read next: High-net-worth borrowers turn to shorter fixes as rate uncertainty persists
And that's also where the picture looks a bit more stable private indices, including Coutts', have shown early signs of demand holding up even as the ONS numbers for inner London keep sliding.
There's also a genuinely useful, time-limited point for anyone with clients near the £2m mark. The mansion tax confirmed in last year's Budget, officially the High Value Council Tax Surcharge will be based on 2026 property valuations, with the actual charges not hitting owners until April 2028.
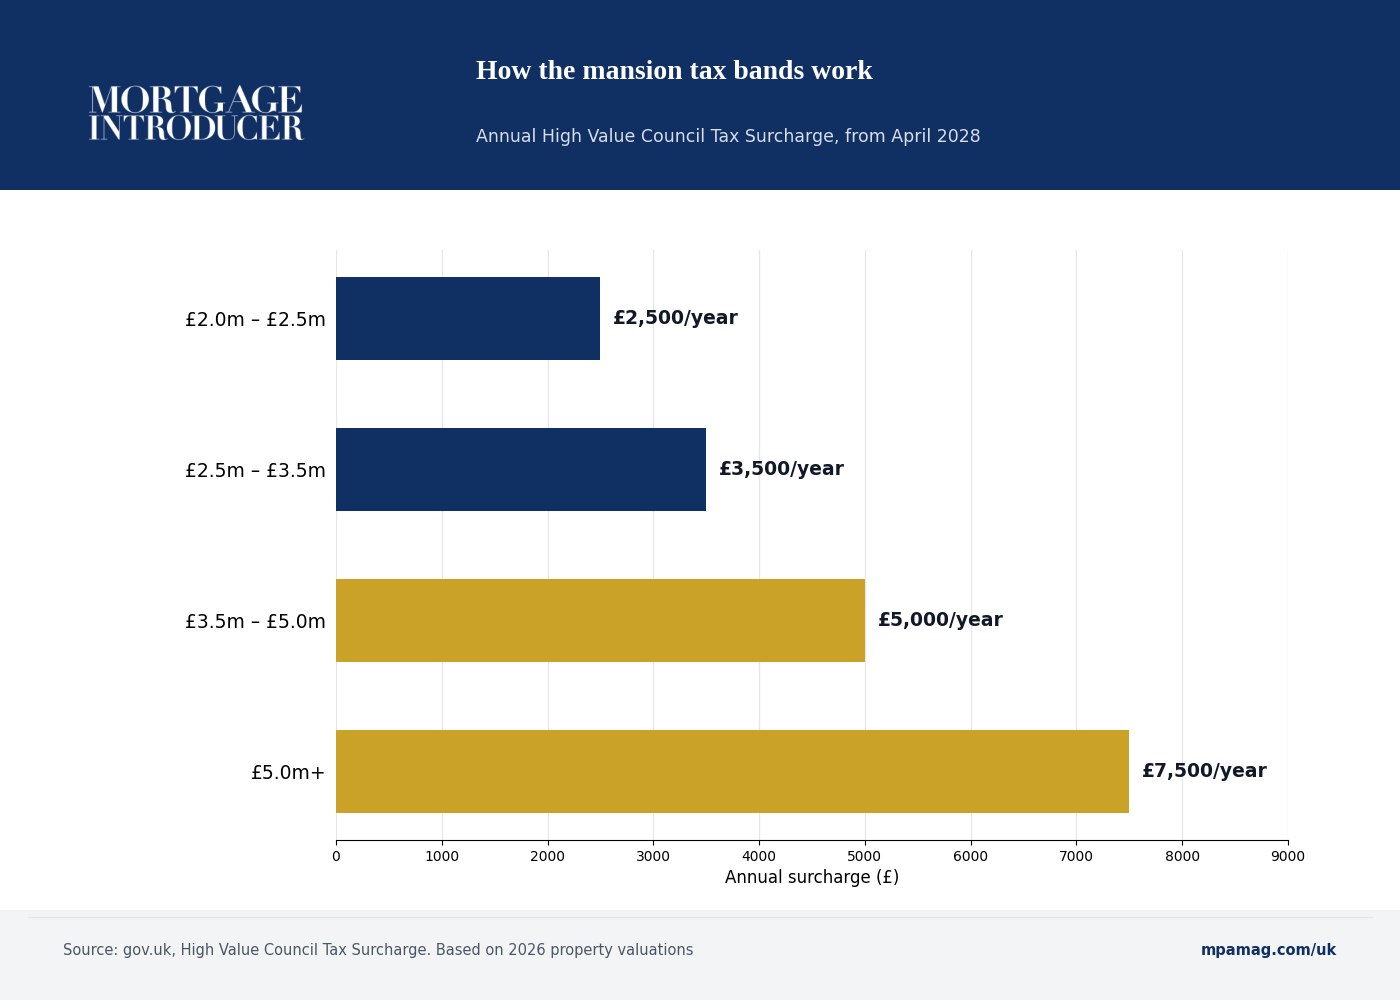
The bands run from £2,500 a year for a £2m–£2.5m home up to £7,500 for anything over £5m. So a property that's lost value this year could quite easily land in a cheaper band than it would have done twelve months ago.
If you've got a client hovering near a threshold, this year's valuation is one worth getting right and one worth revisiting if it's been sitting untouched for a while.
None of which means people should just wait and see. Aaron Jassi, a mortgage adviser at Chase de Vere who works mostly with high-net-worth clients, told Mortgage Introducer that buyers trying to time the market usually end up regretting it, because a good rate can vanish within a day.
The same goes in reverse here, hang around waiting for London's prime market to hit rock bottom, and you might miss both the bargain and the rate that made it worth buying. Some advisers say clients are dealing with the uncertainty by opting for shorter fixes or variable deals instead, giving enough flexibility to move if a good deal turns up, without locking into pricing that might not last.
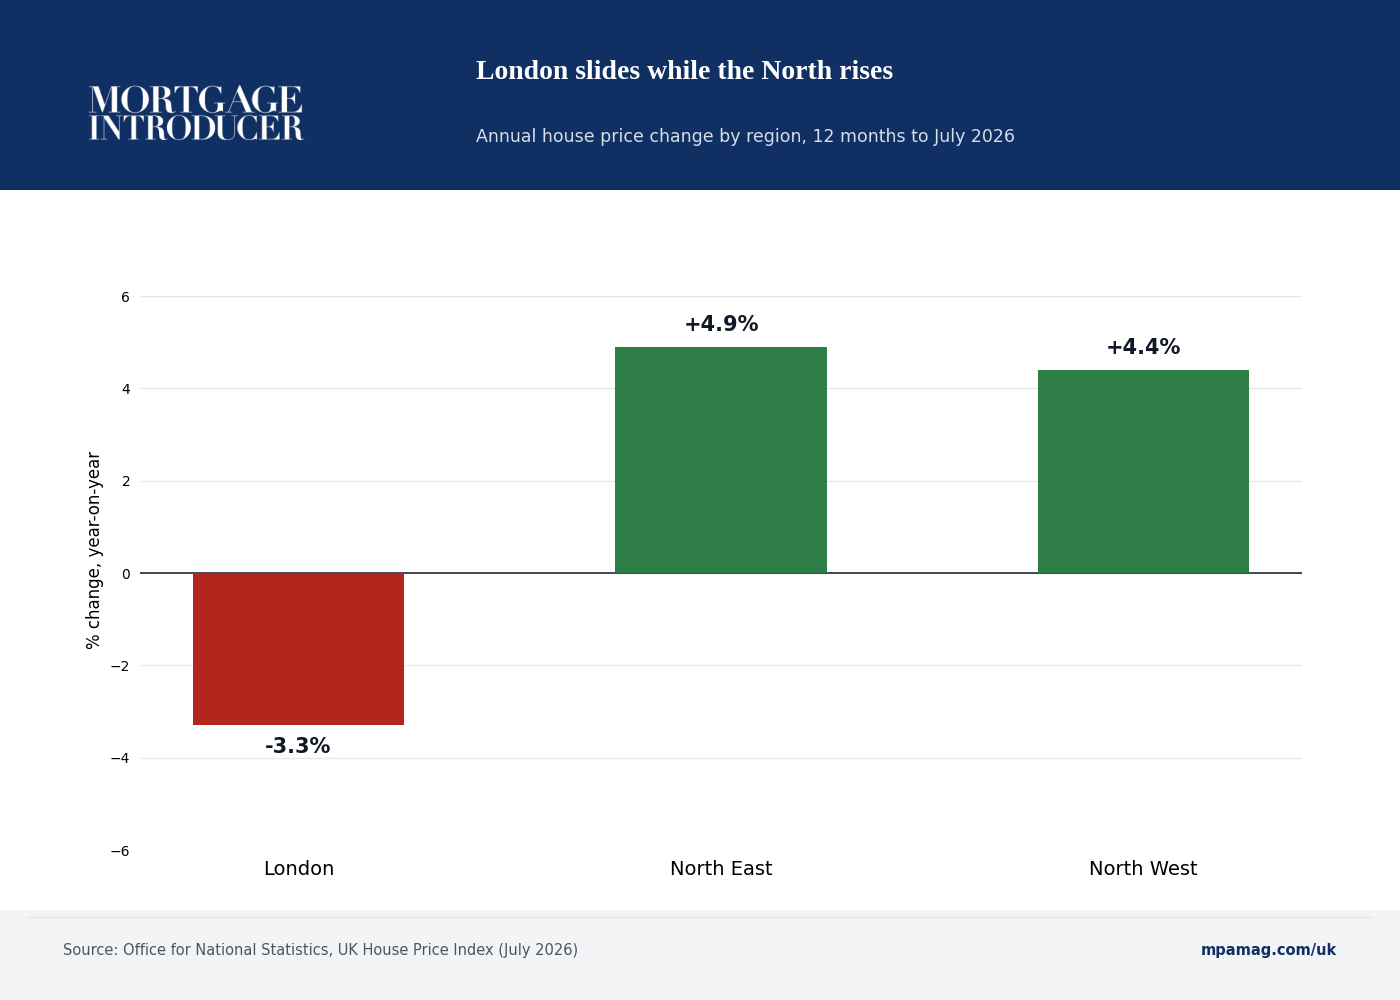
Meanwhile, up north, none of this gloom applies. House prices rose 4.9% in the North East and 4.4% in the North West over the same period, cheaper markets, less stamp duty drag, and mortgages doing far more of the heavy lifting than cash. If you've got clients or a pipeline outside the M25, that's arguably a better story than anything happening in Mayfair right now.
Read next: Landlord exodus accelerates across UK rental market
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.