Pegasus Group finds the London Plan's housing cuts of 300,000 homes risk £41bn annual economic loss and tighter mortgage conditions
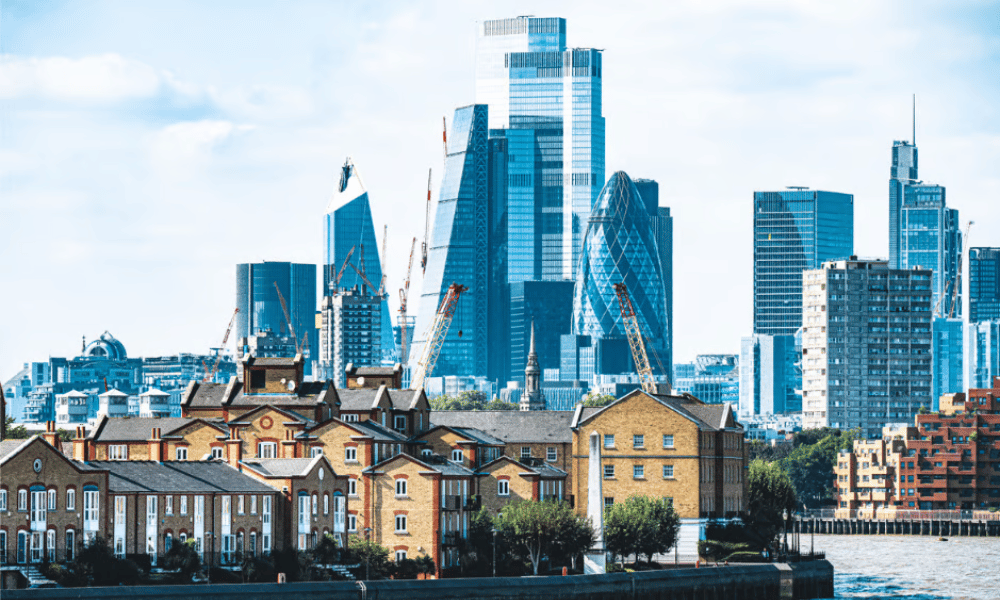
A proposal to cut London's housebuilding target by more than 300,000 homes could push house prices roughly 16% higher than they would otherwise be. That is the central finding of analysis published on 1 October 2026 by Pegasus Group, a multidisciplinary development consultancy.
The finding lands in the same week that national data showed housing starts in England rising 20% year-on-year. On closer inspection, that figure does little to resolve the structural gap the London Plan's housing cuts risk entrenching.
The draft London Plan, released for consultation in July 2026, sets a ten-year target of 558,000 homes. That's more than 300,000 short of the Government's own figure of 880,000.
Pegasus estimates the missing homes would have accommodated around 762,000 people, equivalent to the population of Leeds or Glasgow, with around 412,000 of them economically active. Those residents, and the income they generate, represent mortgage demand that will simply not materialise.
What do the London Plan's housing cuts mean for mortgage lending?
Pegasus calculates that the unbuilt construction phase could have generated £8bn of GVA per year — £80.6bn over the decade. That figure includes 25,400 direct jobs and 52,800 further supply chain roles.
For brokers, the more direct concern is price. Pegasus drew on Greater London Authority research, which found a 1% rise in housing stock produces a 2% fall in prices if nothing else changes. Applied to the shortfall, that relationship implies London prices roughly 15.8% above what they would otherwise be. In a market where first-time buyer affordability is already stretched, that premium erodes deposit-to-loan ratios across the residential book.
"Persistent supply shortages continue to place upward pressure on house prices and borrowing costs," said Chris Wheaton, senior director in the Economics team at Pegasus Group.
A rising starts figure is not the same as a solved supply problem
A Ministry of Housing, Communities and Local Government (MHCLG) release published 25 September 2026 showed new housing starts rising to 35,910 in Q2 2026 — up 20% year-on-year. But completions fell 3% quarter-on-quarter and planning approvals declined 12% to 212,000 for the year to June 2026. Net additional homes delivered across England in 2025–26 came to 196,900 — a 6% fall from the year before.
A starts bounce-back built on a shrinking approvals pipeline is a fragile base on which to absorb a deliberate decade-long target reduction in London.
Does scheme design widen or narrow the problem?
Property experts have warned that a new-build-only Your First Home scheme risks repeating the price-inflating dynamic of Help to Buy. Under that scheme, new-build prices rose 70.1% against a 65.6% increase in the wider market, according to HM Land Registry data. Opening the scheme to existing stock would widen qualifying purchases for brokers, but that decision will not be taken before the Autumn Budget on 28 October 2026.
Broader social costs sit behind the headline figures. London Councils reported in 2025 that one in 50 Londoners is in temporary accommodation, costing borough budgets £4m a day. Poor housing already costs the NHS over £100m annually in London.
Pegasus also found London residents relocating elsewhere in the UK rose 28% between 2014 and 2024. That shift is already visible in commuter-belt asking prices rising at twice London's own rate – a trend lenders should watch.
"At a time when economic growth is paramount, the economic and social price of failing to deliver sufficient housing is simply too high to ignore," Wheaton said.
The London Plan's housing cuts are a planning decision, but their consequences will be felt in the lending market. If 300,000 homes are never built, the mortgages to fund them are never written.