New-build equity loan plan could halve what first-time buyers need to save, but affordability and supply questions remain

Mortgage professionals have given a cautious welcome to Your First Home, a new equity loan scheme for first-time buyers in England announced by Prime Minister Andy Burnham on Saturday. They have also warned that its success will depend on detail yet to be published.
The scheme set out by the Ministry of Housing, Communities and Local Government (MHCLG) is expected to support 2.5% deposits backed by 20% government equity loans. It will be open to first-time buyers purchasing a new-build home from a developer signed up to the scheme. The loans will carry an initial interest-free period, and a household income cap and local property price caps will target support at those who need it most. Chancellor John Healey is due to confirm funding and timelines at the Budget on 28 October.
The announcement follows earlier calls for Burnham to take bold action on stamp duty and the cost of getting onto the housing ladder. Your First Home is separate from the existing First Homes scheme for first-time buyers in England, which offers discounts of 30% to 50% on a property's market value.
How much could Your First Home save first-time buyers?
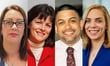
Nicholas Mendes (pictured top middle right), mortgage technical manager and head of marketing at John Charcol, worked through what buyers would need at different prices. At the average UK house price of £272,611, a buyer would need a deposit of £6,815 under the scheme, alongside a £54,522 equity loan and a £211,274 mortgage. On a £230,000 home, the Rightmove average for first-time buyers, the deposit would be £5,750. That compares with £11,500 at a standard 5% deposit.
"Your First Home is positive news for first-time buyers," Mendes said. "The deposit remains the single biggest barrier to getting onto the ladder and bringing it down to 2.5% will make a real difference to those who can afford the monthly repayments but have struggled to save while paying rent."
He added that the equity loan also changes the pricing available on the mortgage itself.
"Because the equity loan covers 20%, the mortgage itself sits at 77.5% loan-to-value, which gives buyers access to lower rates than they would typically see on a 95% mortgage."
Why brokers and trade bodies want more detail
Stephanie Charman (pictured top left), chief executive of the Association of Mortgage Intermediaries (AMI), welcomed the government's focus on first-time buyers but said lenders face practical work before the scheme can launch.
"The success of the scheme will depend on getting the detail right," she said. "A 2.5% deposit represents a change from the 5% minimum under the previous Help to Buy scheme and lenders will need to consider product design, systems and how these applications work in practice. Mortgage advisers will have an important role in helping consumers understand whether the scheme is right for them and, crucially, whether the borrowing remains affordable over the longer term."
Mendes also urged caution, pointing to the new-build restriction and the eventual repayment of the equity loan.
"Buyers will need to go in with their eyes open," he said. "The scheme is limited to newbuilds, which often come with a premium over comparable existing homes, and the equity loan will ultimately need to be repaid, so buyers need to be clear on the terms before committing."
Charman raised further questions over how the scheme will sit alongside existing tax thresholds and housing supply.
"We also need to understand how the property price caps will interact with existing first-time buyer stamp duty thresholds and whether sufficient suitable new-build homes will be available in the areas where buyers need them."
Mendes also called for more stamp duty support in London and the South East, where many new-build homes sit above the £300,000 first-time buyer threshold. He also wants a review of the Lifetime ISA, whose limits have not risen since 2017. Other brokers have argued that stamp duty reform for first-time buyers should come first under the new government.
Charman said the scheme's purpose must be kept in view.
"Your First Home should be a stepping stone into sustainable homeownership, not a sticking plaster for the wider challenges facing first-time buyers," she said. "Helping people overcome the deposit hurdle is positive, but affordability remains a challenge and we need to ensure there are enough suitable homes for them to buy."
Lenders prepare for delivery
Solange Chamberlain (pictured top right), chief executive of retail banking at NatWest Group, said the lender supported the scheme.
"We welcome the government's commitment to helping more people onto the property ladder and support the introduction of the new Your First Home scheme," she said. "Making home ownership more accessible can create opportunities for aspiring buyers, unlock housing market activity and support economic growth across the UK."
She said NatWest was ready to support delivery.
"Supporting first-time buyers has long been a priority for NatWest. As one of the UK's largest mortgage lenders, we already help thousands of customers buy their first home each year and stand ready to support the delivery of this scheme. Together, we can help more people realise their ambition of owning a home."
Mendes pointed to alternatives including Skipton's Track Record mortgage, Gable Mortgages' no-deposit lending for first-time buyers and Accord's £5k Deposit Mortgage. He said these mean a larger mortgage and a higher income to pass affordability.
"The right route will depend on the buyer's circumstances and the type of property they want, which is where speaking to a broker can make a real difference."
What Help to Buy lessons mean for Your First Home
The scheme draws comparisons with Help to Buy, introduced in 2013, offering equity loans of up to 20% on new-build homes to buyers with a 5% deposit.
Kate Davies (pictured top middle left), executive director of the Intermediary Mortgage Lenders Association (IMLA), pointed to the scale of the problem.
"We very much welcome the government's decision to introduce Your First Home," she said. "IMLA has been calling for targeted support for aspiring first-time buyers for some time. Our research estimates that around 3.5 million households who might historically have been expected to become first-time buyers have failed to do so since the financial crisis, so the scale of the challenge is considerable."
She said the familiarity of the equity loan model was an advantage but warned that limiting the scheme to new-build homes carried risks.
"Restricting support to new-build homes can help stimulate additional supply, but it also narrows the choice available to first-time buyers and risks concentrating the benefits among developers. The design of the scheme therefore needs to ensure that support delivers genuine value for buyers as well as encouraging the building of much-needed new homes."
Davies said the Budget detail would decide whether the scheme delivers for buyers and builders alike.
"The full details will clearly be important, but this is a very encouraging start. If Your First Home helps responsible borrowers overcome the deposit hurdle while giving developers greater confidence to build, it can support not only aspiring homeowners but the housing market and wider economy."
Let us know what you think of the Your First Home scheme in our latest LinkedIn poll.
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.