Younger investors and intergenerational wealth are driving new appetite for houses in multiple occupation and multi-unit freehold block finance

Sharia-compliant buy-to-let finance is growing fast, and the range of investors seeking it has broadened considerably alongside the products now available to them.
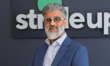
Rizwan Ali (pictured top), director of sales and marketing at StrideUp, a London-based Islamic home finance provider, says demand for specialist products including houses in multiple occupation (HMOs) and multi-unit freehold blocks (MUFBs) has risen considerably over the past four to five years. That growth has been driven by a younger generation with stronger values-led financial preferences and by a generational transfer of wealth within established landlord families.
"The appetite for Sharia-compliant buy-to-let finance and specialist buy-to-lets – HMOs and MUFBs – has increased quite significantly," Ali told Mortgage Introducer. "The community generally is quite interested in investing in assets. It's a very common theme."
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
A generational shift in values
Ali points to three interlocking forces behind the growth. The first is a long-standing cultural inclination within Muslim communities towards property investment as a vehicle for intergenerational wealth. The second is a broader generational shift in attitudes towards ethical finance. He cited a 2023 Deloitte survey which, he said, found that 44% of UK millennials and Gen Z prefer values-driven or ethical financial products – a trend he believes runs higher still within Muslim communities, where StrideUp's own research suggests the figure could be as high as 70%.
The third driver is the intergenerational transfer of wealth now under way within established landlord families. Ali described clients he has known for 15 to 20 years whose adult children are increasingly taking control of family portfolios, and in some cases making Sharia compliance a condition of that transition.
"It's not uncommon for me to hear, 'My children are saying they don't really want to have anything to do with this unless I transfer everything over to a Sharia-compliant platform,'" he said.
This dynamic is accelerating demand not just for standard buy-to-let but for the more complex end of the specialist market. Second and third-generation investors, he said, are pushing into HMOs, MUFBs, and increasingly into commercial property finance – areas where Sharia-compliant products have, until recently, barely existed.
What does growing product availability mean for borrowers?
Throughout most of the Islamic finance sector's history in the UK, the owner-occupied market was where product development was concentrated. Specialist buy-to-let – and in particular HMOs and MUFBs – was a gap in the market. That is changing, and Ali credits product availability as one of the key catalysts now accelerating take-up in the UK specialist buy-to-let market.
StrideUp currently offers finance on properties up to 12-bed HMOs and 10-unit MUFBs, lends up to £2.5 million on a single property, accepts first-time landlords, and carries no minimum income requirement. The lender has grown its book from approximately £40–50 million when Ali joined just under three years ago to close to £700 million today. It completed a securitisation in 2025 – the Meridian Fund, a £230 million transaction – which won a Global Capital award for best securitisation deal of the year, a signal that institutional capital markets are taking the asset class seriously.
"The legacy issues – restrictive criteria, conveyancing being largely messy, double stamp duty – these are like 15-year-old concerns," Ali said. "They've been dealt with."
Part of StrideUp's edge has been its early investment in a digital experience at a time when much of the Islamic finance sector still relied on paper applications and wet signatures – a gap that the Covid-19 pandemic's broader digitalisation push helped close.
Critically, the product is not exclusively for Muslim borrowers, with some clients referred to StrideUp by brokers precisely because its criteria suit cases that conventional lenders cannot accommodate. The absence of a minimum income requirement, the acceptance of first-time landlords, and the willingness to lend on larger HMOs and MUFBs make StrideUp a viable option for borrowers with no particular interest in Sharia compliance.
"A lot of people say to us, 'I thought it was just for Muslims'," he said. "But the product itself, the characteristics, the criteria, it's there for everyone. We would absolutely want everyone to partake in this, irrespective of what faith they are, or even if they're of no faith. It makes absolutely no difference to us.
"We do get business from customers who are not of the Muslim faith, and we're able to help them too."
How is the Renters' Rights Act affecting Sharia-compliant landlords?
The Renters' Rights Act, which came into effect in May, has introduced significant changes to the private rented sector, generating considerable debate about its likely impact on buy-to-let volumes and landlord appetite. Among StrideUp's Sharia-compliant borrowers, Ali says the picture so far is one of continuity rather than disruption, but he is cautious about reading too much into early data.
"The effect on us has not been massively apparent at the moment," he said. "But I would say that with a touch of reservation, in the sense that it's only very recent. When we have a little bit more data on this – because generally there's not much data about Sharia-compliant buy-to-let – we need to look at this over the course of time."
The broader trajectory remains intact. Ali believes 25% to 30% of StrideUp's business being buy-to-let is a plausible and sustainable medium-term target. StrideUp's 2025 securitisation was not just a financing milestone, it was evidence, he argues, that this market has moved well beyond its niche origins.
"The closer we get to the pricing available in the conventional market, the more the growth is going to be expedited."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.