Floating falls out of favour as borrowers lock in ahead of hikes

Mortgage advisers say borrowers rolling off fixed rates in October are steering clear of floating, but they are divided on how long to lock in as the official cash rate (OCR) rises.
The Reserve Bank (RBNZ) lifted the OCR to 2.75% in September, and about 64% of mortgages are due to reprice within 12 months, according to the New Zealand Institute of Economic Research. With 62.2% of loans on fixed rates in the six months to June, according to New Zealand Banking Association figures, most of those borrowers face a refix decision.
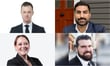
Advisers’ own books show how uneven that exposure is. Cameron Muggeridge (pictured upper left), partner and mortgage adviser at Loan Market in Auckland, estimates about 80% of his clients have rates up for review within a year, while Nathan Miglani (pictured upper right), managing adviser for Christchurch and the South Island at Squirrel, puts it at around 65%.
Laura te Kaat (pictured lower left), mobile mortgage adviser at The Mortgage Girls, has only 16% refixing, which she said reflects how popular longer terms have been over the past year. Andrew Perry (pictured lower right), mortgage broker at Mortgage Market, said most of his renewing clients are coming off rates near 4.5% and moving above 5%.
Floating loses its appeal
Perry said the return of inflationary pressure has made clients keen to fix early rather than bet on rate cuts.
“I’m not seeing any clients waiting to fix and sitting on floating rates,” he said.
Miglani noted floating rates of around 6.5% cost well above shorter fixed terms.
Muggeridge said the usual gap of about one percentage point means rates would need to fall sharply, and soon, to justify floating.
Short terms or long?
Perry has seen more appetite for longer terms, as some lenders show almost no difference between three- and five-year rates.
Miglani’s clients are going the other way. A typical borrower with $450,000 to $600,000 might refix part of the loan at 4.99% for one year and the rest at 5.29% for two.
“Hardly anyone is fixing for longer than two years,” he said.
Muggeridge said more than 95% of his clients already split their lending, and he sees longer-term rates as less attractive given the gap with shorter terms.
Te Kaat uses a break-even calculator to show clients how high rates would need to climb before a shorter term stops paying off. Some of her clients are going further, refinancing early to secure a rate and cashback where break fees are low or nil.
Stress tied to job losses, not rates
None of the advisers reported widespread repayment stress.
Miglani said borrowers had adjusted well, helped partly by wage growth, and he had seen no significant rise in hardship requests. Perry and Muggeridge both pointed to job losses as the main trigger, with Perry also citing separations and noting that lost equity makes it harder for affected households to move on.
When problems do arise, Muggeridge said lenders have improved their hardship processes since COVID-19.
“The banks are very well equipped to handle these hardship requests,” he said.
The country’s four largest banks would also keep lending even if unemployment hit 10.5%, according to the first joint trans-Tasman stress test in almost a decade.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.