Lending to households continued despite modelled recession, oil shock, and cyber-attack

New Zealand’s four largest banks would stay above their minimum capital requirements and keep lending even if house prices fell 35% and unemployment hit 10.5%, according to results from the first joint stress test run by New Zealand and Australian regulators in almost a decade.
The Reserve Bank of New Zealand (RBNZ) and the Australian Prudential Regulation Authority (APRA) released headline results from the 2026 Trans-Tasman Stress Test. The test covered ANZ Bank New Zealand, ASB Bank, BNZ, and Westpac New Zealand, which together account for 84% of bank lending in New Zealand, alongside their Australian parent banks.
The RBNZ has published detailed results for New Zealand banks, while APRA will release its Australian findings later in 2026.
Both regulators concluded their banking systems would remain resilient, although banks would take heavy losses and come under strain on capital and liquidity. The RBNZ warned that banks’ capital buffers would be significantly depleted.
A severe scenario for borrowers
The hypothetical scenario combined an escalation in regional geopolitical tensions, a sharp spike in oil prices, and a deep recession in both economies. It also included a three-notch credit rating downgrade and higher bank funding costs, along with a disruption to market funding and a cyber incident affecting an offshore banking operation. The house price and unemployment assumptions were deliberately harsher than the RBNZ’s expected economic outlook.
Loan losses did most of the damage. As more households and businesses struggled to repay, banks’ annual impairment expenses rose from a baseline of $0.3 billion to $6.2 billion in the first year and peaked at $7.2 billion in the second. The core capital ratio of the four banks fell 4.7 percentage points to a low of 8.5% in the third year, before mitigating actions, still well above the 4.5% minimum.
To rebuild capital, banks identified steps including repricing, credit measures, cost savings, and capital injections from their parents.
Why a joint test matters for New Zealand
The exercise reflects how closely the two banking systems are tied. New Zealand’s four largest banks are all owned by Australia’s major banks, and both systems are heavily exposed to residential property markets.
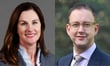
“That interconnection means a banking crisis in one country could well cause serious impacts on the other side of the Tasman,” said APRA deputy chair Therese McCarthy Hockey (pictured left).
The RBNZ’s findings show why that link matters. It found that support from Australian parent banks could not be guaranteed if both countries were under severe stress. The central bank said new loss-absorbing capital instruments introduced through its 2025 Capital Review should make that support more reliable.
More joint tests on the cards
Angus McGregor (pictured right), the RBNZ’s assistant governor for financial stability, said the two regulators would consider running trans-Tasman stress tests more often.
“Feedback from participating banks indicated that the joint approach reduced regulatory burden and supported stronger engagement between Australian parent banks and their New Zealand subsidiaries,” McGregor said.
The RBNZ is now developing recommendations to help the banks strengthen their risk management and preparedness for future stress.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.