Hardship cases drop 9.7%, while most borrowers stay on fixed rates

The average first-home buyer loan in New Zealand fell 3.4% to $506,761 in the six months to June 2026. Over that period, first-home buyers accounted for 22.4% of the 72,209 new home loans opened, according to retail banking insights released by the New Zealand Banking Association (NZBA).
House prices have continued to soften since: the national median eased 2.3% year on year to $755,000 in September 2026, according to the latest Real Estate Institute of New Zealand (REINZ) data, and Westpac now expects national values to fall 1.4% in 2026.
Fixed rates dominate as hardship eases
Fixed-rate lending remains the norm. Of all loans, 62.2% were on fixed rates, 16.3% were on variable rates, and the remaining 21.5% combined fixed and variable portions.
There were signs of easing financial stress. The number of customers granted hardship status dropped 9.7% on the prior half, to 5,562, and most credit cards (68%) were paid off in full, avoiding interest costs.
Those figures predate the start of a new tightening cycle: the Reserve Bank (RBNZ) has since lifted the official cash rate (OCR) to 2.75% in September, its second increase since tightening resumed in July.
Deposit balances moved in different directions. Total savings account balances declined 1.3% to $112.8 billion, an average of $16,879 per account. Term deposits rose 0.4% to $195.7 billion, with an average balance of $111,030.
Cash use keeps shrinking
The data, covering January to June, also shows New Zealanders moving further away from cash.
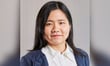
NZBA chief executive Roger Beaumont (pictured) said the long-term direction was clear, with cash declining while “the shift to digital payments and online and mobile banking grows”.
ATM transactions made up 1.6% of the 2.2 billion customer transactions recorded, down from 1.7% in the prior half. Cash transactions in branches dropped 11.5%, from 2.1 million to 1.9 million, and accounted for 2.5% of all branch transactions, down from 2.7%. Meanwhile, active internet and mobile banking users rose 2.4% to 6.2 million, just over 74% of the industry’s 10.18 million unique customers.
Beaumont stressed that cash still has a role: “That’s not to say cash is on the way out.”
He said some customers continue to rely on it for reasons such as budgeting, gifting, cultural practices, and fundraising, and that cash now represents only a small share of all banking activity.
“The decline in cash use is incremental,” he said.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.