COSBOA warns the trust tax overhaul's exit penalty could punish small family businesses navigating a wider tax shake-up

The Council of Small Business Organisations Australia (COSBOA) has ramped up its opposition to the federal government's proposed 30% minimum tax on discretionary trusts, warning that a 47% penalty rate attached to the measure will "unnecessarily punish small family businesses" that later need to exit the arrangement.
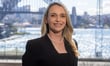
COSBOA chief executive Skye Cappuccio (pictured) said the exposure draft legislation "remains bad policy that will hurt small business”, specifically targeting a clause that would tax a discretionary trust at the top marginal rate, with family members who receive a distribution also facing the Medicare levy on top.
How discretionary trusts are taxed now
Right now, a discretionary trust itself generally pays no tax at the trustee level. Instead, income is distributed to beneficiaries, who are taxed at their own individual marginal rates.
That structure allows "income splitting": a trustee can direct income toward family members on lower personal tax rates rather than concentrating it all with the highest earner, reducing the household's overall tax bill and, in turn, the overall tax take.
There's no minimum tax rate currently attached to trust distributions – which is what the government wants to change.
What the government is proposing
At the May Budget, Labor announced a flat 30% minimum tax on discretionary trust distributions. Facing industry pushback, the government made a concession earlier this month: existing discretionary trusts can elect, on a one-off basis, to nominate fixed beneficiaries who retain the current tax treatment.
Once a trust makes the fixed-distribution election, it's largely locked in. If a trustee breaches the election by distributing differently than agreed, the trust loses the benefit – and is hit with the top marginal tax rate (up to 47%) plus the Medicare levy for that year.
Why the fix falls short
While the concession Labor made was welcome, Cappuccio argues it has left a lot to be desired.
"Family businesses evolve," she said. "A son or daughter might come home and start working in the business... These are normal decisions for a family business." She argued there is no need to impose the higher exit rate when a simpler alternative – moving straight to the 30% minimum tax – is already available.
"If making one of those changes means losing access to the elected arrangement, why should that business then be taxed at the highest marginal rate for that year?" Cappuccio said. "There is a straightforward alternative. Let the business move to the government's proposed 30 per cent minimum tax. There is no need to impose a higher rate for that year.
"The government's underlying 30 per cent minimum tax remains bad policy. But if it intends to proceed, it should not make a bad policy worse by punishing small family businesses simply because their circumstances change."
The minimum tax measure is one part of a broader reshaping of investment and business taxation flagged in the May Budget, alongside changes to negative gearing and the capital gains tax (CGT) discount.
Negative gearing benefits are being preserved for existing properties but tightened for future purchases, while the 50% CGT discount is being replaced with cost-base indexation combined with a 30% minimum tax on net capital gains – together representing the most significant shake-up of investment property taxation in a generation.
Part of a running fight
This isn't COSBOA's first objection to Labor's controversial tax overhaul.
When the government softened a related measure in June by lifting the small business CGT concession turnover threshold fivefold, from $2 million to $10 million, Cappuccio argued that the stakes went beyond dollar figures.
"What we are hearing very clearly from small businesses is that this is not just a conversation about tax," Cappuccio said at the time. "It is about whether Australia still encourages people to back themselves and build something over the long term."
Broking industry bodies have raised similar concerns about the wider package since the Budget was handed down in May. Brokerages are themselves small businesses, and many operate through discretionary trust structures for the same succession-planning and asset-protection reasons COSBOA cites.
Commercial and Asset Finance Brokers Association (CAFBA) chief executive David Bushby said he was "deeply concerned that these complex new rules and valuation requirements will adversely impact our members and their commercial clients, leading to unintended consequences and possibly encouraging avoidance behaviour in the market”.
Outgoing Finance Brokers Association of Australia (FBAA) chief Peter White raised a similar concern earlier in the Budget process, cautioning that reform aimed at improving housing access could end up hurting the people it was meant to help.
"While I commend the government for wanting to open up more housing, these changes will disadvantage the very people it seeks to help – younger Australians, as well as many other people on lower incomes," White said.
The window for change is narrowing.
Treasury's consultation on the exposure draft legislation closes on 18 September – this Friday – after which the government moves toward finalising the bill for introduction to Parliament.