Is AML clarity finally in sight for commercial brokers?

The Finance Brokers Association of Australia (FBAA) has welcomed a significant step towards regulatory certainty for commercial and asset finance brokers, after the Australian Transaction Reports and Analysis Centre (AUSTRAC) indicated that ordinary commercial broking activities are generally not intended to fall within the scope of Australia's expanded anti-money laundering and counter-terrorism financing (AML/CTF) obligations.
The development follows months of advocacy by the FBAA and other industry bodies to resolve ambiguity in the original Tranche 2 AML/CTF guidance that left brokers uncertain about their compliance obligations.
Why brokers were worried
Australia's Tranche 2 AML/CTF reforms extend anti-money laundering obligations beyond banks and financial institutions to include professional service providers such as lawyers, accountants, real estate agents, and businesses involved in corporate finance and capital raising.
When guidance was first published, however, a provision under item 4 of table 6 – covering entities that assist in organising, planning, or executing debt or equity financing for a company or legal arrangement – was worded broadly enough to potentially capture standard commercial finance broking activities.
For many commercial and asset finance brokers, the concern was critical. If broking activities were found to fall within scope, they would potentially be required to enrol separately with AUSTRAC, establish standalone AML/CTF compliance programs, train staff in anti-money laundering procedures, and monitor and report suspicious transactions.
In July 2026, the Mortgage & Finance Association of Australia (MFAA) and the Commercial & Asset Finance Brokers Association of Australia (CAFBA) jointly wrote to the Australian Government and AUSTRAC seeking formal confirmation that standard commercial broking was not the intended target of the reforms.
AUSTRAC acknowledged the concern but stopped short of providing a definitive ruling, noting it would address the matter through future guidance. The FBAA separately contacted AUSTRAC and received a letter dated 21 July 2026 advising that brokers need not begin working towards compliance on this question until AUSTRAC had published its position.
What AUSTRAC's clarification means in practice
AUSTRAC has now indicated that brokers arranging commercial and asset finance for ordinary business purposes, including equipment purchases and working capital, would generally not be required to enrol separately with AUSTRAC or establish standalone AML/CTF programs solely for those activities.
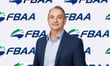
FBAA chief executive officer Leo Gagic (pictured) said the regulator had listened to the industry's concerns. "The original guidance left some uncertainty around whether commercial and asset finance brokers could face significant compliance obligations that were never intended to apply to their businesses," Gagic said.
"Based on its latest response, it's clear that AUSTRAC has listened to our concerns and worked through the issue. Their latest clarification gives us confidence that we're moving towards formal confirmation that ordinary commercial and asset finance broking activities are not required to address these additional requirements."
Brokers should still wait and see
Brokers involved in broader corporate financing transactions, including capital raising and business acquisitions, may still attract AML/CTF obligations and should seek specific advice on their circumstances. However, they assured continued support for lenders in meeting their own AML/CTF obligations through existing lender relationships and processes.
MFAA has published practical guidance for members covering the current regulatory position, AUSTRAC's expectations, and recommended steps, including documenting the basis for any position adopted, retaining supporting records, and reviewing that position as additional guidance is released. Brokers unsure about their specific obligations should consult their association or seek professional legal advice.
Gagic welcomes the regulator's willingness to address its concerns. "Strong anti-money laundering protections are essential, but regulation needs to be clear about who it applies to and what businesses must do," he said. "We'll continue working with AUSTRAC until the position is formally confirmed and brokers have the clarity they need."
The clarification is not yet final. Formal guidance from AUSTRAC is expected to follow as the regulator completes its review, but FBAA is committed to updating members as soon as further information is available.