Some buyers trade higher climate risk for cheaper entry, analysis finds
Wairoa has the highest share of homes facing elevated flood risk in New Zealand, but Christchurch has the largest number of exposed properties, according to new Cotality analysis.
Cotality gave each property a relative flood risk score from 0 (low) to 5 (high), combining river, surface-water, and coastal flooding. It used New Zealand FloodMap, a model from engineering consultancy Haskoning that major insurers and financial institutions already use. The scores are relative: a zero is not a guarantee of safety, and a five is not a forecast of flooding.
Two-thirds (66%) of Wairoa properties scored between 3 and 5. Buller followed at 61%, then Napier at 56%, Gore at 50%, and Westland at 43%. Much of the country sits at the other end of the scale: in 14 of the 72 areas analysed, at least 90% of properties scored 0 or 1.
A growing factor in lending and insurance
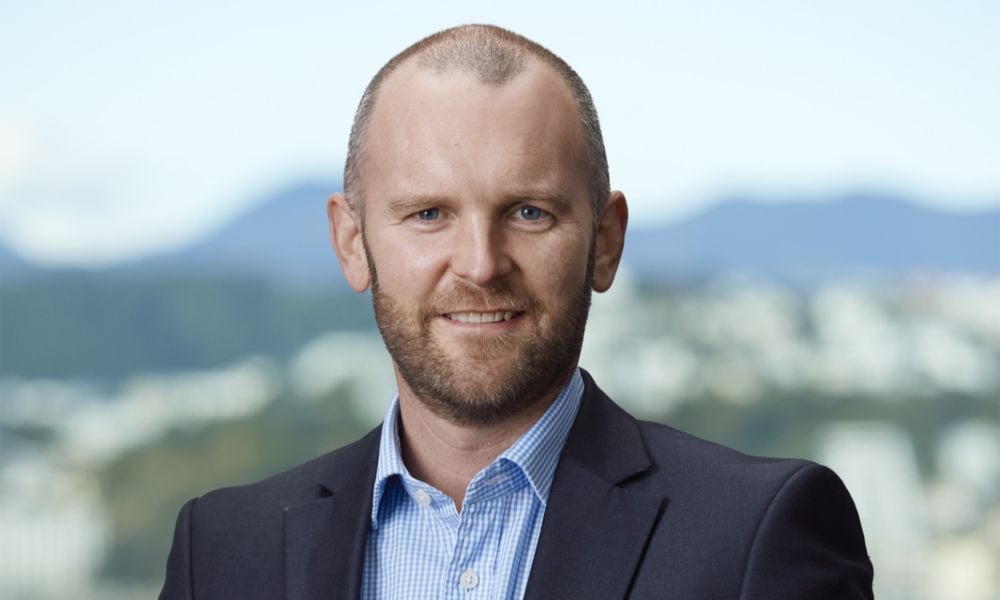
Kelvin Davidson (pictured), Cotality’s chief property economist, said: “Flood risk is increasingly becoming a housing market issue, not just an environmental one.” He said it had implications for property values, insurance, lending decisions, and household wealth.
In a worst case, some owners could be left with a damaged home that is effectively uninsurable and unsellable, yet possibly still paying off a mortgage. For higher-risk regions, the report warned: “Mortgages and insurance may be available and ‘affordable’ now, but there’s a higher risk that this won’t be the same in future.”
That shift is already under way. Property insurers are increasingly pricing risk at the individual-property level, the Reserve Bank of New Zealand (RBNZ) said in its November 2026 Financial Stability Report, describing climate adaptation and insurance affordability as important challenges.
In Buller, Cotality’s second-highest-risk district, availability has already been tested. Since early 2026, AA Insurance has paused new home, business, and landlord policies in the postcode covering Westport, citing flood risk, though existing policies remain in force.
Big cities carry the bigger exposure
The most exposed districts are, however, small housing markets. Wairoa, Buller, Gore, and Westland together make up just 0.9% of the properties analysed, and Napier another 1.4%.
Count homes rather than shares, and the picture changes. Christchurch has around 24,000 properties scoring 3 to 5. Napier has about 13,900, Auckland City about 11,300, and Lower Hutt about 10,400.
According to Davidson, these larger markets may have lower concentrations of exposure, but because of their size “they represent a potentially greater exposure for the broader financial system.”.
Cotality said the findings were consistent with earlier RBNZ analysis identifying Hawke’s Bay, Wellington, and Canterbury as areas to monitor closely. Cotality argued Auckland also warrants close attention, given the size of its housing stock and its experience during Cyclone Gabrielle.
Buyers weigh risk against price
Cotality’s earlier research on Cyclone Gabrielle found that flood-affected and flood-prone homes generally sell at a discount, but their values have since grown slightly faster. That suggests some buyers will accept more hazard in return for a cheaper way into the market.
Davidson said affordability remained a strong driver of buyer behaviour, but that no property was entirely free of climate risk. He said owners should understand the risks tied to their location, because “over time those risks may increasingly affect insurance costs or availability, financing and property values”.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.