Borrowers urged to set a strategy as wholesale rates climb
New Zealand borrowers face rising mortgage rates over the coming months. ASB now expects the Reserve Bank of New Zealand (RBNZ) to lift the official cash rate (OCR) three more times, and says fixed mortgage rates have already passed their lows for this cycle.
ASB economists said they expect a 25-basis-point hike to 3% on 28 October, followed by further increases in December and February, taking the OCR to a peak of 3.5%. It isn’t alone: most major banks now expect a hike on 28 October, with Kiwibank the outlier.
Inflation drives a higher peak
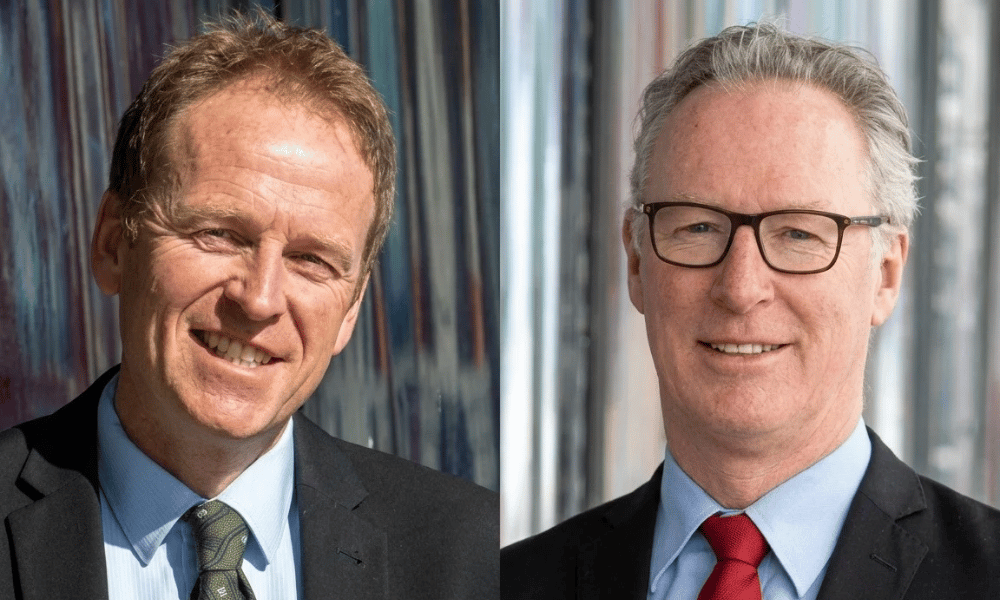
ASB senior economist Mark Smith (pictured left) said the case for an October move was strong. He pointed to a weaker New Zealand dollar, higher oil prices, and an inflation outlook that has worsened since September. ASB now expects annual inflation to reach 4.7% by the end of 2026 and to stay above 3% until the end of 2027.
The bank has also raised its estimate of the neutral OCR, the level at which policy is neither loose nor tight, to 3.5%. That means more tightening simply to bring settings back to normal.
“It is relatively easy to forecast 2% inflation, but it is much harder to deliver it,” Smith wrote.
He acknowledged the cost to the economy.
“The timing is unfortunate,” he wrote, warning that further hikes during a large cost shock could slow the labour market recovery.
Fixed rates past their lows
ASB senior economist Chris Tennent-Brown (pictured right) said that, despite competing pressures, “mortgage rates are expected to go up, not down”.
ASB’s carded rates show floating at 6.29%, while fixed rates range from 4.79% for six months to 5.75% for five years. The one-year rate is about 2.5 percentage points below its 2023 peak, but every term has risen from its 2025–26 low. Wholesale rates have moved faster than retail pricing: the two-year swap rate is about 40 basis points higher since September.
That fits with what lenders did after the September hike, when banks raised floating rates in full but moved fixed rates less consistently, according to the Real Estate Institute of New Zealand. Even so, the average rate households are actually paying, at around 4.8%, remains close to its 2026 low.
A strategy, not just the lowest rate
Tennent-Brown said borrowers should weigh flexibility, repayment timeframes, and the cost of floating against fixing, rather than simply chasing the cheapest rate. Floating is relatively expensive, while longer fixed terms offer certainty at a higher cost. He also noted that loan-to-value restrictions can affect credit availability and borrowing costs, and that debt-to-income limits are now in place.
For more information, read ASB’s Economic Note and Home Loan Rate Report.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.