Why Krishna wants clearer, more consistent lending rules

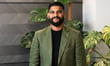
Manshil Krishna (pictured), a mortgage adviser and director of Benchmark Mortgages in Auckland, says some of his most valuable conversations with clients have involved two words: "Not yet." It's a lesson the former banker says he learned while building his own advisory business.
Building trust through honest answers
Krishna launched Benchmark Mortgages in 2023 at a time when rates were rising, servicing criteria were tight, and property market confidence was low. With no large franchise or automatic referral network behind it, the business grew mainly through word of mouth.
He was named one of NZ Adviser's Top 25 Brokers in 2024 and 2025, and a Top Broker in 2026.
Krishna said clients do not expect guarantees. They expect honesty, clarity, and a plan. In practice, "Not yet" might mean reducing debt, improving account conduct, building a larger deposit, or waiting until their income can be properly evidenced.
"Our job is not to manufacture a yes," he said.
From banker to mortgage adviser
Krishna came to advice from the other side of the table. He entered banking in 2010 and worked across ANZ, BNZ, and Westpac in New Zealand and Australia, in roles spanning retail, business, private, and commercial banking. That experience showed him the gap between how borrowers see their applications and how credit teams read them.
He said he had not fallen out of love with banking. He left because he wanted "the ability to finish the job properly for the client." Inside a bank, even the hardest work is limited by one institution's policy, products, and appetite. As an adviser, he can begin with the client's goals and then match the strategy and lender to them.
Why an approval is not a lending strategy
Krishna believes the industry is moving beyond judging success by approval alone.
"An approval is not a lending strategy," he said.
A loan can be approved and still be poorly structured, costly, or restrictive when a client wants to make their next move. Structure, he said, affects cash flow, flexibility, risk, and future borrowing capacity well beyond any introductory rate.
Getting the structure right starts before a lender sees the file. More clients now speak to advisers before they apply, rather than only after a bank declines them. Existing liabilities, unused credit limits, account conduct, and how income is evidenced can all materially change how an application is assessed.
The case for consistent lending policy
Krishna sees inconsistency across lenders as one of the industry's biggest challenges. Each lender has its own policy, servicing methodology, documentation requirements, and interpretation of risk. As a result, strong applications can be delayed or assessed differently depending on the lender or channel. At the same time, advisers must gather more information and document why their recommendations are suitable.
Krishna wants the existing bar met more efficiently and consistently, not lowered. That means clearer lending policy, more standardised documentation, and specific feedback from lenders when an application cannot be supported.
Consistency matters inside the adviser industry too. He would like stronger mentoring for new advisers, with training focused on credit analysis and loan structuring rather than products and sales.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.