Getting clients bank ready up to a year early

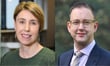
Shifting lending rules are keeping would-be New Zealand borrowers out of the market, according to Loan Market senior mortgage adviser Becs McCallum (pictured). She says many assume they’ve been shut out without checking where they stand.
McCallum, whose business trades as Loan Market McCallum & Co., has been named in NZ Adviser’s client-rated Top 25 Brokers for 2025, its top mortgage brokers for 2026, and the volume-based Top Advisers 2026 ranking.
She points to a mix of debt-to-income (DTI) rules, the test rates banks use to check whether borrowers can afford repayments, and changing lender appetite.
“The biggest friction right now is just how rapidly the goalposts keep moving,” she said.
The result, McCallum says, is a group of everyday borrowers who have stopped engaging altogether, even as the Reserve Bank reviews its lending restrictions annually.
“A lot of people are sitting on their hands right now assuming they can’t do anything, simply because the old rules they knew don’t apply anymore,” she said.
Getting borrowers bank ready early
McCallum’s answer is to start the conversation well before a client has found a property. Her team works with clients three to 12 months ahead of when they need finance, so borrowing capacity is clear before a deadline adds pressure.
The aim is clarity rather than complexity. In her words: “It’s about stripping back the noise, showing them what the banks are actually looking at today, and giving them a clear path forward.”
She argues that early education eases anxiety and improves results, and that leaving it until a client is under time pressure works against them.
Translating the borrower’s story
McCallum’s grasp of how banks assess borrowers comes from more than a decade in retail and corporate banking, starting in 2001. She moved to broking with Loan Market in 2013, trading a single bank’s answer for more than 30 options.
That insight matters most for borrowers who don’t fit a standard credit profile. One case stands out: a self-employed couple turned down by several main banks despite solid financials, because their structure didn’t fit the banks’ standard criteria.
The fix was presenting their position in terms a credit team could assess. As McCallum put it: “We pushed, re-framed the risk, worked directly with the right decision makers, and got it across the line unconditionally.”
Her takeaway is that a first decline often reflects how an application was presented, not the borrower’s true position.
From rate finders to long-term partners
McCallum says the adviser’s role has changed. Clients now call at life’s turning points, not only when they’re buying, and she says banks increasingly see adviser-led clients as better prepared.
That long-term view shapes her advice to newcomers: invest in systems and people rather than doing everything alone, and think in decades rather than deals.
“If you treat every client like a 20-year relationship rather than a single transaction, you’ll never have to worry about where your next piece of business is coming from,” she said.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.