The one-time niche product is seeing its popularity climb. Industry executives explained why, and what brokers and their clients need to keep in mind

The popularity of reverse mortgages has soared in Canada in recent years, and that momentum doesn’t appear to be slowing anytime soon.
Once viewed as a niche product, its uptake is increasing as a way for older homeowners to tap into home equity while remaining in place – and while it’s not a solution that should be offered without a careful appraisal of each borrower’s individual situation, industry members say its appeal is only spreading.
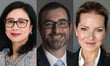
Pierre Martin (pictured, top centre), senior vice president of broker channel at HomeEquity Bank (HEB), told Canadian Mortgage Professional an evolution has taken place in recent years in industry perceptions of the product, evidenced by conferences such as the recent MortgageFest Canada summit in Toronto.
“In the last two years, you’ve really seen a different shift in these types of conferences,” he said. “More and more there are panels, there are presentations around reverse, and it’s becoming a real solution.”
That transformation, according to Martin, has been helped by the rising skillset of brokers. “Today, I think they’re real mortgage advisers,” he said. “They’re there to strategize with their client and figure out different solutions.”
Growing attention to the product on the broker side can be attributed in part to changing demographics across Canada.
Tracy Valko (pictured, top right), a leading broker and founder of AIMI Mortgage Collective, highlighted the “very large” cohort of Canadians aged 55 or over, a share that’s only set to increase in the coming decades. “That’s going to give brokers the opportunity to look at equity-rich homeowners who are liquidity poor, and access that in a very responsible way,” she said.
Financial pressures bearing down on many Canadians are playing a role. With a significant share of mortgages renewing this year, Valko said brokers have a key opportunity to sit down with long-term clients and take stock of their full financial picture.
That means not just rate, but also debt load, cashflow, and longer-term needs. “We have a bigger responsibility, more than ever, to not just be their mortgage broker [with a] best-rate scenario – but more of that strategy, financial planning,” she said.
Christine Xu (pictured, top left), founder of Moneybroker Canada and a 26-year industry veteran, told CMP she’s witnessed the demand firsthand. She’s been running reverse mortgage seminars for clients – and each one fills within a day, an “overwhelming” level of response.
Bank of Mom and Dad a key factor behind product’s growth
One of the main reasons homeowners are turning to the product, Xu said, is as a way of navigating the affordability challenges facing their children.
The so-called “Bank of Mom and Dad” has become an increasingly prominent force in the Canadian mortgage market during the past 20 years, mainly because of the hurdles faced by younger homeowners in the face of rising home prices and downpayment requirements.
“I imagine a lot of the time, parents want to help their children,” Xu said. “Taking the reverse mortgage route is a very good option.”
Why brokers and their clients need to be cautious about reverse mortgages
But the product is not a blanket option for every client -a dn brokers need to approach it accordingly, Martin said, with a careful and comprehensive conversation before pushing ahead.
“Should it be for everyone? No,” he said. “And I think those are the questions you have to ask with the client: What is really the outcome you need? Is this really a solution that fits your needs? You want to protect them.”
That responsibility is exactly what makes the broker channel so well placed to drive the product’s growth, he said: a broker can assess the full picture of a client’s finances, their family situation, and their long-term plans before making a recommendation.
“It’s a way to continue living with dignity and their house and not be house poor,” he said. “And I honestly believe the help of brokers will increase the magnitude of this solution.”
Make sure to get all the latest news to your inbox on Canada’s mortgage and housing markets by signing up for our free daily newsletter here.