A reform pitched as a win at the coffee counter could cost builders a cash flow lifeline, with housing supply in the firing line

Eight cents on a coffee. Nearly 95,000 homes behind schedule. At first glance, Australia’s card surcharge ban and a deepening housing shortage have nothing in common.
But since the ban took effect on 1 October following the Reserve Bank of Australia (RBA)’s review of card payment costs, the two have become inextricably linked.
It’s a classic case of a butterfly effect that has roped in the Australian Taxation Office (ATO) and industry lobby groups, and has created a red-faced moment for Anthony Albanese’s ruling Labor Party.
Why the RBA scrapped card surcharges
Technically, the RBA did not outlaw surcharges itself; it simply allowed card networks to enforce a “no surcharge” rule on businesses (card networks have always preferred to ban surcharges since they discourage card use). eftpos, Mastercard, Visa and American Express all used that new freedom to prohibit merchants from surcharging.
What the ban has not removed is the cost on merchants of accepting a card payment. The RBA’s guidance acknowledges businesses will still pay these costs after surcharging ends, and says they can be built into a business’s overall pricing. According to the RBA, around 16% of Australian businesses surcharge, and they will decide whether to fold payment costs into sticker prices, as they do with every other cost.
In effect, your $5 coffee purchase will no longer show up as $5.08 on your bank statement. But the cafe is well within its power to simply jack the price of your coffee up at the point of sale.
This is where the ATO came in, since a tax bill cannot be legally repriced, unlike a cup of coffee. Because tax liabilities are set in legislation, commissioner of taxation Rob Heferen said the ATO cannot build card payment costs into prices. The ATO’s answer? Stop accepting credit cards altogether. Labor has since intervened to delay the ban until July 2027.
“It is not tenable for the ATO to absorb the costs associated with accepting credit cards on an ongoing basis. This would result in less revenue being collected by the ATO and ultimately, less funding being available for all government services,” Heferen said.
It is worth mentioning that credit card payments represented only 2.3% of total ATO collections in the 2024-25 tax year, per ATO data. Nonetheless, the timing has handed the federal opposition an easy window of attack.
While Albanese boasted that Australians will save money “every time you tap” and that their morning coffee could be cheaper, Liberal opposition leader Angus Taylor was quick to point out a contradiction.
“The prime minister is out today boasting about his ban on card surcharges. But there’s a catch,” he wrote on social media. “While small businesses are being told to absorb the cost of accepting credit cards, his own Tax Office has decided it won’t. Instead, the ATO will simply stop accepting credit cards altogether. You couldn’t make it up.” He called for Albanese to reverse “this ridiculous decision” immediately.
The ban itself grew out of the RBA’s Review of Merchant Card Payment Costs and Surcharging, launched in October 2024. The central bank’s Payments System Board published its final decisions in a Conclusions Paper in March 2026. It found that surcharging, introduced more than two decades ago to steer consumers toward more efficient payment choices, no longer worked: businesses surcharged all cards at one rate, enforcement proved difficult and cash use fell.
Alongside the ban, the RBA cut the caps on interchange fees – what a merchant’s bank pays the customer’s card issuer – and required more fee transparency. The RBA expects small businesses to benefit most from the lower caps, because they tend to pay fees closer to the existing limits. A cap on foreign-card interchange and some transparency changes are to follow in April 2027.
How the surcharge ban reaches housing supply
Housing Industry Association (HIA) chief executive of industry and policy Simon Croft said the ATO’s decision to scrap credit card payments has removed a legitimate payment option used by some businesses to help manage cash flow at a time when builders are being asked to absorb an increasing range of costs, taxes and compliance obligations.
“Each of these changes may appear manageable in isolation, but together they are placing increasing pressure on business cash flow, profitability and confidence,” he said. “Combined with elevated construction costs and tighter trading conditions, these pressures continue to make managing cash flow one of the most significant challenges facing residential building businesses.”
HIA has called on the ATO and the federal government to reverse the decision before it takes effect on 30 November.
Peter Esho (pictured, below), chief executive of specialist property finance firm 13X, which funds residential developers, puts it more bluntly: “Credit is the lubricant that keeps the housing engine turning over. A hit to cards is a hit to credit and cash flow.”
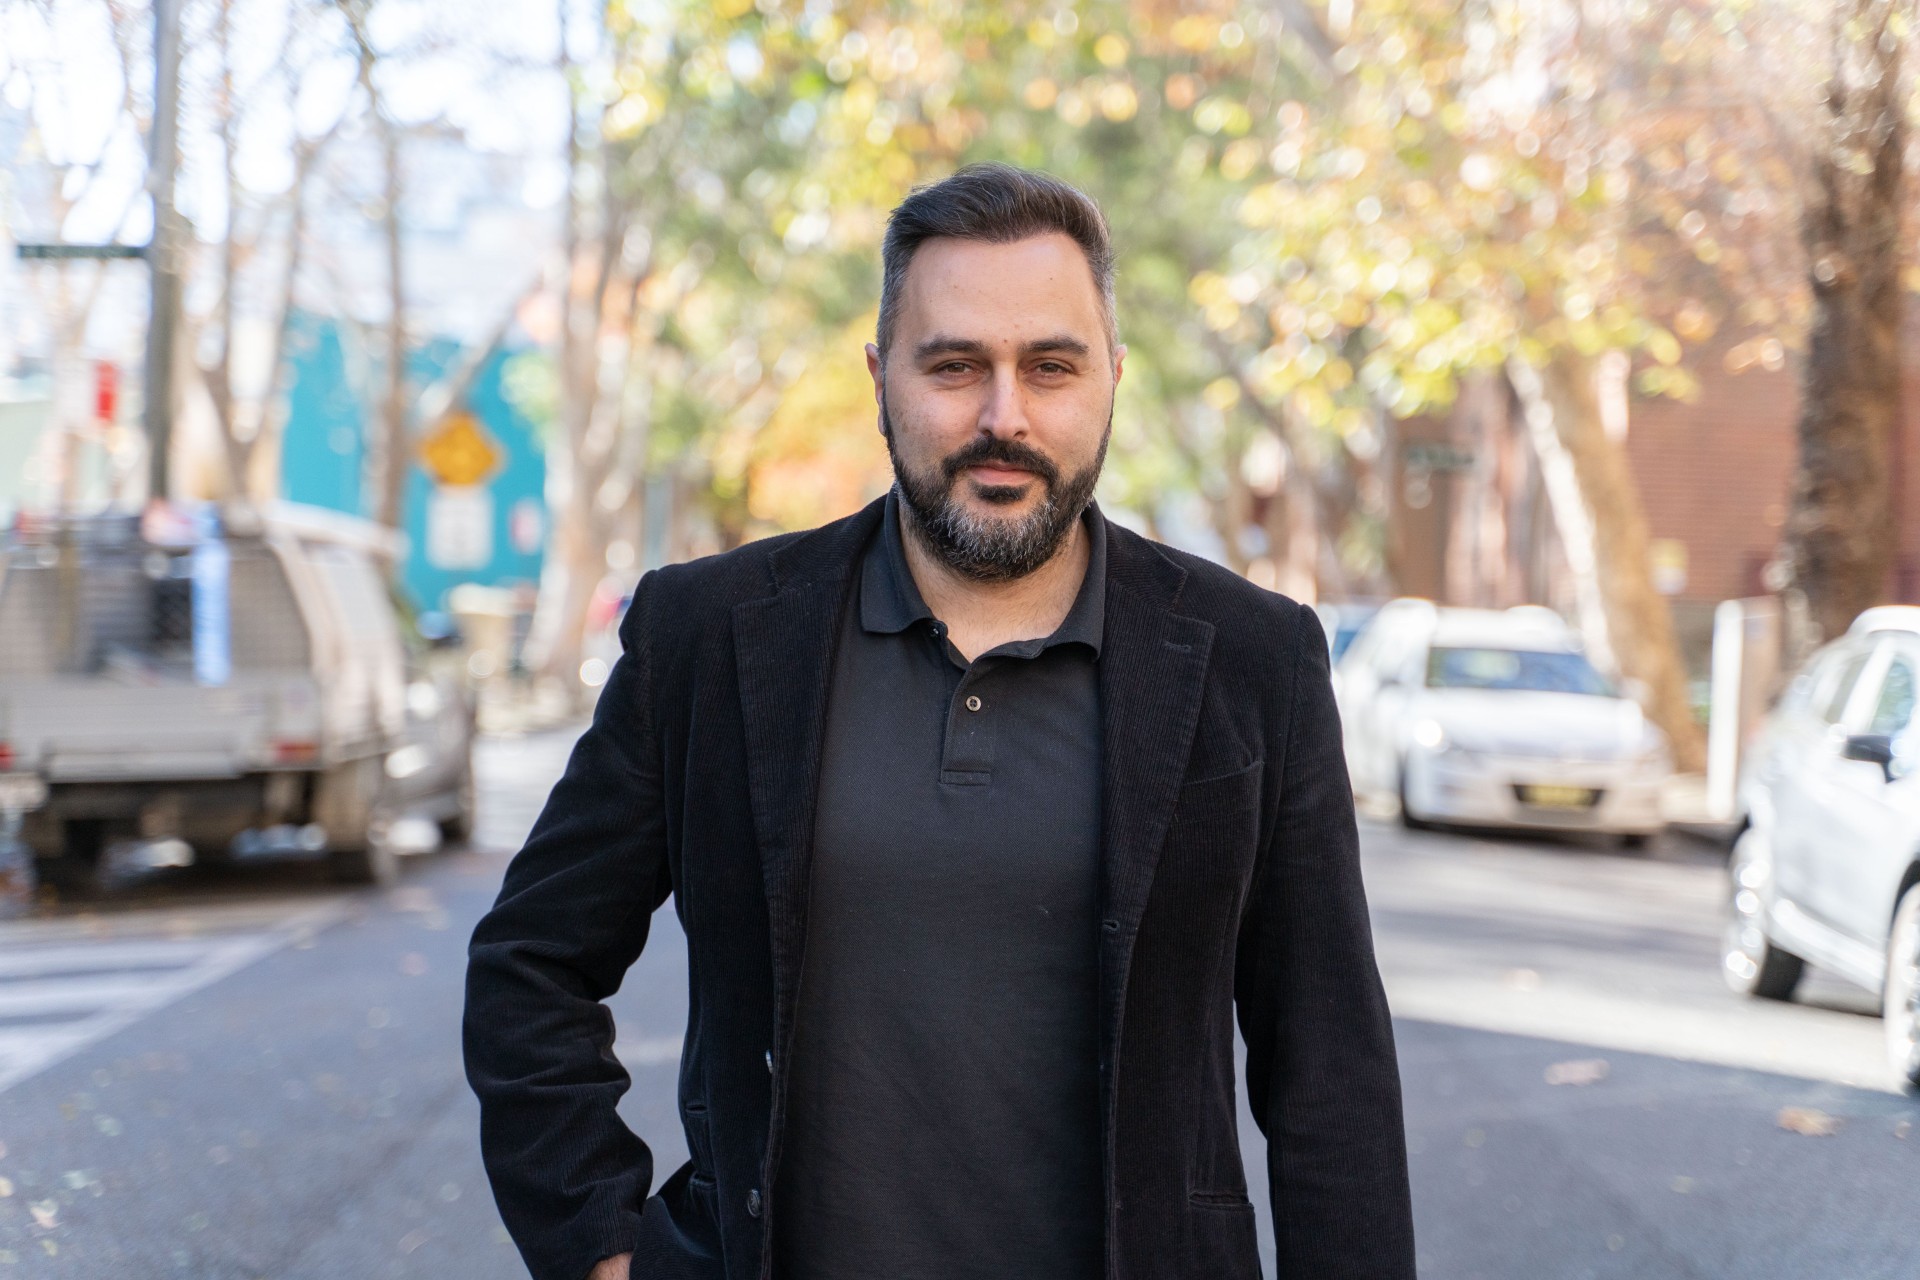
With HIA forecasting that Australia will miss its Housing Accord target by 186,000 homes, “Canberra’s response is to take a cash flow tool off the people who build them”, warned Esho. “The ATO’s change doesn’t collect a single extra dollar of tax. It just decides which builder runs out of runway first.”
Andrew McKellar, chief executive of the Australian Chamber of Commerce and Industry, called it “complete hypocrisy”, given how many small businesses rely on credit cards to manage cash flow.
Matthew Addison, chair of the Council of Small Business Organisations Australia (COSBOA), took a more measured tone. He said only a relatively small number of small businesses are expected to be affected, but agreed the change could add a cash flow challenge for those that are.
“While the proportion of small businesses using credit cards to make ATO payments may be relatively small, the impact for those businesses can still be significant. The concerns now being expressed publicly reinforce the need for the ATO to consider the practical consequences for affected small businesses,” said Addison.
Addison warned that removing the ability to surcharge without first ensuring lower payment costs are passed through leaves small businesses having to absorb those costs, all at a time of mounting cash flow pressure among small businesses.
Read more: SMEs shifting into survival mode, but their mettle shines through
“The ATO’s own response highlights that concern,” continued Addison. “If absorbing the cost of accepting credit card payments is not sustainable for a government agency, it is difficult to expect small businesses already operating on tight margins to simply absorb those costs themselves.
“COSBOA will continue to raise these concerns directly with the ATO and government through our established advocacy channels, and speak publicly where appropriate as the implications for small businesses become clearer.”
A supply problem that starts with funding
The bigger concern is what tighter cash flow does to a building pipeline that has been behind schedule ever since Australia fell 60,000 homes short in the Accord’s first year.
After the first two full years of the National Housing Accord, HIA analysis of Australian Bureau of Statistics (ABS) data shows Australia is nearly 95,000 dwellings behind its 1.2 million homes target. That works out to about 130 homes a day over two years.
HIA estimates the shortfall meant $2.8 billion in stamp duty and $8.2 billion in GST went uncollected over that period.
“I have said it for years: housing is a supply problem, and supply is a funding problem,” said Esho. “Back credible builders and developers properly and the stock comes forward. Prices ease, rents ease, cost of living eases. HIA says the shortfall has already cost governments $11 billion in stamp duty and GST. You do not fix an $11 billion hole by making it harder for builders to pay you.”
Esho also argued that the surcharge ban moves the merchant fee rather than removing it, and in construction, the fee ends up in the price of a home.
“The surcharge ban sounds like a win for consumers until you remember somebody still pays the merchant fee. In construction that lands on builders and trade suppliers on wafer thin margins, and it ends up in the price of the house. We have already watched big names in this industry fall over this year. We have a 1.2 million home target and a policy agenda built for about 900,000.”
So for coffee drinkers, the surcharge ban may mean a slightly higher price on the menu board. But for a building industry that is tens of thousands of homes behind schedule – not to borrowers watching fixed home loan rates rise as lenders price in further tightening – the cost may prove much harder to absorb.