Suspension of major ASX-listed real estate fund highlights emerging cracks in private credit – but is regulation really the answer?

The suspension of a major ASX-listed real estate fund this week is the latest sign of a broader reckoning underway in Australian private credit – one that has been building for months and shows no sign of slowing.
Metrics Real Estate Multi-Strategy Fund, run by the $40 billion Metrics Credit Partners group, was pulled from trading on Monday after admitting that unspecified "amounts" disclosed in its preliminary report "may differ materially" from the upcoming audited report.
At stake are questions surrounding valuations of Metrics' private-market investments, loan exposures and the fair value of its equity investments. It's an age-old issue for private investments – since they are not publicly traded, valuations are only assessed periodically using expert judgement, rather than letting the market decide in real time.
Later on Monday, Metrics Credit Partners revealed a $160 million write down across three of its ASX-listed funds, with the value of the Real Estate Multi-Strategy Fund falling by over 12% – from $388 million to $340 million.
“In finalising the audited results, greater weight was given to downside scenarios and less favourable potential outcomes,” Metrics told investors. “The resulting changes include revisions to expected cash flows, discount rates, capitalisation rates, development timeframes, end sale values and development costs.”
It is reasonable for the fund's responsible entity, Perpetual, to pull trading pending a proper audit, but is this a routine disclosure, or another crack for brokers to navigate in a sector the regulators have all but declared open season on?
Scrutiny deepens
Regulatory warnings are coming thick and fast for Australia's booming private credit industry.
A decade ago, private credit was a niche corner of Australian finance. Today it's a roughly $200 billion sector, according to Australian Securities and Investments Commission (ASIC) estimates, with independent analysis for the regulator putting growth at close to 500% over the past ten years.
That growth has brought significant attention to this relatively underregulated segment of mortgage finance (real estate accounts for an estimated 40 to 60% of private credit lending in Australia).
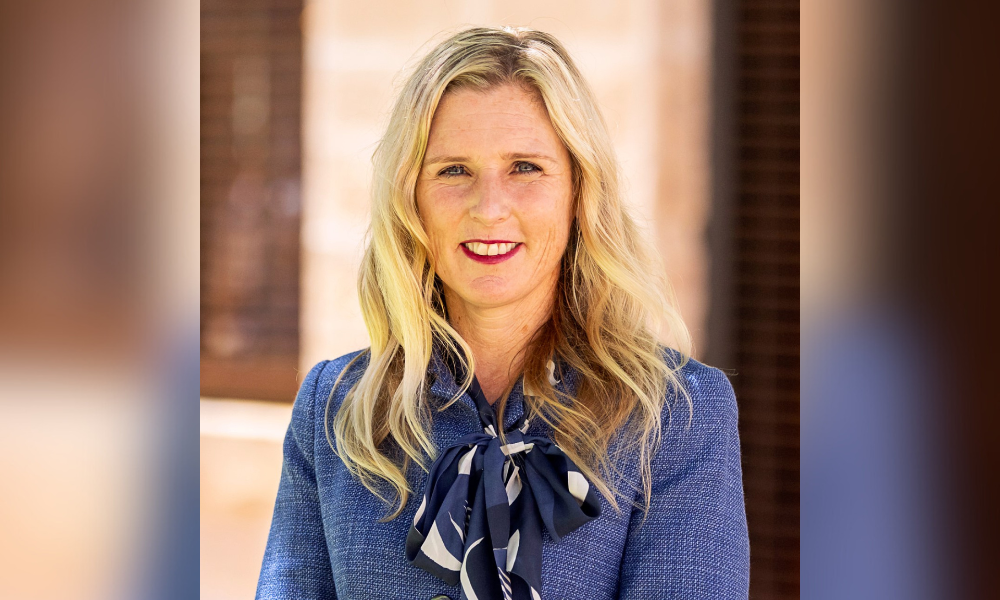
"We are now well beyond warnings," ASIC commissioner Simone Constant (pictured, above) said during a Commercial & Asset Finance Brokers Association of Australia (CAFBA) summit earlier this month. "The (private credit) sector should prepare for enforcement action."
Constant's comments followed the collapse of Bathla Group, the Western Sydney developer whose implosion has become private credit's defining case study – roughly $3.4 billion owed to more than 40 lenders, funnelled through some 540 special purpose vehicles, in a structure Constant pointedly noted had "almost twice the number of special purpose vehicles as employees".
Thousands of half-built homes have been left in limbo. Several lenders exposed to Bathla's projects – including CVS Lane, which froze applications and redemptions across two funds after disclosing exposure through nine separate loans, and Centuria Bass, which locked up several hundred million dollars belonging to its own investors – proceeded to shut the gate on investor redemptions rather than risk a run.
ASIC chair Sarah Court dubbed the Bathla episode private credit's "first real test", while Reserve Bank of Australia (RBA) governor Michele Bullock went a step further, warning a parliamentary inquiry that a serious implosion in the private credit sector "will wash back onto the banks."
Such heightened rhetoric has been running for over a year now.
Back in September 2025, ASIC chair Joe Longo warned the sector to lift its standards or face intervention, following the regulator's first deep dive into the market. Two months later, a follow-up review of 28 funds – spanning major managers like Metrics Credit Partners and La Trobe Financial through to newer entrants – found ASIC once again putting the sector on notice, flagging opaque fee structures, inconsistent default terminology and weak governance around related-party dealings.
By the time S&P Global Ratings weighed in, the consensus among analysts was that tighter oversight would ultimately strengthen the sector rather than hold it back – a view Constant's latest remarks suggest the regulator is now moving well past.
What is exactly being sold as credit?
There's an uncomfortable question sitting underneath these collapses and trading suspensions: is what's being marketed to investors as "private credit" actually credit at all?
The Metrics Real Estate Multi-Strategy Fund is a useful, if unintentional, case in point.
The fund's own materials describe a strategy built "across the full capital structure – from senior secured real estate debt through to real estate equity", roughly split down the middle.
While that's disclosed, not hidden, it's exactly the kind of structure ASIC's research flagged as a governance minefield well before Bathla made headlines.
Timbs and Williams' review of the sector for the regulator warned that "holding any combination of senior debt, mezzanine debt and equity positions in the same borrower can conflict decision making and actions during distress" – and that funds routinely use terms like "senior", "secured" and "investment grade" so loosely that investors have no real way to compare one product against another.
La Trobe Financial chief executive Chris Andrews argues that private credit has become a label rather than a genuine description of risk – with some funds now holding equity exposures "dressed as debt", while advertising the same target returns as far more conservative, first-mortgage lenders.
Where a manager uses investor money to fund related businesses or acquisitions rather than straightforward loans, that distinction should be obvious to investors long before a downturn forces the question. For Andrews, it comes down to a basic question: "Did my money buy a loan, or did it buy a business?"
David Bushby (pictured, below), chief executive of CAFBA, was blunt when asked whether this blurring between debt and equity was actually happening in the market his members operate in. "The answer to that is what I've heard is probably yes, that is happening," he told MPA – though he was careful to flag he was speaking secondhand rather than from direct oversight of any specific fund.
It's a pattern the Financial Services Council (FSC)'s Private Markets Best Practice Principles, released last month, was built to confront head-on, forcing private credit managers to disclose "borrower-paid fees, credit-related income, net interest margin arrangements and other economic benefits" that have historically let managers dress up returns while quietly shifting risk onto investors who thought they were simply earning interest.
"Where fund structures, SPVs, interposed entities or related-party arrangements materially affect fee or economic benefit flows, disclosure should enable investors to understand the nature and effect of those arrangements," reads the yet-to-be-implemented FSC guidance.
A cycle, not a crisis
Not everyone reads the current turmoil the same way. Andrews argues that much of what's being reported as a private credit crisis is really a property cycle doing exactly what property cycles do – finding out which lenders are legit, and which lenders are swimming naked.
National dwelling values have fallen roughly 3.6% from their March 2026 peak, and Commonwealth Bank expects a peak-to-trough decline of around 9%.
Measured against history, that's unremarkable: Australian house prices have corrected by a similar magnitude roughly every seven to ten years since 1980, with declines of 8.4% in both the 2017–19 and 2022–23 downturns – neither of which took more than 18 months to play out.
On that reading, the current pullback isn't unwinding the extraordinary run-up in prices since 2020; it's simply trimming it.
For Andrews, the real test isn't whether a downturn happens – it's whether a lender saw it coming. "It is utterly normal for developers... to experience financial stress periodically and, occasionally, to fail," he argues.
The only way a single borrower's failure becomes a problem for an entire fund's investors, in his view, is if that fund had already lent too much, without building in the diversification or liquidity to absorb the loss. A property downturn, in other words, isn't an excuse – it's precisely the scenario a well-run credit fund is supposed to be underwritten for.
It's a notably more measured take than the one coming from the regulator. Where Constant, Court and Bullock have all framed the current stress as evidence of a sector-wide problem demanding urgent intervention, Andrews' argument effectively shifts the blame downstream – onto individual managers who cut corners during the boom, rather than onto private credit as an asset class.
But whether that distinction offers much comfort to a broker with a client caught in a frozen fund, or an investor waiting on a delayed final report, is a different question entirely.
Self-regulate or be regulated?
As pressure on private credit ramps up, an existential question comes to the fore: Should regulation come from within or beyond?
Bushby leaves no doubt where CAFBA stands. "We are inherently as an organisation anti-regulation," he says. "We believe that an industry that self-regulates well delivers much better outcomes for everybody."
He points to ASIC's own 10 principles for private credit as proof the blueprint already exists – the industry just isn't always following it. "It's a pretty simple document. You look at it, there's nothing in there that's really stunning. But so many… or very few… are apparently following it."
ASIC's disclosure rules are limited in scope – they only bind retail products, leaving wholesale and ‘sophisticated investor’ funds largely outside of the equation.
"This means that two products both described as 'private credit' can carry very different disclosure obligations, and that the… benchmarks an investor might reasonably expect to compare them on will only have been reported by one," says Andrews.
While Andrews (pictured, below) has not made the case for or against unifying disclosure obligations across all product types, Bushby happily rejects the idea outright.
"We would say emphatically no to that," Bushby says. His argument: commercial borrowers are simply a different animal to retail mortgage customers, "generally a more sophisticated borrower", operating on an ongoing relationship rather than a one-off transaction.
The risk to brokers
Private credit's growth has been a genuine boon for brokers. Merely a decade ago, a client with a complex commercial or development deal that didn't fit bank lending criteria had few places to turn.
Today, brokers can choose from dozens of private lenders each offering different appetites, speeds and structures – a level of flexibility banks have never really matched, and one that's helped brokers win and retain clients who'd otherwise have been turned away.
But that choice comes with an underside the current wave of scrutiny is putting on full display.
A pipeline deal financed by a private lender isn't insulated from that lender's own balance sheet problems. If a fund is forced to freeze redemptions, pause new lending, or gets caught out by a valuation write-down, a loan a broker has already structured can simply stop moving – deposits paid, settlement dates locked in, and no guarantee the funding will actually turn up on the day it's needed.
The FSC's new Private Markets Best Practice Principles is meant to reduce exactly this kind of risk – forcing managers to hold proper liquidity buffers, price loans honestly and disclose fee structures and related-party dealings that have historically hidden how exposed a fund really is.
The problem is timing. The standard only binds the FSC's own Full Members, and even then not until 1 July 2027 – nearly a year away. Funds serving wholesale and sophisticated investors get an even lighter version of the rules.
In practice, that means the private lenders brokers are placing deals with today are operating under exactly the same light-touch conditions that produced Bathla, Metrics' current troubles, and the string of redemption freezes before them – with nothing mandatory changing until the new FSC standards come into effect next July.
Until then, the due diligence brokers do on a lender before recommending them matters more than ever, and largely falls on brokers themselves.
Thankfully, Bushby says CAFBA's own members haven't reported pre-approved commercial loans being pulled because a private lender ran short of capital – for now.