Separation, relocation, and over-leverage push recent buyers to sell below cost

Mortgage advisers say separation, relocation, and borrowing that stretched too far in the 2021 boom are pushing some recent buyers to sell at a loss, and they’re working through hardship options, rentals, and refinancing to help clients avoid a forced sale.
The comments follow Cotality’s Pain and Gain Report, which showed 15.8% of homes resold at a loss in the September 2026 quarter, the highest share since 2012, with loss-making properties held for a median of 4.5 years. Auckland (25.5%) and Wellington (20.4%) recorded the weakest results.
Hold, rent, or cut losses
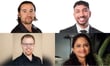
Rustam Nomozov (pictured upper left), mortgage adviser at Mortgage Lab, described a young Wellington couple who bought two rental properties in the capital region about six years ago, putting in roughly $400,000 of their own money. After moving overseas for work, they sold one at a loss of around $100,000. Selling the second would leave them with only $100,000 to $150,000 of their original investment, so, with a higher overseas income, they’ve chosen to hold it while it remains affordable.
Vijay Gounder (pictured upper right), mortgage adviser at Loan Market, said emotional attachment often keeps owners holding on. One client bought for $950,000, with the property now worth $800,000 against $750,000 of lending and is waiting to recover the loss rather than using the remaining equity to buy again in what advisers describe as a buyer’s market.”
Alan Borthwick (pictured lower left), certified financial planner at DUX Financial Services in Wellington, stress-tests how long a property might take to recover, drawing on his own experience of holding a rental that was worth less than he paid for nine years after 2008. He weighs that against the cost of waiting: a client $40,000 below their target price, subsidising the property by $2,000 a month, would spend roughly that amount in a year and a half. “If not now, when?” he said.
Advisers said renting out the property can work for clients who need to move, but only if the numbers add up after rates, insurance, maintenance, management, and vacancies. Property type matters too: advisers urged close scrutiny of body corporate fees, maintenance plans, and building issues for apartments, while Borthwick warned against off-the-plan rental townhouses in Christchurch where the numbers don’t stack up.
Life changes behind the losses
In Borthwick’s experience, job losses aren’t the main driver. Separations and relocations are more common, and buyouts are especially hard when there’s little equity. In one recent case, siblings and a couple who bought together four or five years ago planned for one party to buy the other out after five years, but one now wants to move to Australia and there isn’t enough equity to make it work.
Gounder pointed to a mix of job losses, with unemployment at its highest level since 2015, overseas opportunities, and heavy borrowing during the 2021 buying frenzy, when some buyers also took on car loans and other debts. Tradespeople who relied on equity and top-ups to fund renovations have been hit twice, he said, as property values fell for a seventh straight month and work dried up.
Options before a sale
Nomozov said the first step is working out whether the pressure is temporary or ongoing. Options include term extensions, interest-only periods, restructuring, hardship applications, and, for investors, selling one property to make the rest of the portfolio manageable. Lenders assess support case by case, so he presents a clear budget and a plan for when temporary help ends.
Gounder, who previously worked at New Zealand’s largest bank, said lenders want to avoid forced sales, noting “the banks do not like mortgagee sales due to the reputation repercussions”. Banks’ financial wellbeing teams can set up a six-month loan deferral, he said, and he has also used equity releases and non-bank lenders to help clients keep long-held family homes.
Borthwick added that lenders are generally supportive, but mortgage payment suspensions now have to be arranged through bank branches, so advisers must coach clients through the process. He also considers KiwiSaver hardship withdrawals.
Simi Sethu (pictured lower right), director of Kripa Financial Solutions, said refinancing can still help in the right cases. A Wellington client who bought for $1.03 million, with the property now worth about $830,000, had lending above the property’s value, making refinancing difficult, so Sethu secured discounted pricing with the existing bank through the client’s employment banking package. In Palmerston North, a client who had paid a low equity margin for more than three years was refinanced to another lender with a 0.25% rate discount and a $7,000 cash contribution.
Where a sale is unavoidable, Nomozov said a loss on the purchase price differs from negative equity: if proceeds won’t cover the mortgage and costs, the shortfall must be discussed with the lender before selling. Borthwick said remaining debt can sometimes be converted to a personal loan.
“Make the decision based on your future, not just the price you paid,” Nomozov said.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.