Top executives reveal what it takes to get a file across the finish line

For Canadian mortgage brokers who want more approvals in 2026, lenders have a clear piece of advice: tell their clients' story, and provide as much detail as possible about why a deal makes sense.
Executives from some of Canada's biggest players in the broker channel were on hand at last week's MortgageFest Canada (September 23–24) for a panel on prime lending and how brokers can navigate an increasingly challenging market.
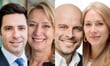
Elena Robinson (pictured, centre left), vice-president of residential sales at First National Financial, described the company's approach to lending as "prudent underwriting with a common-sense approach." She said brokers who present a clear, full picture of their client's situation are far more likely to get approval. "If the brokers provide that story to the lender, you're more apt to get a yes," she said.
Another practical stumbling block, meanwhile, is that deals can fall apart because brokers haven't confirmed property values before submitting. "Not only are they wasting the lender's time, but as a broker you're feeling the time wasted for yourself," Robinson said.
Bank of Montreal (BMO) is "very open for business" in the prime lending space, according to Jamie Doolittle (pictured, far right), head of BMO BrokerEdge, although she underlined a clear focus on sustainability. "We want to make sure that homebuyers can afford their home today and can afford their home tomorrow," she said. "So that sustainability of affordability and predictability is really, really important."
Where lenders are likely to apply greater scrutiny, Doolittle said, is where a borrower carries elevated debt ratios or where gaps appear in the application.
"We are very focused on making sure that the story and the documentation and the numbers align," she said. "Having those conversations upfront and telling that clear and concise story is going to allow underwriters to make a decision faster."
The value of a well-packaged file
The basics of a customer's profile are still fundamental. Enrik Brassard (pictured, centre right), associate vice-president, broker channel at National Bank, underlined the importance of a strong balance sheet. "It's nice to see clients that have savings, have investments, have shown good credit behaviour," he said.
"This is a client acquisition strategy, too – when clients come with other financial needs, this allows us to build a strong relationship throughout the life of the client."
Brassard also offered a practical reminder on file submission: a complete, well-packaged file on first submission has a far greater chance of approval than one that trickles in with follow-up documentation. "The file is at its nicest the first time you submit it," he said. "The more you submit, the murkier it gets – because then it seems like you don't know your client."
Growing file complexity a continuing trend
Risk appetite remains extremely important for lenders in a volatile and unpredictable economic environment. TD's approach hasn't shifted significantly this year, according to vice-president, broker services and operations Devon Ajram (pictured, far left) – but the complexity of the files coming in is increasing.
"Generations are now adopting multiple careers, side hustles, and revenue streams," he explained. "As mortgage brokers, what's becoming really important is being able to get a fulsome story on paper about who your customers are."
And even in cases where a borrower's profile is strong, lenders are continuing with a careful and rigorous approach. A good credit score and credit behaviour, Brassard said, do not absolve brokers and lenders of good due diligence. "You could have the greatest client in the world," he said, "but they still need to prove where they've got their money, their wealth, and their cash on hand."
Anti-money laundering and regulatory compliance requirements have added scrutiny around the source of funds, an area where broker collaboration is essential.
Ultimately, the panellists were agreed on a common point: brokers who submit complete, well-documented files and can clearly articulate their client's financial story are the ones winning approvals in the current environment. "Credit is manageable with a good story," Brassard said. "Due diligence is not manageable. It's black and white."
Make sure to get all the latest news to your inbox on Canada’s mortgage and housing markets by signing up for our free daily newsletter here.