What higher borrowing costs could mean for homebuying and the renewal wave
Fixed mortgage rates have been on the rise amid climbing bond yields in recent weeks and the Bank of Canada is now back in hiking mode, putting upward pressure on variable rates.
National homebuying activity was already weak before the central bank’s 25-basis-point hike on Wednesday, but mortgage industry figures fear the move could worsen the outlook for the housing market even further.
The Canadian Mortgage Brokers Association of Ontario (CMBA-ON) said it was “disappointed” by the BoC’s move, describing it as a decision that could have a big negative impact on consumer and investor confidence in a market that’s already been weighed down by global economic uncertainty and trade tensions.
Jessica Rickerby, CMBA-ON president, suggested that the decision had prioritized inflation over housing challenges. “While inflation is a key concern of Ontarians, so is housing affordability,” she said in remarks accompanying the statement.
“The difference is that affordability is a pressing issue right now, whereas inflation is – at present – only slightly above the Bank of Canada’s target rate.”
Higher rates have implications for the renewal picture
The recent jump in fixed rates has seen a growing number of Canadians turn away from those options and toward sometimes shorter-term variable options, a trend noted by Canada Mortgage and Housing Corporation (CMHC) in its latest residential mortgage industry report.
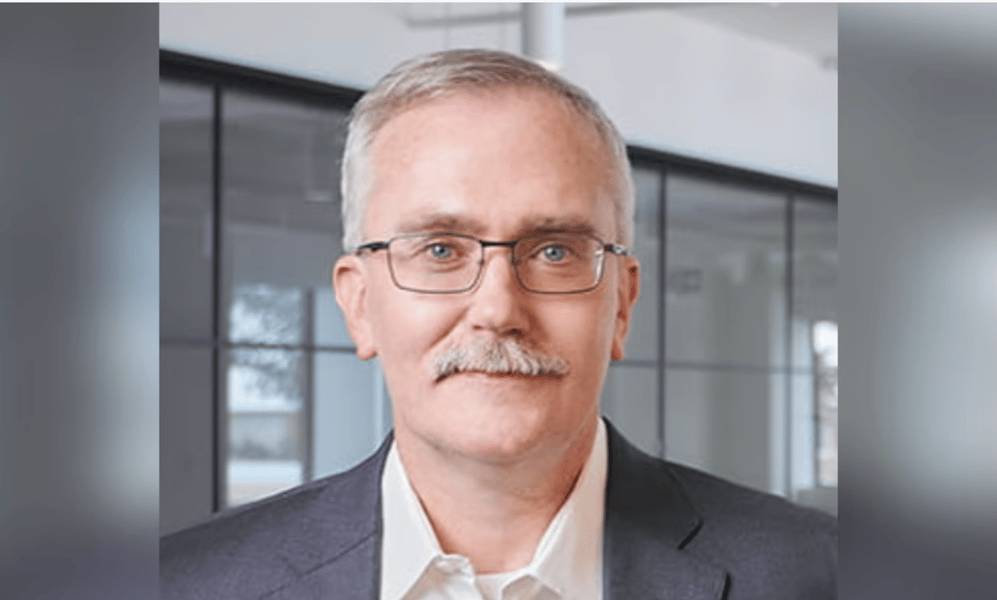
The much-discussed mortgage renewal wave, in which scores of pandemic-era mortgages have renewed at higher interest rates in 2025 and 2026, seemed to be past its peak. But if rates continue rising – and Canadians are increasingly choosing shorter mortgage terms – that could prolong renewal challenges, according to CMHC’s deputy chief economist Aled ab Iorwerth (pictured top).
“There is a move away from the five-year fixed towards shorter-term mortgages,” he told Canadian Mortgage Professional. “And interest rates have been going up. So I’m a little bit more concerned than I used to be in that area.
“I’m a little bit concerned that we’re going to have more of this discussion of renewal at higher interest rates. Perhaps my concerns won’t materialize – and I hope they don’t – but that is certainly an area that I’m more concerned about than I used to be.”
That’s not to say a series of big rate hikes by the Bank of Canada is in store. Instead, ab Iorwerth’s main concern is wider pressure in the lending system with the potential to drive bond yields and interest rates higher.
“US fiscal deficits, demand for money for AI, saving from an aging population – I see a lot of demand for savings, putting upward pressure on, say, five-year interest rates,” he said. “I wouldn’t tie it directly to the Bank of Canada. There’s going to be a lot of demand for money in order to invest in a range of different options.”
Speaking to reporters on Wednesday, the BoC’s senior deputy governor Carolyn Rogers indicated the central bank wasn’t expecting the housing market to pick up pace any time soon.
“Certainly, borrowing rates are currently weighing a bit on the housing market,” Rogers said after the Bank’s announcement. “An increase will add to that a bit on the margin, so I think the outlook we’ve got for housing in the forecast… takes all of that into account.”
What the hike means for commercial mortgages
Rising bond yields and inflation concerns have clouded the outlook for the commercial lending sector – but Mark Fieder, principal and president at Avison Young Canada, struck a bullish tone on the space’s prospects after the BoC’s latest move.
“Despite this rate hike, we anticipate demand for institutional-quality commercial real estate will remain strong,” he said, “supported by durable income, downside protection, and long-term portfolio stability.
“Pricing for premier assets will stay competitive, particularly in the industrial and multifamily sectors. Transaction activity will be increasingly governed by asset quality, lease profile, and growth prospects.”
Make sure to get all the latest news to your inbox on Canada’s mortgage and housing markets by signing up for our free daily newsletter here.