KiwiSaver contributions key to closing gap with Australia, Marsh index finds

New Zealand’s retirement income system has posted a record score, but it still trails Australia, which has earned an A grade for the first time, according to the 2026 Marsh CFA Institute Global Pension Index.
New Zealand scored 71.4, up from 70.4 in 2025, keeping its B grade and placing 15th of 55 systems. The index, compiled by Marsh with CFA Institute and the Monash Centre for Financial Studies, attributed the rise mainly to higher net replacement rates reported by the Organisation for Economic Co-operation and Development (OECD) and an increase in the household savings rate.
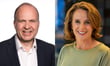
Report lead author Tim Jenkins (pictured left), a partner at Marsh, said New Zealand had “posted its best result in the ten years it has been in the Index”. New Zealand also kept its A grade for integrity, with a score of 84.
Where the gap lies
Australia scored 80.6, joining the Netherlands, Denmark, Iceland, Singapore, and Israel among the six A-grade systems.
Jenkins said the shortfall was “about adequacy and financial sustainability”, meaning how much income New Zealanders will have in retirement and whether the system can keep delivering. He pointed to the systems’ design: Australia has had compulsory superannuation contributions for more than 30 years, while KiwiSaver is younger and voluntary.
New Zealand’s weakest result was adequacy, where it scored 66.5 and ranked 34th. It fared better on sustainability, scoring 68 and ranking 11th.
Marsh New Zealand chief executive Anna Scott (pictured right) said the report’s path to a higher score was clear, and that “most of it comes back to how much goes into KiwiSaver and how it is used in retirement”.
What would lift the score
The index suggested New Zealand could lift its score by raising KiwiSaver contribution levels, coverage, and tax efficiency, and by making retirement income KiwiSaver’s main purpose with more drawdown options. It also recommended raising household savings and reducing household debt.
Those goals can pull against each other. The New Zealand Institute of Economic Research has warned that higher KiwiSaver contributions could slow mortgage repayments for households with no other savings to redirect.
Ageing pressures ahead
This year’s report focused on ageing populations, as falling birth rates and longer lives put more strain on pension funding worldwide. Workforce participation among New Zealanders aged 65 and over rose 16% over the past 20 years, one of the largest increases in the index and second only to Singapore.
Scott said New Zealanders needed to plan beyond immediate household budget pressures.
“The lesson is – the earlier we start, the easier it will be,” she said.
Stay informed with the latest housing market trends and mortgage insights — subscribe to our free daily newsletter.