Top lenders at MortgageFest Canada say alt lending is now the prime solution for many Canadians

The image of alternative lending as a short-term fix for borrowers with damaged credit has, by most measures, run its course.
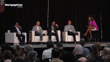
At MortgageFest Canada, held at Mississauga’s International Centre, senior executives from four of the country’s leading alt lenders made a straightforward argument: the channel has matured into a primary solution for a wide and growing share of the Canadian borrower base, and brokers who continue to treat it as a backup option are forgoing significant business.
“The alternative space is part of your prime option now,” said Cam DelliPizzi, regional sales director at MCAN Financial.
“It’s as simple as that. And if you’re not thinking about it that way, you’re losing opportunity for yourself.”
A borrower profile that no longer fits a single box
The shift is structural, not cyclical. As qualification criteria at Canada’s major chartered banks have narrowed under regulatory pressure, a growing range of creditworthy clients — self-employed borrowers, entrepreneurs, holders of multiple investment properties, and those navigating divorce or Canada Revenue Agency obligations — have landed in the alternative channel not because of damaged credit, but because of how banks define qualifying income.
Grant Armstrong, chief growth officer at WealthONE Bank of Canada, offered a data point that reframes the conversation: the average FICO score among his institution’s alternative borrowers sits at 763. That's a number that, he noted, outperforms some Big Six portfolios in certain segments.
“Banks have very, very specific ways of looking at income,” Armstrong said.
“That’s where the alternative lenders can come in and have a different risk appetite — to be able to say, we want to look at that cash flow of the business. Some of our clients have multiple properties — bank statement approach, investment properties, holdcos — stuff that’s just a little bit outside of what the traditional bank is.”
Joel Cote, chief operating officer at Haventree Bank, described the evolution as a reclassification rather than a demotion.
“It’s no longer, for many, a short-term solution,” he said.
“For many clients that fit this profile, the alt solution is the prime solution.”
As Canadian mortgage debt continues to swell past record levels, the proportion of borrowers whose income structures fall outside conventional bank parameters is only expected to grow.
Packaging files and building lender relationships
For Prakash Bector, vice president of sales and distribution at EQ Bank, the sharpest opportunity for brokers in the alt space lies in how they prepare and present files.
For self-employed clients in particular, income verification requires understanding the full shape of the business — revenue, overhead, how the client structures expenses — not just a line-15 figure.
“The more equipped you are upfront, the easier it’s going to be for all of us to be able to assess the deal and give you a quick answer and move the file along,” he said.
The panelists were united on one practical step that few brokers take: call the lender’s business development manager and ask directly how income is calculated.
Armstrong noted that of more than 100 brokers in the room, fewer than 2% had done so. That single conversation, he argued, can redefine a broker’s performance in the alt space.
Brokers looking to sharpen their edge with alternative lenders would do well to start there.
“Build the package for the lender,” he said. “If you build it for yourself, it doesn’t help the lender.”
Cote offered a clear summary of what separates approvals from declines.
“What kills deals are surprises,” he said. “The more info that we know upfront, the better equipped we are to try to navigate a solution.”
As artificial intelligence begins reshaping how mortgage brokers handle file complexity and client communication, the ability to build clean, transparent files quickly is only going to matter more.
Make sure to get all the latest news to your inbox on Canada’s mortgage and housing markets by signing up for our free daily newsletter here.