Laberge suggests BoC will keep rate increases on ice for 2026 – but says 2027 could be a different story
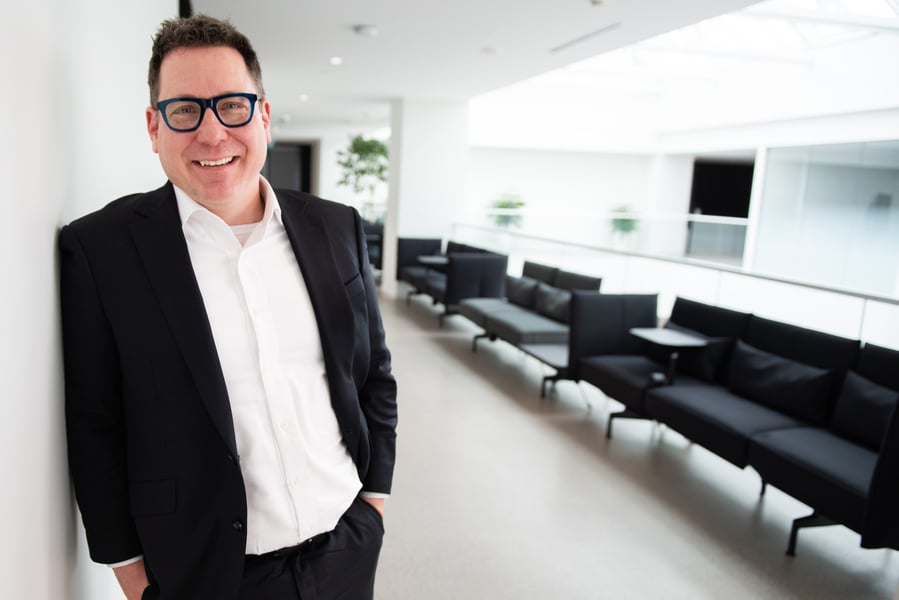
Canada Mortgage and Housing Corporation (CMHC) chief economist and senior vice president Mathieu Laberge (pictured top) doesn’t see the Bank of Canada raising rates in 2026 despite surging odds of a hike.
Laberge told an audience at this weekend’s Mortgage Professionals Canada (MPC) National Conference in Calgary that he believes the central bank will keep rates unchanged for the rest of the year because of a weak economy, although he still sees rate hikes ahead in 2027.
“I don’t see rates going up anytime soon,” Laberge said. “The reason is yes – there’s inflation. Governor Macklem was really, really clear that he has no tools to do anything about global inflation. He could kill the economy as much as he wants, and kill domestic inflation, but current inflation is coming from supply chain disruption and oil prices due to war in Ukraine and the Strait of Hormuz.
“He’s very conscious about that, and his choice is moving on something for optics to say ‘We’re doing something,’ and having a detrimental impact on the economy, or just saying, ‘Well, it’s hard, but we can’t do anything about it.’”
Choppy economy could keep BoC on hold, says Laberge
The Bank is scheduled to meet at the end of this month (October 28), with speculation about a possible hike either this time around or in December intensifying amid persistent inflation and a more aggressive Federal Reserve south of the border, which increased rates in its last decision.
But the Canadian economy’s sluggish performance has continued. In September, the jobs market posted its worst month of the year, with the economy losing 68,300 jobs and the unemployment rate jumping to 6.5%.
Laberge suggested the shaky economy would likely keep rate hikes on ice, although he said mortgage market watchers should pencil in sooner-than-expected 2027 increases.
“The economy is not extremely [strong] right now. We saw the labour market numbers,” he said. “So my hunch right now is: not before 2027. Our previous forecast was mid-2027. We may bring that forward a little, so maybe end of Q1, early Q2 2027, but I don’t see anything this year.”
The Bank has left its benchmark rate unchanged throughout this year, maintaining a wait-and-see approach as trade tensions with the US continue and oil prices creep higher because of the continuing US-Iran war.
Mortgage renewals: Borrowers coping, but risks remain
Amid a volatile economy and rising fixed rates, one of the stories of the year has been the mortgage renewal wave, in which scores of borrowers have renewed their mortgage at much higher rates than they first took out.
During the COVID-19 pandemic in 2020 and 2021, rates were at rock-bottom – but they’ve since soared, leading to a glut of five-year mortgages expiring in a higher-rate environment.
While borrowers have generally handled that well, Laberge cautioned that the market isn’t out of the woods yet, particularly with the choppy economy continuing.
“The renewal shock may be easing for some households, but the risk has not vanished,” he said. “It has moved. It’s sitting in existing portfolios. It’s more regionally concentrated than it’s ever been, and the resale conditions are softer.
“It also shows up for very specific household types like first-time homebuyers or those who didn’t have as much time to build equity and are now facing decreases in house prices. And so this is a very different story from saying Canada has broad mortgage distress – but we need to keep an eye on where all of this is going.”
Make sure to get all the latest news to your inbox on Canada’s mortgage and housing markets by signing up for our free daily newsletter here.